
Table of Contents
- Debt Consolidation as a Strategic Financial Move
- Improving Cash Flow Through Debt Consolidation
- Debt Consolidation vs. Corporate Refinancing: Key Differences
- Strategic Timing: When Growth‑Stage Companies Should Consider Debt Consolidation
- Impact on Future Venture Capital and Capital Structure
- Lender Evaluation Criteria for Mid‑Sized Firm Debt Consolidation
- Making an Informed Decision on Debt Consolidation
Debt Consolidation as a Strategic Financial Move
For lower middle market businesses, commercial debt consolidation is a strategic financial move that can unlock growth potential. By combining multiple obligations—such as term loans and lines of credit—into a single facility, companies can simplify management and strengthen their balance sheet, turning a complex liability structure into a platform for expansion.
Restructuring liabilities in this way can lower total interest costs and improve monthly cash flow, freeing up capital for acquisitions, working capital, or market expansion. At Zaidwood Capital, our Debt Advisory team structures consolidation strategies tailored to each company’s situation, leveraging our proprietary data platform and deep investor network. Through our comprehensive investment banking services, we support businesses in executing debt consolidation strategies that align with long-term growth objectives, not just short-term crisis management.
We view consolidating debt as a proactive tool for financial optimization—one that empowers leadership teams to redeploy resources toward value creation.
Improving Cash Flow Through Debt Consolidation
Beyond simplifying monthly obligations, a well-structured debt consolidation plan directly enhances cash flow. For businesses managing multiple high-interest obligations, consolidating these into a single facility can meaningfully reduce total monthly debt service, freeing up immediate working capital. Our Debt Advisory team at Zaidwood Capital helps clients evaluate whether a consolidation approach aligns with their broader capital strategy.
How Consolidation Improves Working Capital
When a business carries several loans or credit lines with varying rates and terms, the combined monthly payments can strain operating liquidity. By consolidating debts into one loan with a potentially lower cost of capital and a fixed repayment schedule, monthly cash outflows become more predictable and often lower. This predictability allows management to forecast working capital more accurately and allocate resources toward growth rather than debt service.
A consolidation strategy may involve asset-based lending or a structured term loan, depending on the company’s balance sheet and objectives. Our team works to align the facility structure—whether through extended amortization or interest-only periods—with the client’s specific cash-flow needs. This tailored approach helps ensure that the newly freed capital can be redirected strategically, such as funding organic expansion, covering operating expenses during seasonal slowdowns, or investing in professional services like tech M&A advisory fees to execute a growth-through-acquisition plan.
Strategic Applications of Freed Cash Flow
The immediate benefit of lower monthly obligations is tangible, but the strategic value is equally significant. Businesses that successfully restructure debt often find themselves better positioned to pursue capital formation initiatives, M&A opportunities, or market expansion without the constant pressure of servicing high-cost debt. As a Boutique M&A and Capital Advisory Firm, we view debt consolidation not as an isolated tactic but as part of a Full-Cycle M&A and capital strategy that supports long-term value creation.
With a clearer cash-flow picture, businesses can evaluate the next phase of their capital strategy—whether that involves growth equity, acquisition, or further debt optimization.
Debt Consolidation vs. Corporate Refinancing: Key Differences
Now that we have outlined the basics of capital restructuring, let us examine the key differences between debt consolidation and corporate refinancing. For many businesses, managing multiple high-cost obligations creates unnecessary complexity and strain on working capital. Recent bank mergers have reshaped the lending landscape, directly influencing the availability and attractiveness of both strategies. Zaidwood Capital helps clients navigate these options with precision.
In debt consolidation, a company combines several outstanding debts into a single loan with one manageable payment. This approach aims to simplify cash management and can lower borrowing costs depending on the credit profile and market conditions. It typically streamlines payment schedules across credit cards, revolvers and short-term notes, simplifying covenant monitoring and treasury forecasting. In contrast, corporate refinancing replaces an existing loan with a new one to secure better terms, extend maturities, or alter the debt structure. While consolidating debt primarily reduces payment complexity, refinancing corporate obligations adjusts the cost of capital to align with current business cycles.
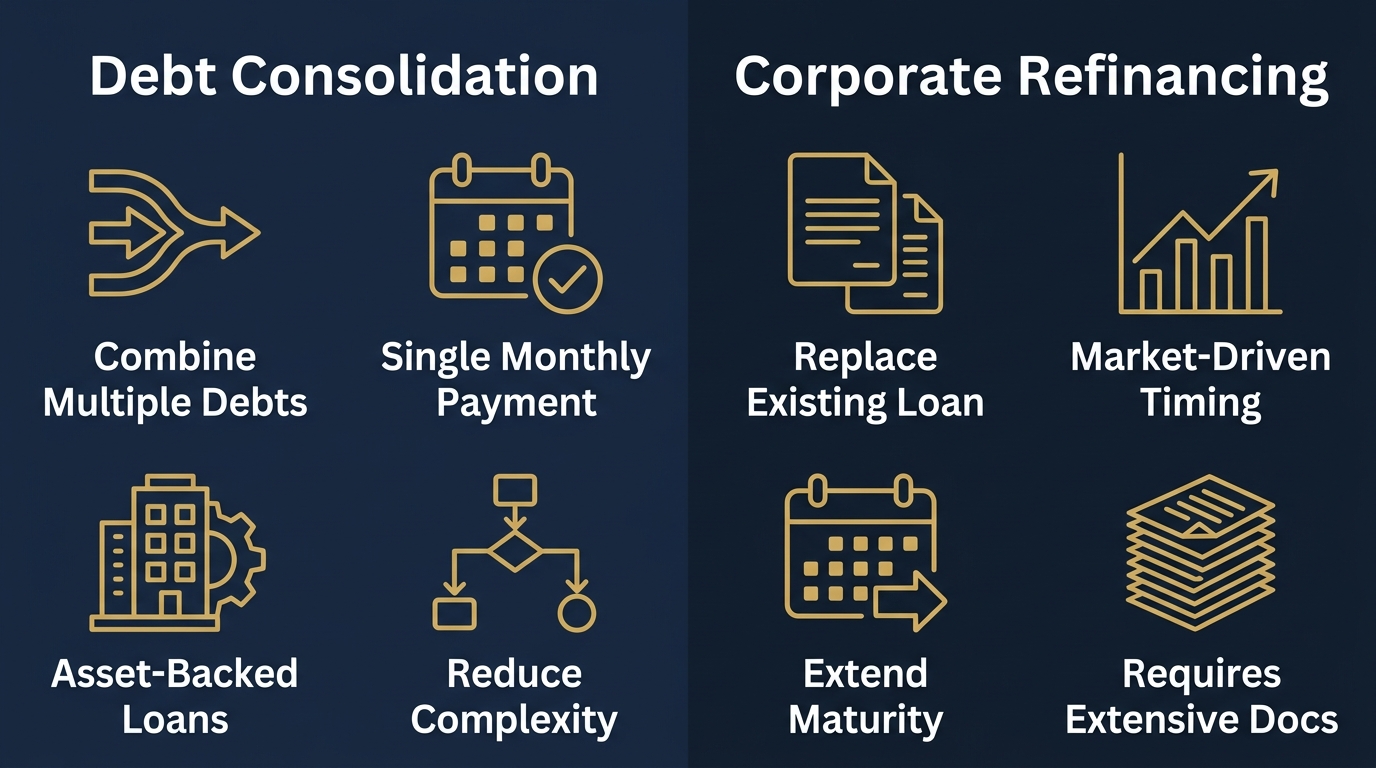
Key differences between debt consolidation and corporate refinancing
Both strategies improve cash flow but through distinct mechanisms. A firm pursuing debt consolidation often uses asset-based or working capital loans that streamline multiple high-interest obligations. Corporate refinancing typically demands more extensive financial documentation and rigorous due diligence, as lenders reassess the entire capital structure. This path generally requires more extensive documentation, longer lead times and thorough lender assessments that test consolidated balance-sheet strength and cash-flow resilience. According to analysis by Zaidwood Capital, the ongoing consolidation among regional banks has reduced the number of active lenders, which can tighten credit availability and shift the relative appeal of each option.
We help clients weigh tradeoffs. Understanding these differences helps businesses choose the right path, which we explore further in the next section on implementation strategies for capital restructuring.
Strategic Timing: When Growth-Stage Companies Should Consider Debt Consolidation
Understanding when to consolidate is as critical as knowing how — growth-stage companies often miss optimal windows due to delayed decision-making. At Zaidwood Capital, we observe that debt consolidation becomes a pivotal lever when management teams face a convergence of financial pressure and strategic opportunity. Rather than treating it as a reactive measure, we advise founders and CFOs to evaluate consolidation timing proactively, using a clear set of diagnostic triggers.
Three conditions frequently signal that the moment is right for a consolidation strategy:
- Post-funding clean-up – After a Series A or B round, growth-stage companies often carry high-cost bridge notes, convertible instruments, or merchant cash advances that dilute the benefit of fresh equity. Consolidating these scattered obligations into a single term loan with a lower blended rate can simplify the capital structure and free up operating cash flow.
- Margin strength meets service cost drag – When gross margins are sustainably positive but EBITDA remains negative, a closer look often reveals that fragmented debt servicing — multiple interest schedules, divergent covenants — is the culprit. Refinancing multiple debt facilities at this juncture often removes the drag and reveals a healthier core business.
- M&A readiness – Companies pursuing an acquisition, whether as buyer or target, benefit from a clean balance sheet. Zaidwood Capital’s business acquisition financing advisory frequently integrates liability consolidation as a strategic step, reorganizing outstanding working capital lines and acquisition-related notes so the transaction can proceed without legacy distraction. Growth-stage companies should verify that their consolidation plan meets FINRA investor protection and compliance standards, especially when investor capital is involved.
Beyond these triggers, we recommend a simple diagnostic: If your weighted average cost of debt exceeds 15%, have you evaluated consolidating into a single term loan with a lower blended rate? Sustainable consolidation also depends on cash-flow visibility — lenders typically expect 12 or more months of predictable recurring revenue or a robust contract pipeline before approving a restructuring package.
Distinguishing between working-capital debt (AR financing, inventory lines) and acquisition-related debt matters, because each carries different risk profiles and collateral implications. In our experience as a Boutique M&A and Capital Advisory Firm, the most successful consolidations occur when the timing aligns with a deliberate Full-Cycle M&A or expansion roadmap — not as a hurried fix, but as a measured recalibration of the balance sheet ahead of the next growth phase.
Once timing is confirmed, the next step is evaluating consolidation structures, which we cover in the following section.
Investments involve risk and are not guaranteed to appreciate; investors may lose all or part of their investment. This content is for informational purposes only and does not constitute an offer, solicitation, or commitment for any financial transaction. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is unaffiliated with Finalis.
Impact on Future Venture Capital and Capital Structure
With the due diligence framework established, we now turn to how these findings directly shape your ability to attract venture capital and build a resilient capital structure. Thorough due diligence can surface opportunities for debt consolidation and balance sheet optimization that strengthen your financial profile and increase investor confidence.
When your operational, financial, and legal records are validated by comprehensive due diligence, the information asymmetry that typically keeps VC investors cautious is significantly reduced. This transparency helps position your business as a lower-risk opportunity, often accelerating the fundraising timeline and helping you negotiate terms that better reflect your company’s actual worth.
Unaddressed risks—whether legal exposures, operational inefficiencies, or financial gaps—are among the most common deal-breakers in venture capital negotiations. Our due diligence framework surfaces these vulnerabilities early, giving you the opportunity to remediate them before they become investor objections. Proactive resolution may also uncover opportunities for debt consolidation or working capital refinancing that strengthen your capital structure ahead of an equity raise.
A clean due diligence report can also support higher valuations and more favorable debt-to-equity ratios in subsequent funding rounds. Our framework aligns with securities industry advocacy and compliance standards, ensuring your capital structure decisions meet current regulatory expectations. When analysis reveals that your cash flows can comfortably service additional obligations, pursuing debt restructuring may prove more strategic than issuing dilutive equity. Zaidwood Capital’s venture capital fundraising service—leveraging a network of over 4,000 institutional investors and access to more than $15 billion in deployable capital—directly benefits from the depth of our due diligence findings, positioning you to attract growth capital on stronger terms.
Ultimately, the due diligence process does more than prepare your company for a transaction—it creates the conditions for a more rational capital structure and a more credible equity story. At Zaidwood Capital, we view this not as a one-time exercise but as an ongoing strategic discipline that can improve your access to venture capital, support efficient debt consolidation when appropriate, and help you navigate the complex interplay between equity and debt financing. Once your capital structure is optimized, the next phase is executing a post-transaction integration that locks in those gains for the long term.
Lender Evaluation Criteria for Mid-Sized Firm Debt Consolidation
To capitalize on the strategic benefits of debt consolidation, firms must first assess potential lenders against a structured set of objective criteria, beginning with core financial health metrics. Lenders typically evaluate a mid-sized company’s leverage using a debt-to-EBITDA ratio, with industry benchmarks commonly clustering between 3.0x and 4.0x for firms pursuing consolidation, according to capital-market data tracked by the Securities Industry and Financial Markets Association (SIFMA). Beyond this leverage threshold, a firm’s cash-flow coverage ratio becomes equally telling, demonstrating the ability to service consolidated obligations from operating income without straining working capital. Collateral requirements form the next layer of scrutiny, where receivables, inventory, and equipment are the asset classes most frequently accepted, and loan-to-value ranges are calibrated against those assets to protect both borrower and lender. When evaluating debt consolidation lenders, we also focus on covenant structures, because mid-market loan agreements often carry affirmative covenants mandating regular financial reporting and negative covenants that restrict additional indebtedness or asset sales; the presence of covenant-light or covenant-flexible provisions can signal a lender’s willingness to accommodate growth-stage volatility. Prepayment flexibility is equally critical in a consolidation strategy: typical structures include yield maintenance provisions that compensate the lender for foregone interest or step-down schedules that reduce the penalty as the loan matures, and both directly influence a firm’s ability to refinance as conditions improve. Beyond the term sheet, a lender’s track record with similar-sized consolidation transactions and relevant industry specialization, contextualized by SIFMA insights into mid-market lending activity, offers a window into execution reliability and sector understanding. Regulatory standing must also be verified, and FINRA rules on fair dealing and disclosure provide a baseline for confirming that any prospective lender meets its communications and suitability obligations. Consolidating existing debt without this due-diligence step can expose a firm to compliance gaps that erode the very efficiency the consolidation seeks. We recommend applying a weighted evaluation framework—allocating roughly 40% to financial health, 30% to loan structuring terms, and 30% to lender credibility and regulatory compliance—so that no single metric drives the decision. Applying these criteria positions a firm to select a partner aligned with its long-term financial goals.
Making an Informed Decision on Debt Consolidation
An informed decision on debt consolidation begins with a clear articulation of your objective—whether you aim to reduce interest costs, simplify repayment structures, free up operating cash flow, or position for growth. This clarity becomes the benchmark against which every consolidation structure is measured.
A thorough review of current debt terms and prevailing capital market conditions is essential.
As the Securities Industry and Financial Markets Association (SIFMA) reports, interest rate trends directly influence the attractiveness of consolidating commercial debt, making market timing a critical component of the evaluation. We weigh the trade-off between short-term liquidity relief and long-term cost of capital—a refinancing decision that may lower monthly obligations but could extend repayment tenure or trigger prepayment penalties.
Equally important is assessing counterparty strength and structural flexibility, as restrictive covenants in a new facility can constrain future operations. Our full-cycle advisory framework at Zaidwood Capital stress-tests these assumptions, helping you determine whether a debt restructuring aligns with your broader strategic plan. Investments involve risk, and past performance does not guarantee future results.