
Zaidwood Capital

Category: Working Capital Solutions

  • What Is Supply Chain Financing? Complete 2026 Guide

    What Is Supply Chain Financing? Complete 2026 Guide

    Table of Contents

    The Essentials of Supply Chain Financing for Business Leaders

    Supply chain financing (SCF) encompasses solutions such as reverse factoring and dynamic discounting that allow buyers to extend payment terms while suppliers receive early payment from a financial institution. This working capital optimization tool has become essential for business leaders seeking to strengthen liquidity and supplier relationships.

    Effective SCF arrangements involve three key stakeholders: the buyer, the supplier, and the financing provider. As a Boutique M&A and Capital Advisory Firm, we understand that buyers can improve Days Payable Outstanding (DPO) and suppliers can reduce Days Sales Outstanding (DSO) while lowering supply chain disruption risk. Unlike traditional factoring or invoice discounting, which are supplier-centric, SCF is a buyer-led approach that does not add debt to the buyer’s balance sheet and often enhances overall liquidity. By accelerating cash conversion cycles, SCF can free up internal funds for growth investments without increasing leverage.

    Our asset-based lending and working capital solutions can support SCF programs by providing the capital that flows between trading partners. Drawing on a network of over 4,000 investors and access to $15B+ in capital, Zaidwood Capital can structure bespoke working capital facilities that complement SCF arrangements. However, it is critical to recognize that supply chain financing does not guarantee improved financial outcomes. Each arrangement involves risk and requires thorough due diligence; companies should consult their own legal and financial advisors before proceeding.

    Understanding these fundamentals sets the stage for exploring the specific structures available for implementing an SCF strategy.

    How Supply Chain Financing Benefits Buyers and Suppliers

    Supply chain financing benefits both buyers and suppliers by optimizing payment cycles and strengthening trade relationships. Unlike traditional trade credit, which often pits buyer and supplier interests against each other, this strategic working capital tool enables companies to manage cash flow more effectively without incurring additional debt. We at Zaidwood Capital help clients implement these programs, creating value on both sides of the transaction.

    Benefits for Buyers

    For buyers, supply chain financing extends days payable outstanding (DPO) without damaging supplier trust. By allowing a company to defer payments to a later date—often up to 60 or even 90 days—while the supplier receives early payment through the financing platform, the buyer preserves cash that can be reinvested in growth or used to reduce existing debt. This arrangement mirrors the working capital preservation achieved through equipment financing: just as equipment loans allow a business to acquire assets without depleting cash reserves, supply chain financing frees up liquidity that would otherwise be tied up in short-term payables. Moreover, offloading early-payment pressure to a third-party funder strengthens supplier relationships, giving suppliers reliable capital access that fosters collaboration and reduces disruption risk. We advise structuring programs so extended terms don’t strain partnerships.

    Benefits for Suppliers

    For suppliers, supply chain financing provides early payment at a far lower cost than factoring or merchant cash advances. By leveraging the buyer’s credit profile, suppliers can convert approved invoices into cash within days rather than waiting 30, 60, or 90 days. This rapid liquidity reduces reliance on expensive debt consolidation, which merely restructures old obligations without improving ongoing cash flow. Supply chain financing acts as a form of working capital for merchants, offering early payment without traditional debt. Suppliers can use the accelerated payments to fund raw material purchases, meet payroll, or invest in efficiency improvements without taking on high-cost debt. Unlike reactive restructuring, SCF aligns payment timing with actual cash conversion cycles, helping suppliers maintain a healthy debt-service coverage ratio and avoid the downward spiral that often triggers the need for consolidation. This flexibility is especially valuable for middle-market companies operating with thin margins.

    These mutual benefits make supply chain financing a cornerstone of modern working capital management, transforming payment cycles into strategic assets for both parties. We at Zaidwood Capital help businesses design programs that unlock these advantages. Next, we will discuss how to implement a program effectively.

    Supply Chain Financing vs. Traditional Factoring: A Detailed Comparison

    Having explored the fundamentals of supply chain financing, we now compare this buyer-centric approach with traditional factoring. The differences in structure, risk, and relationship dynamics can substantially impact a company’s working capital strategy.

    The Working Capital Optimization Framework

    Supply chain financing is a cornerstone of modern working capital optimization, enabling companies to accelerate cash flow while preserving strong buyer–supplier relationships. By converting approved invoices into early payments for suppliers, this buyer-led approach shortens the cash conversion cycle and reduces days payable outstanding without straining the buyer’s own liquidity. In a typical SCF structure, the buyer approves an invoice and a third-party funder pays the supplier at a discount, with the buyer settling the full amount on the original due date—effectively extending the buyer’s DPO while injecting early cash into the supplier’s business. We integrate supply chain finance into a broader liquidity strategy that considers asset-based lending, dynamic discounting, and—where appropriate—global lending services to optimize cash flow across the supply chain.

    A well-designed supply chain financing program not only frees up cash tied in receivables but also provides suppliers with access to lower-cost credit, which in turn strengthens supply chain resilience. The framework evaluates invoice volumes, supplier segmentation, and payment terms to identify which invoices are best suited for early discounting, as opposed to traditional factoring or outright payment term extensions. As a boutique M&A and capital advisory firm with deep expertise in payables advisory and asset-based lending, we help mid-market businesses structure these programs to complement existing bank lines and support growth objectives. This disciplined approach ensures that SCF delivers measurable improvements to the weighted average cost of capital and working capital ratios.

    Key Differences from Traditional Factoring

    While both supply chain financing and factoring accelerate supplier payments, they differ sharply in initiation, relationship impact, and cost. The table below outlines six critical dimensions that corporate treasurers should weigh when selecting a working capital tool.

    Feature Supply Chain Financing Traditional Factoring
    Initiation Buyer-initiated, based on approved invoices Supplier-initiated, often requires sale of receivables
    Buyer/Supplier Relationship Strengthens partnership; buyer facilitates early payment Can strain relationship; supplier bears cost and gives up control
    Cost Structure Lower cost, often tied to buyer’s credit rating Higher discount rates; fees based on receivable quality
    Risk Credit risk primarily on buyer; lower overall systemic risk Supplier risk (non-payment by buyer) can be transferred to factor
    Flexibility Scalable; can be selectively applied to approved invoices Often requires selling entire receivable portfolio; less granular
    Credit Dependence Primarily buyer’s credit profile Supplier’s credit and the creditworthiness of its customers

    Because supply chain financing is buyer-initiated, it fosters a collaborative process: the buyer approves an invoice and invites the supplier to discount it, reinforcing commercial trust. Traditional factoring, by contrast, is supplier-driven and can strain relationships when a supplier sells receivables without the buyer’s knowledge, often signaling cash-flow pressure. Cost structures illustrate another clear divide—supply chain financing leverages the buyer’s stronger credit rating to secure lower financing rates, a dynamic confirmed by Securities Industry and Financial Markets Association (SIFMA) credit risk benchmarks that associate buyer-led programs with reduced default probabilities and cheaper terms. Factoring, however, prices risk based on each receivable’s quality, resulting in higher overall costs for the supplier.

    Risk allocation also separates the two approaches. Supply chain financing concentrates credit exposure on the buyer, who is typically a lower credit risk, thereby limiting systemic consequences for the funder. Factoring transfers non-payment risk to the factor, but that protection is embedded in the discount rate and ultimately borne by the supplier. On the flexibility front, a supply chain financing program can be tailored to specific approved invoices, giving treasurers precise control over cash outflows. Factoring frequently requires the sale of the entire accounts receivable portfolio, which sacrifices granularity and strategic liquidity management. Finally, credit dependence underscores a key accessibility advantage: SCF programs tie to the buyer’s credit profile, enabling even smaller or lower-rated suppliers to obtain affordable early payment, whereas factoring examines both the supplier’s credit and the creditworthiness of its customers, potentially excluding weaker participants from cost-effective options.

    These comparisons illustrate why many growth-focused companies prefer supply chain financing as a cornerstone of their working capital strategy. By selecting the right tool, companies can avoid the pitfalls of one-size-fits-all financing and strategically manage liquidity. The infographic below distills the core contrasts visually.
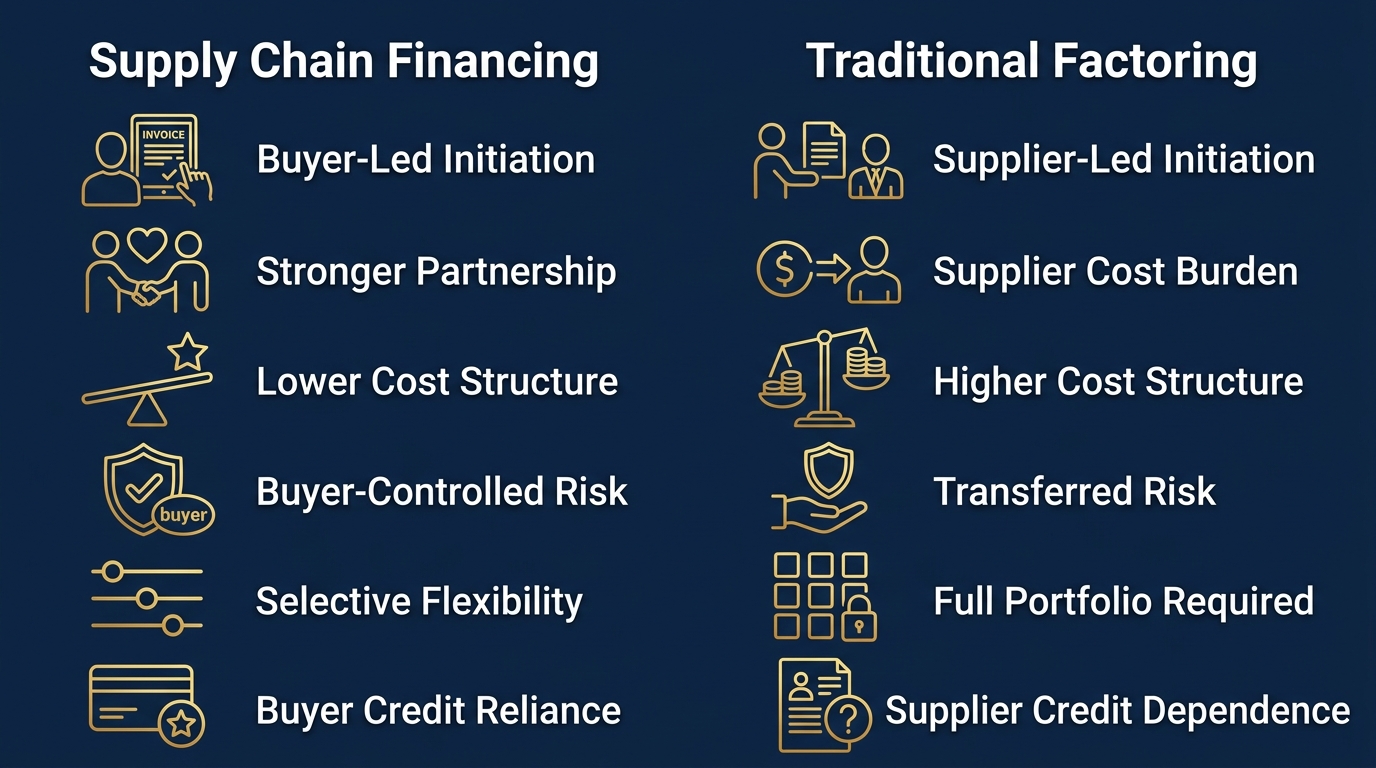
    Two-column comparison infographic showing Supply Chain Financing versus Traditional Factoring with gold outlined icons on deep navy background
    Supply chain financing vs. traditional factoring comparison

    In practice, adopting supply chain financing can reduce total financing costs, deepen supplier loyalty, and build a more resilient supply chain. For mid-market firms, the buyer-led model often aligns incentives across the supply base more effectively than traditional factoring. As the next section explores, implementing such a program demands careful alignment of invoice processes, funding partners, and payables strategy to match your company’s risk appetite and growth objectives.

    Managing Risks and Best Practices in Supply Chain Finance Implementation

    Identifying and Mitigating Implementation Risks

    While supply chain financing delivers significant liquidity benefits, companies must navigate a range of operational, credit, and regulatory risks. A disciplined risk assessment and a mitigation plan tailored to each category protect both the buyer and its supplier community.

    Risk Category Description Mitigation Strategy
    Buyer Credit Risk Risk of buyer defaulting on approved invoices Thorough credit assessment; use credit insurance or guarantees
    Supplier Onboarding Complexity Difficulty in educating and onboarding numerous suppliers Phased rollout; dedicated supplier support team; clear communication
    Legal/Regulatory Compliance Non-compliance with securities or lending regulations Engage legal counsel; comply with FINRA and state regulations (e.g., through Finalis for securities)
    Technology Integration Integration with existing ERP/accounting systems Use API-first platforms; pilot with a subset of transactions
    Program Scalability Unable to scale to larger supplier base or transaction volumes Design flexible program parameters; partner with experienced finance provider

    Among these, buyer credit risk and legal/regulatory compliance demand the highest attention. Buyer credit risk can undermine the entire program if an anchor buyer cannot meet its obligations, making robust credit analysis and, where appropriate, credit insurance or guarantees essential. On the regulatory side, any supply chain finance structure that touches securities must align with industry rules. The guidelines published by the Securities Industry Trade Association and FINRA emphasize rigorous compliance frameworks. We reinforce that Zaidwood Capital is not a registered broker-dealer; all securities transactions are conducted through Finalis Securities LLC, ensuring that programs adhere to applicable regulations without exposing the sponsoring company to unauthorized activities. Proactive legal counsel and early engagement with compliance resources help contain these risks.

    Best Practices for Program Success

    A well-designed supply chain financing program incorporates best practices that accelerate adoption, maintain operational integrity, and adapt to evolving business needs. Drawing on our experience with middle-market working capital solutions, we recommend the following:

    1. Structured supplier education and dedicated support. Phased rollouts, clear communication of the program’s value, and a dedicated onboarding team reduce friction and drive higher supplier participation. Suppliers that understand how early payment improves their cash flow are far more likely to enroll and remain active. Buyers can further incentivize early adoption by offering favorable early payment terms during the initial phase.
    2. Technology-first platform selection. Choose API-first platforms that integrate seamlessly with existing ERP and accounting systems. A pilot phase with a subset of transactions validates system performance before full-scale deployment. Our own Precision Catalyst platform illustrates how data-driven matchmaking and digital engagement can streamline supplier onboarding and transaction processing—without adding unnecessary complexity. The Velocity Matrix framework ensures technology deployment stays aligned with execution timelines.
    3. Ongoing performance monitoring. Establish KPIs such as days payable outstanding (DPO), supplier adoption rates, and early-payment discount capture. Regular reviews of these metrics, combined with feedback loops from suppliers, allow for continuous refinement. As we discuss in our debt consolidation and cash-flow resources, improving working capital efficiency often depends on visibility into real-time financial data and disciplined performance tracking. Internal dashboards and structured supplier surveys reinforce the feedback loop and provide early warnings.
    4. Scalable program architecture. Design flexible program parameters from the start, including tiered financing limits and the ability to add new suppliers without major reconfiguration. Partnering with an experienced finance provider that understands middle-market dynamics ensures the program can grow alongside the buyer’s transaction volumes. Regular scalability reviews help the program keep pace with corporate growth.

    With these best practices in place, companies can confidently explore more advanced SCF structures and unlock the full strategic potential of their working capital.

    Evaluating Supply Chain Financing as a Strategic Capital Solution

    Beyond traditional debt and equity, supply chain financing (SCF) provides a strategic way to optimize working capital without diluting ownership or incurring high-interest debt. SCF is a suite of solutions that improve cash flow by allowing buyers to extend payment terms while suppliers receive early payment on approved invoices, enhancing supply chain resilience.

    SCF typically involves a third-party financier—often a bank or fintech—that advances funds to suppliers based on the buyer’s approved payables. For example, a manufacturer in West Palm Beach could approve a $100,000 supplier invoice, have the financier pay the supplier immediately, and then repay the financier 90 days later, preserving its own working capital. The supplier gains faster access to cash, often at a lower cost than factoring, while the buyer strengthens the relationship and reduces supply chain risk.

    When evaluating SCF as a strategic capital solution, we consider several criteria: the cost of capital relative to other short-term financing, whether the arrangement is treated as on- or off-balance-sheet debt, how seamlessly it integrates with existing ERP and invoicing systems, and its scalability as transaction volumes grow. Unlike business acquisition financing—where Zaidwood Capital structures layered debt and equity for transformative transactions—and the capital raises we advise for food and beverage brands, SCF focuses on recurring working-capital needs rather than one-time events. It is not a one-size-fits-all solution; companies must assess their cash conversion cycle, supplier concentration, and financial covenants. Like all financial solutions, supply chain financing carries costs and risks that must be evaluated carefully. Additionally, businesses should verify that any SCF platform or financier complies with applicable regulations, including oversight by the Financial Industry Regulatory Authority.

    SCF is most valuable for companies with stable buyer-supplier relationships and predictable payment cycles, helping them unlock trapped cash to fund growth without sacrificing equity. However, it is only one part of a comprehensive capital strategy, and advisory guidance can help firms choose the right mix.

    Frequently Asked Questions About Supply Chain Financing

    Now that we’ve covered the fundamentals of supply chain financing, let’s address common questions.

    What is supply chain financing? Supply chain financing is a collaborative, technology-enabled set of solutions that optimize payment terms between buyers and suppliers, improving working capital without traditional borrowing.

    Who can benefit from supply chain financing? Mid-market and growth-stage companies seeking to strengthen supplier relationships, reduce supply chain risk, and free up cash for strategic initiatives are ideal candidates for supply chain finance.

    Does Zaidwood Capital offer supply chain financing advisory? Yes. As a Boutique M&A and Capital Advisory Firm, we advise on supply chain financing within our Asset-Based Lending / Working Capital advisory. Results vary; we recommend independent due diligence and consultation.

    Leveraging Supply Chain Financing for Sustainable Growth

    Beyond traditional capital formation, supply chain financing optimizes working capital between buyers and suppliers. According to Zaidwood Capital’s global lending guide, types like invoice financing, reverse factoring, and dynamic discounting unlock liquidity, while specific solutions such as equipment financing address asset needs without draining cash reserves. This approach underpins our full-cycle advisory, leveraging over $15 billion in accessible capital to match businesses with the right financing mix. Through our advisory in asset-based lending, we integrate these instruments to fuel sustainable growth, always within a risk-managed framework.

    Resources

  • Commercial and Industrial Loans: Complete Guide for Businesses

    Table of Contents

    Understanding Commercial and Industrial Loans

    Commercial and industrial loans — commonly referred to as C&I loans — are short-to-medium-term financing solutions designed to fund a company’s daily operations, working capital needs, or capital expenditures. These instruments form a core part of corporate debt financing, and businesses can access them on either a secured or unsecured basis.

    In practice, companies qualify for C&I loans through one of two primary frameworks: asset-based lending or cash flow financing. Asset-based lending centers on the quality of a borrower’s collateral, such as inventory, equipment, or accounts receivable. Cash flow financing, by contrast, emphasizes the strength of historical and projected revenue streams.

    According to Zaidwood Capital’s own advisory resources, institutional investors evaluate applicants using additional metrics — including a detailed business plan, audited financial statements, and multi-year cash flow projections — before matching a company with an appropriate lender. While banks have long dominated this space, a growing pool of institutional investors now provides business loans for commercial purposes, offering a viable alternative for mid-market and growth-stage firms.

    Zaidwood Capital’s Debt Advisory practice helps businesses navigate these two qualification models, acting as a bridge to institutional capital sources. Through its platform, Zaidwood Capital provides global lending services that connect companies with the right C&I lending partners, ensuring a structured and transparent path to financing.

    Commercial and Industrial Loans vs. Other Financing Options

    While the previous section outlined what C&I loans are, this section helps you distinguish them from other common financing products. Understanding the distinctions between commercial and industrial loans, commercial real estate loans, and equipment financing is essential for any business owner evaluating the right capital structure. Each product is designed to meet fundamentally different business needs, from funding day-to-day operations to acquiring major assets. At Zaidwood Capital, we help clients navigate this landscape, leveraging our advisory expertise and access to over 4,000 institutional investors to secure the right financing for their unique situation.

    C&I Loans vs. CRE vs. Equipment Financing
    FeatureCommercial & Industrial LoansCommercial Real Estate LoansEquipment Financing
    Primary Use CaseWorking capital, inventory, operational expensesAcquiring, developing, or refinancing real propertyPurchasing machinery, vehicles, or technology
    Collateral TypeReceivables, inventory, equipmentReal estate asset being financedEquipment being acquired
    Repayment TermShort to medium term (1–5 years)Long term (10–30 years)Medium term (3–10 years)
    Interest Rate TypeFixed or floating, tied to working capital cyclesFixed or floating, typically lower spreadsFixed or floating, often with equipment retention clauses

    The primary use case immediately highlights the distinct purpose for each loan. Commercial and industrial loans are the go-to solution for fueling organic growth, covering payroll, and managing seasonal inventory swings. In contrast, commercial real estate loans are structured for the long-term acquisition or development of property, reflecting the extended lifespan and stable value of real estate assets.

    When we look at collateral, C&I loans typically rely on a company’s assets like accounts receivable, inventory, and existing equipment. This differs significantly from CRE loans, where the property itself serves as collateral, and equipment financing, where the newly purchased machinery, vehicles, or technology secures the debt. This collateral structure directly influences the repayment term, where C&I loans often operate with shorter 1-5 year horizons aligned with operational cycles, whereas CRE loans can amortize over much longer periods of 10 to 30 years.

    These differences underscore why there is no single “best” option—only the right instrument for a specific business objective. Our advisory process, highlighted on our Raise platform, involves a detailed review of a company’s financial standing, cash flow projections, and strategic goals to match you with appropriate lending structures.

    Comparison of C&I loans, commercial real estate loans, and equipment financing options.

    Understanding these differences is the first step. The next section will walk you through the qualification process for a C&I loan. We encourage you to review the details carefully, and when you’re ready to explore how a tailored debt solution can support your growth, you can Book A Call with our team.

    This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to transact. This is not investment advice; please consult your legal, tax, and financial advisors before making decisions.

    Collateral, Eligibility, and Loan Structuring for C&I Lending

    Beyond the basic loan purpose, successful C&I financing depends on three pillars: collateral, borrower eligibility, and loan structure. For businesses seeking commercial and industrial loans, understanding how lenders assess each of these areas is essential to securing terms that align with operational needs and growth goals. Our advisory team at Zaidwood Capital helps companies navigate these criteria, drawing on institutional requirements to build a strong lending case.

    Types of Collateral in C&I Lending

    The collateral securing the facility is a primary driver of advance rates and overall credit appetite. Lenders evaluate asset quality, liquidity, and valuation risk to determine how much they are willing to advance against each class. The table below summarizes the most common collateral types accepted in C&I loans, alongside their typical advance ranges and how institutional lenders generally view each asset class.

    Accounts receivable financing consistently receives the most favorable treatment, with advance rates reaching 70 to 90 percent. Because these assets convert to cash relatively quickly, they represent the most liquid form of collateral in C&I lending. Inventory, by contrast, carries more uncertainty. Advance rates of 30 to 60 percent reflect obsolescence risk, shelf-life concerns, and the challenge of liquidation if a borrower defaults. Equipment and machinery can provide solid collateral support at 50 to 80 percent of appraised value, provided the assets are well-maintained and have a clear secondary market. Real estate, while strong, is often carved out for commercial real estate-specific products rather than traditional C&I lines.

    Lender Eligibility Criteria

    Institutional lenders apply a consistent set of financial metrics to gauge a borrower’s ability to service C&I obligations. Per Zaidwood Capital’s guidance on asset-based lending, a debt-service coverage ratio of 1.25x or higher is a typical baseline. This means the company’s operating cash flow should cover all scheduled debt payments with a comfortable margin. Lenders also examine liquidity through the current ratio, generally expecting it to remain above 1.0x, though stronger ratios improve negotiating power.

    Beyond ratios, the documentation package is critical. Institutional investors require audited financial statements covering at least the last three fiscal years, detailed accounts receivable aging reports, and third-party inventory or equipment appraisals. The U.S. Securities and Exchange Commission’s reporting standards underpin many of these requirements, ensuring that the financial information lenders rely on meets a recognized threshold of accuracy. Our role is to assemble and present this package in a format that aligns with how institutional credit committees evaluate risk.

    Loan Structuring: Rates and Terms

    Once collateral and eligibility are confirmed, the loan structure defines how the capital is priced and repaid. Interest rate choice is often the first decision point. Variable-rate loans are typically tied to the Secured Overnight Financing Rate, or SOFR, plus a spread that reflects the borrower’s credit profile and transaction size. While this structure can offer lower initial costs, payments fluctuate with market conditions. Fixed-rate loans carry a premium for the interest-rate certainty they provide, making them attractive for companies that prioritize predictable budgeting over potential savings in a declining rate environment.

    Repayment terms can be just as important as the rate itself. For businesses with uneven revenue cycles, seasonal or deferred payment structures are often built into the agreement. For capital-intensive purchases, equipment financing can be structured with seasonal or deferred payment plans, linking directly to our detailed FAQ. This flexibility allows borrowers to match debt service to cash generation, reducing strain during off-peak periods. With the collateral and structure defined, the next step is preparing a complete application package. To discuss how these terms can be tailored to your specific situation, we invite you to Book A Call for a custom quote.

    Strategic Uses of C&I Loans: Working Capital and Equipment Financing in Practice

    Now that we understand the broad benefits of C&I loans, let’s explore two of their most strategic applications in practice. Commercial and industrial loans provide the structured capital that businesses need for specific operational and growth objectives, from managing day-to-day cash flow to acquiring essential equipment. At Zaidwood Capital, our Debt Advisory team helps clients navigate these applications, structuring solutions that align with both immediate needs and long-term business plans.

    The following table matches common business needs to the appropriate loan structure, documentation requirements, and typical use cases.

    Common Collateral Types for C&I Loans
    Collateral TypeDescriptionTypical Advance RateLender Preference
    Accounts ReceivableInvoices from creditworthy customers70%–90%Highly preferred due to liquidity
    InventoryRaw materials, WIP, finished goods30%–60%Moderate; depends on obsolescence risk
    Equipment & MachineryFixed assets with appraised value50%–80%Good; stable collateral if well-maintained
    Real EstateCommercial or industrial property60%–75%Strong, but often used in CRE-specific products

    These three structures cover the most frequent strategic uses of C&I loans we encounter in our advisory work. Selecting the right one depends on your specific objective, the collateral available, and the documentation you can provide to support the request.

    Financing Working Capital with C&I Loans

    For businesses facing seasonal demand fluctuations or uneven cash flow cycles, working capital financing through an asset-based revolving line of credit offers a practical solution. This structure uses your company’s accounts receivable aging and inventory reports as collateral, creating a borrowing base that increases as your operational assets grow. Rather than waiting for customer payments to arrive, you draw against the value of outstanding invoices and on-hand inventory to cover immediate needs.

    Qualifying for this type of facility requires clear cash flow projections that demonstrate your ability to service the debt across different points in your business cycle. Lenders reviewing your application will want to see consistent patterns in your A/R aging, turnover rates on inventory, and realistic forward-looking projections that account for both peak and off-peak periods.

    A real-world example helps illustrate how this works in practice. Consider a wholesale distributor in Baltimore that experiences a predictable seasonal inventory buildup ahead of the summer months. To purchase stock and cover operating expenses during the slower winter period, the business establishes an asset-based line of credit secured by its receivables and inventory. This structure provides the liquidity needed to make supplier payments on time without depleting cash reserves, and the credit line contracts as receivables are collected, keeping the cost of capital aligned with actual usage.

    All documentation and loan structuring must comply with relevant securities regulation and investor protection standards where applicable. For the working capital example above, the key documents needed include:

    • Accounts receivable aging reports showing outstanding invoice balances and due dates
    • Inventory reports detailing stock levels, valuation, and turnover rates
    • Cash flow projections covering seasonal peaks and troughs

    Equipment Financing: A Practical Application

    Commercial and industrial loans also provide a structured path for acquiring machinery, vehicles, or IT infrastructure without depleting working capital. Equipment financing typically takes the form of a term loan secured by the purchased asset itself, meaning the equipment serves as collateral for the loan. This approach preserves liquidity while allowing the business to put the new asset to productive use immediately. According to internal resources from Zaidwood Capital, the process follows a clear, step-by-step sequence.

    Start by obtaining a professional equipment appraisal to establish the fair market value of the machinery you want to purchase. Next, secure a detailed invoice or purchase order from the vendor that specifies the equipment, pricing, and delivery terms. With these documents in hand, our Debt Advisory team can structure the term loan to match the useful life of the equipment, with repayment terms that align to your projected cash flow from using the asset.

    Businesses with seasonal revenue patterns can also benefit from structured flexibility in their equipment financing. In Baltimore, a company that generates the majority of its revenue during the summer tourism season can arrange a payment schedule with higher installments during peak months and reduced or skipped payments in the winter. This alignment ensures that debt service never outpaces available cash flow. Documentation best practices for equipment financing applications include:

    • Equipment appraisal establishing fair market value
    • Detailed invoice or purchase order from the vendor
    • Two to three years of business financial statements and tax returns
    • Business plan or statement outlining the intended use of the financed equipment

    With these structured applications in mind, we can now examine how businesses and advisors proceed through the full lifecycle of a C&I loan transaction.

    Optimizing Financial Health with Commercial and Industrial Loans

    A core component of debt advisory is helping companies optimize their financial health through commercial and industrial loans, a category of short-to-medium-term financing designed to fund day-to-day operations. C&I loans can be used for various purposes, from purchasing inventory and machinery to covering working capital needs. By strategically deploying these loans, businesses can maintain momentum without sacrificing equity. We work with our clients to structure C&I loans that enhance liquidity, building a stronger foundation for scalable growth.

    C&I loans are often structured as asset-based lending, secured by a company’s receivables or inventory. This approach unlocks capital tied up in current assets, improving cash flow without ownership dilution. For businesses with strong recurring revenue, cash flow financing serves as a complementary tool, allowing them to borrow based on their ability to generate predictable revenue streams. Institutional investors in our network, which comprises over 4,000 entities, can offer flexible terms that may not be available through traditional banks. According to our qualification framework, lenders evaluate collateral quality, EBITDA trends, and comprehensive business plans during the due diligence process.

    Our debt advisory team aligns each client’s C&I loan structure with its specific growth stage and operational cycles. By assessing financial statements, projected cash flows, and expansion plans, we match companies with institutional lenders whose investment criteria align with their sector and deal size. This tailored approach ensures that the resulting capital structure supports working capital efficiency and positions the business for future capital raises. Our team has successfully raised over $800 million in financing solutions, leveraging access to more than $5 billion in deployable debt.

    Proper structuring of C&I loans can strengthen a company’s balance sheet and credit profile, while adherence to financial industry regulation and investor education standards helps ensure transparency in C&I loan agreements. We encourage businesses to discuss their C&I loan structuring needs with our debt advisory team.

    Now let’s address some common questions businesses have about commercial and industrial loans. The regulatory landscape is shaped significantly by federal oversight, with the FTC consumer and business protection division playing a key role. Our team emphasizes that awareness of these protections is a fundamental step in responsible commercial and industrial financing.

    What is the FTC’s role in C&I lending?

    The Federal Trade Commission enforces truth-in-lending requirements and prohibits unfair or deceptive acts against businesses. This oversight creates a baseline of borrower protection for C&I loans, ensuring lenders provide transparent terms and cannot engage in predatory practices.

    How can businesses evaluate lender credibility?

    Business owners should verify lender registrations, review financing terms carefully, and consult the FTC’s business guidance on lending to identify red flags. We advise our clients to avoid any lender unwilling to disclose clear, written documentation.

    What should borrowers know about collateral and guarantees?

    Many commercial and industrial loans require collateral or personal guarantees. The FTC’s truth-in-lending standards mandate that these obligations be clearly disclosed upfront, helping borrowers make informed decisions without hidden risk.

    For more detailed guidance on securing C&I financing, our team can help.

    Partnering with a Capital Advisory Firm for C&I Financing

    Navigating the complexities of commercial and industrial loans demands more than a strong balance sheet—it requires a partner who understands institutional lending at scale. Zaidwood Capital’s debt advisory team evaluates a company’s financial position, cash flow profile, and collateral base to structure tailored C&I financing solutions. By leveraging a network of over 4,000 investors and more than $15 billion in deployable capital, we streamline the transaction process and connect businesses to the right capital partners. Through our Full-Cycle M&A and capital advisory approach, we guide clients from initial due diligence through closing, ensuring every phase moves with precision.

    Securities are offered through Finalis Securities LLC, a registered broker-dealer. Zaidwood Capital LLC is not a registered broker-dealer, and no content herein constitutes an offer or solicitation of securities. Investments involve risk, and past performance does not guarantee future outcomes.

    Resources