
Table of Contents
- Equipment Financing as a Strategic Growth Tool
- Understanding Equipment Financing Structures and Benefits
- Evaluating Equipment Financing Options, Terms, and Structures
- Steps to Qualify for Equipment Financing and Prepare a Strong Application
- Integrating Equipment Financing into Broader M&A and Capital Strategies
- Frequently Asked Questions About Equipment Financing
- Your Path to Equipment Financing Success with Zaidwood Capital
Equipment Financing as a Strategic Growth Tool
Growth-stage enterprises rarely face straightforward capital decisions. Equipment acquisitions sit at the intersection of operational expansion and balance-sheet management, and how a company finances them can either accelerate momentum or create unnecessary constraints. We position equipment financing as a strategic growth lever — one that preserves working capital for initiatives such as talent acquisition, market entry, and product development — rather than treating it as a standalone purchasing transaction. Financing for equipment acquisitions allows management to fund fixed-asset needs without diluting ownership or exhausting lines of credit that may be better deployed elsewhere in the business.
As debt advisors, we evaluate multiple structures based on the asset profile, the company’s cash-flow cadence, and its broader capital stack. Term loans often suit long-lived machinery where predictable amortization aligns with project economics; finance leases can match shorter economic lives or rapidly depreciating technology assets; and sale-leasebacks may unlock embedded equity in already-owned equipment when liquidity is needed for a growth pivot. Equipment leasing structures are never one-size-fits-all, so our analysis focuses on which instrument best aligns the obligation’s duration with the asset’s useful life and the enterprise’s strategic timeline.
Beyond structure selection, our due-diligence approach weighs the equipment’s expected residual value, the industry’s pace of obsolescence, and the effect of the new asset base on overall liquidity and future borrowing capacity. For instance, in sectors where technology cycles compress replacement timelines — such as enterprise AI infrastructure — residual-value assumptions and flexibility provisions carry material weight in the negotiation. According to Zaidwood Capital’s integrated capital-formation framework, equipment financing is most effective when it is embedded in a broader advisory process that sequences the right combination of debt and equity instruments to match each stage of growth.
Because no single asset exists in isolation from the rest of a company’s structure, equipment financing discussions at our firm typically follow a business acquisition, a growth equity raise, or an M&A transaction where the client must fund the fixed-asset component of a growth plan. This full-cycle perspective is what distinguishes a truly consultative engagement from a transactional placement. Whether the need arises during post-acquisition integration or alongside a Series B capital raise, our team brings over 80 years of collective experience to structuring and negotiating arrangements that protect the enterprise’s overall financial flexibility while securing the assets that drive revenue.
Understanding Equipment Financing Structures and Benefits
Within a well-structured capital stack, equipment financing provides a targeted way to fund critical assets. As a Boutique M&A and Capital Advisory Firm based in West Palm Beach, we evaluate equipment financing within your full-cycle capital strategy, helping growth-stage companies acquire the machinery, technology, and infrastructure they need without unnecessarily diluting equity or straining working capital. Equipment loans, equipment leases, and asset-based financing each offer distinct advantages depending on your ownership goals, tax position, and cash flow profile.
The table below compares these three structures across the factors that matter most.
| Feature | Equipment Loan | Equipment Lease | Asset-Based Financing |
|---|---|---|---|
| Ownership | Full ownership at end of term | Lender retains ownership | Use asset as collateral; ownership after repayment |
| Upfront Cost | Down payment (10-20%) | First month’s payment + security deposit | Minimal upfront; asset value determines advance |
| Tax Benefits | Section 179 depreciation, interest deduction | Lease payments may be fully deductible | Depreciation & interest deduction |
| Typical Term | 3-7 years | 2-5 years | Revolving; 1-3 years renewable |
| Best For | Essential, long-term equipment | Technology/rapidly depreciating assets | Companies with strong asset base needing flexible working capital |
As the comparison shows, equipment financing can be tailored to ownership objectives, tax circumstances, and balance-sheet priorities. Equipment loans suit businesses looking to build long-term equity in core assets; the 3- to 7-year amortization aligns repayment with the useful life of heavy machinery or production equipment, while Section 179 depreciation and interest deductions can meaningfully reduce taxable income. In contrast, equipment leases preserve cash by swapping a large down payment for a modest first-month lease charge and security deposit, ideal for technology assets that depreciate quickly or require frequent refresh cycles. Lease payments may be fully deductible, further enhancing the after-tax cost advantage. Asset-based financing, which we structure through our Asset-Based Lending / Working Capital service, allows companies to borrow against the value of existing equipment or other hard assets. This revolving facility offers flexibility for firms that want to preserve liquidity for growth initiatives rather than tying up capital in a fixed-term note.
Strategic structure selection goes beyond short-term cost. We help clients weigh how ownership, tax treatment, and term length interact with their broader capital formation goals — whether they are planning a future sale, scaling operations, or managing seasonal working capital swings. By integrating equipment financing into a Full-Cycle M&A and capital advisory framework, we ensure the structure chosen today does not constrain tomorrow’s strategic options.
With the three structures and their benefits clear, the next question is how to determine which option best fits your company’s cash flow and asset lifecycle. This website is for informational purposes only and is not an offer, solicitation, or recommendation to buy or sell any security. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC. We welcome you to continue exploring how our debt advisory and capital formation process aligns equipment financing with your long-term vision.
Evaluating Equipment Financing Options, Terms, and Structures
After determining the equipment capital your business needs, the next critical step is evaluating the structures, terms, and technology that can optimize your equipment financing strategy. As a Boutique M&A and Capital Advisory Firm, we help founders and executives weigh ownership models, compare lender criteria, and leverage AI-driven capital formation to fund essential assets.
Comparing Equipment Loans and Leases
Equipment loans provide direct ownership — the borrower builds equity in the asset and can claim depreciation and interest deductions, though monthly payments are typically higher and the loan adds both a fixed asset and debt to the balance sheet. Equipment leases, by contrast, keep the lessor as owner while offering lower, often fully deductible operating payments and, in some structures, the option to purchase for $1 or fair market value at term end. Certain lease structures also allow the obligation to remain off-book, preserving borrowing capacity. Choosing between these two equipment financing structures therefore hinges on your tax position, cash-flow tolerance, and balance-sheet strategy.
Key Terms, Interest Rates, and Fees
Understanding the real cost of equipment financing requires looking beyond the headline rate. The total outlay equals principal plus interest (fixed or variable) plus origination fees and any prepayment penalties over the full term. Even a lower APR can prove expensive once fees, balloon payments, and accelerated amortization are factored in. It’s equally important to match the loan term to the asset’s useful life, assess down-payment and residual options, and review covenants, liens, and personal guarantees before signing.
Across lender types, the key differences come down to these five criteria:
| Lender Criterion | Traditional Bank | Online Lender | Asset-Based Lender |
|---|---|---|---|
| Loan Size | $50,000 – $5,000,000 | $25,000 – $2,000,000 | Custom; asset-value driven |
| Interest Rate (APR) | 6% – 12% | 12% – 36% | 8% – 20% |
| Approval Speed | 7 – 30 days | 24 – 48 hours | 5 – 15 days |
| Credit Score Min. | 680+ | 600+ | 550+ |
| Collateral Required | Equipment + blanket lien possible | Equipment only | Equipment + other assets |
A business with strong credit will find the traditional bank’s 6%–12% APR attractive, but the 7–30 day approval window may delay time-sensitive equipment purchases. Online lenders offer speed and a 600+ credit floor, yet their 12%–36% APR pushes total cost higher, while asset-based lenders weigh collateral value more heavily than credit scores. These illustrative market benchmarks, drawn from our deal experience, help you identify the most suitable capital partner for your equipment financing needs.
Leveraging AI and Technology for Equipment Capital Raising
Once the optimal structure and terms are clear, technology can dramatically accelerate capital formation. Our proprietary investor matchmaking engine, Precision Catalyst, uses AI-driven analytics to align your equipment funding request with the most relevant institutions from our network of 4,000+ investors—spanning strategic investors, venture capital, private equity, family offices, and sovereign wealth funds—and our access to over $15 billion in committed capital. The same platform underpins our enterprise AI capital raising approach, connecting growth-stage companies to institutional counterparties with the speed and precision that a traditional advisory process often lacks. Combined with the Velocity Matrix rapid-execution framework, these tools compress the timeline from mandate to close while preserving the custom guidance of a full-cycle capital advisory engagement.
This website is for informational purposes only and does not constitute an offer, solicitation, or recommendation to buy or sell any security. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is unaffiliated with Finalis. Investments involve risk, and past performance does not guarantee future results. Prospective investors should conduct their own due diligence and consult legal, tax, and financial advisors and, where appropriate, a registered representative.
With a clear picture of structures, terms, and technology, the path to equipment capital becomes a matter of execution.
Steps to Qualify for Equipment Financing and Prepare a Strong Application
If you’re ready to secure equipment financing for your business, the most critical step is preparing a comprehensive application that showcases your financial health and growth potential. A well-organized submission not only accelerates underwriting but also strengthens your position in negotiations. We’ll guide you through three essential preparation stages: gathering key financial documents, understanding lender evaluation criteria, and crafting a persuasive business case that aligns with your strategic objectives.
Gathering Your Financial Documentation
Start by assembling the following core materials:
- Two to three years of business and personal tax returns
- Year-to-date profit and loss statement and balance sheet
- Cash flow statements for the most recent 12 months
- A business plan outlining operations, market, and growth strategy
- An itemized equipment quote or vendor invoice specifying the assets to be financed
Documentation requirements differ by financing structure. The table below highlights key documents for equipment loans, leases, and asset-based financing.
| Loan Type | Equipment Loan | Equipment Lease | Asset-Based Financing |
|---|---|---|---|
| Core Documents | Tax returns (2-3 yrs), P&L, balance sheet, business plan, equipment quote | Tax returns, P&L, balance sheet, equipment quote, personal financial statement | Asset schedule, AR aging, inventory listing, debt schedule, business plan |
| Credit Focus | Personal & business credit score, time-in-business, cash flow | Business credit profile, less stringent on time-in-business | Asset quality & liquidation value more than credit score |
| Additional Requirements | Equipment appraisal, insurance certificate, UCC filing | Insurance, vendor invoice, UCC filing | Field exam, collateral monitoring agreement, borrowing base certificate |
With your documentation in order, the next step is to understand how lenders evaluate your financial profile.
Understanding Credit Requirements and Underwriting Criteria
Credit Score. Lenders typically seek a personal credit score in the mid-600s or higher, though business credit history and overall financial strength can offset lower scores. Review both personal and business credit reports before applying to correct any errors.
Time in Business. Most equipment lenders prefer at least two years of operating history. Startups may still qualify through asset-based financing or leases when supported by strong personal credit and a viable business plan.
Cash Flow & Debt Service Coverage. A key metric is the debt service coverage ratio (DSCR), which compares cash flow available to debt obligations. A DSCR of 1.25x or more is commonly expected, demonstrating your ability to service new debt comfortably. Consistent, positive cash flow signals repayment reliability.
Collateral & Advance Rates. In asset-based financing, lenders appraise equipment and receivables to determine advance rates—typically 50% to 80% for equipment and up to 85% for accounts receivable. Understanding these rates helps us structure a finance package that maximizes your borrowing capacity while protecting asset values.
We evaluate these factors in conjunction with your overall financial profile, ensuring your application presents the strongest case possible.
Crafting a Compelling Business Case for Equipment Financing
Once your documents are in order and you understand underwriting criteria, the final step is to present a strategic business case. We guide clients to frame three core elements:
- Market Demand: Demonstrate industry trends, customer need, and competitive positioning that justify the equipment investment.
- Projected ROI: Quantify the expected revenue increase or cost savings tied to the equipment’s use. For example, upgrading machinery might reduce labor costs by 20% and boost output by 30%, strengthening your cash flow for repayment.
- Management Credibility: Highlight your team’s industry experience, past operational successes, and track record of meeting financial commitments. Lenders often weigh management quality as heavily as financials.
We help you translate these elements into a data-backed narrative that aligns with lender expectations. By presenting a clear, quantified story, you reduce lender risk perception and improve your negotiating stance. This holistic preparation not only strengthens your equipment financing application but also positions your business for future capital-raising efforts. Our team stands ready to refine every detail of your presentation until it meets institutional standards. As a Boutique M&A and Capital Advisory Firm, Zaidwood Capital provides hands-on support and institutional insight to navigate the entire financing lifecycle—from document preparation through deal closing.
Integrating Equipment Financing into Broader M&A and Capital Strategies
Equipment financing is a capital-stack decision, not a back-office purchase. The structure chosen for acquiring machinery directly affects ownership, leverage, and strategic flexibility. For companies scaling across West Palm Beach and beyond, we position equipment financing alongside equity raises, asset-based lending, and acquisition debt — ensuring each layer reinforces the broader capital formation plan. Unlike equity raises that dilute existing shareholders, equipment loans and leases preserve ownership, making them a vital tool for founders protecting their stake.
The table below compares four capital solutions across the decisions that matter most.
| Capital Solution | Equipment Financing (Loan/Lease) | Equity Raising | Asset-Based Lending | Acquisition Financing |
|---|---|---|---|---|
| Primary Use | Funding new or replacement equipment | Selling equity for growth capital | Using company assets as collateral for revolving credit | Borrowing against future M&A targets’ assets or cash flow |
| Impact on Ownership | No dilution | Dilution | No dilution | Varies (debt vs. equity) |
| Best For | Isolated asset purchases; predictable depreciation | High-growth, asset-light companies needing scale | Cyclical/seasonal businesses with strong B/S | Firms executing buy-outs, mergers, or bolt-on acquisitions |
| Zaidwood Capital Support | Structuring, lender introductions, side-by-side comparison | Investor introductions, Precision Catalyst AI matching, full-cycle advisory | Collateral analysis, borrowing-base modeling, lender outreach | Buy-side/sell-side M&A advisory, due diligence, capital formation |
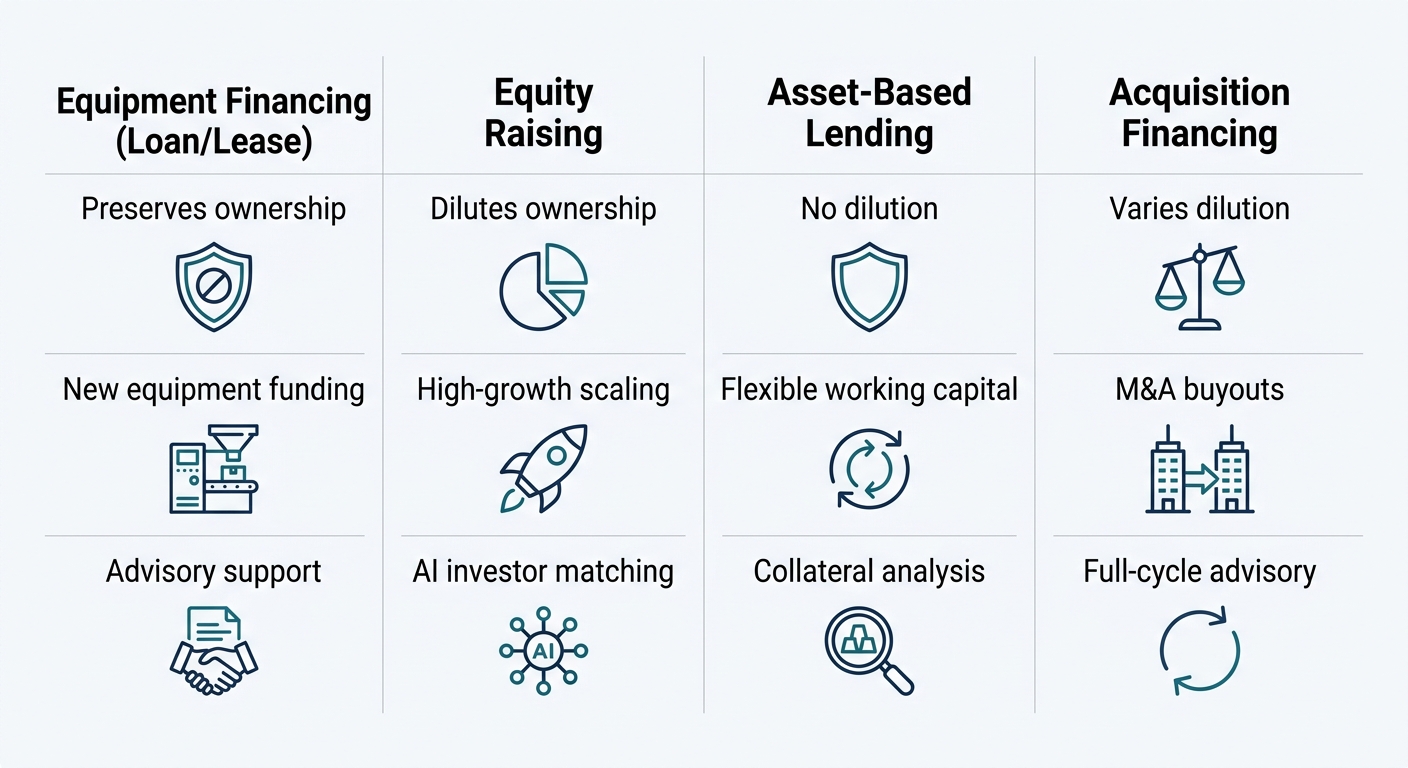
The table highlights a critical advantage: equipment financing and asset-based lending preserve equity, while equity raises dilute existing shareholders. Companies with predictable depreciation schedules often find equipment financing the optimal choice, whereas high-growth, asset-light ventures may lean on equity. Our role spans each solution — from structuring equipment loans and leases and vetting lenders to deploying Precision Catalyst for AI-driven investor matchmaking in equity rounds. For cyclical businesses with strong balance sheets, we model borrowing bases and facilitate asset-based credit lines, while our M&A advisory supports buy-outs through capital formation and due diligence. By layering equipment financing with seller notes, growth equity, or ABL facilities, we help clients minimize dilution and close transactions with greater strategic flexibility.
The capital stack infographic below highlights how these four solutions complement one another across different business stages.
This integrated approach reflects our full-cycle M&A and capital advisory mandate. Whether you’re funding a single piece of equipment or executing a complex acquisition, we structure, source, and sequence capital solutions to align ownership goals with transaction outcomes. Our advisory team — supported by a network of over 4,000 institutional investors — ensures each layer preserves equity where it matters most, so you can close with confidence.
Frequently Asked Questions About Equipment Financing
The FAQs below address common questions about equipment financing in the context of our asset-based lending and working capital solutions.
What is equipment financing? Equipment financing is an asset-based lending structure where the equipment secures funding to purchase or refinance business machinery, vehicles, or technology.
How does it differ from an equipment lease? Financing provides ownership and depreciation benefits, while a lease is a usage agreement without title transfer.
How does it support working capital and acquisitions? Equipment financing preserves working capital for operations and acquisitions, avoiding large cash outlays that could strain liquidity.
What factors do you evaluate? We review cash flow stability, time in business, credit standing, and the equipment’s useful life to tailor a facility that fits your broader capital strategy.
How does Zaidwood Capital help? We integrate equipment financing into our full-cycle M&A advisory process, leveraging a network of over 4,000 institutional investors to ensure alignment with your capital structure.
Contact our team to explore equipment financing options for your business.
Your Path to Equipment Financing Success with Zaidwood Capital
From first conversation to funded equipment, Zaidwood Capital guides you through a straightforward equipment financing journey. We begin with a consultation to assess your equipment acquisition financing needs and cash-flow profile. Next, we structure an asset-based solution that ties together your equipment and working capital, then use our Precision Catalyst platform to match you with the right lenders from our network of 4,000+ investors. Finally, we execute and close through our Velocity Matrix rapid-execution framework. Zaidwood Capital is not a registered broker-dealer; securities, where applicable, are offered through Finalis Securities LLC. We support the full cycle from strategy to funding; let’s start.