
Zaidwood Capital

Tag: Continuation Funds

  • Private Equity Continuation Funds: 2026 Guide for Investors

    Private Equity Continuation Funds: 2026 Guide for Investors

    Table of Contents

    The Rise of Private Equity Continuation Funds

    Private equity continuation funds have become a mainstream liquidity solution, allowing general partners to transfer assets into a new fund they manage and extend the hold period. These gp-led secondary transactions have risen in response to prolonged exits, valuation gaps, and challenging IPO or sale routes.

    Single-asset continuation vehicles concentrate this approach on one high-performing company that needs additional time and capital to reach its full value. The rise of private equity continuation funds has transformed the secondary market from a distressed niche into a deliberate institutional portfolio management tool.

    Sponsors evaluating these structures can access experienced capital advisory services to support evaluation and execution. As a Boutique M&A and Capital Advisory Firm, we provide guidance without promising any specific outcome, drawing on the approach detailed in our Capital Advisory FAQ. We help clients navigate continuation fund complexities and align strategies with long-term value creation.

    Setting the Stage for Continuation Fund Analysis

    In today’s liquidity-constrained market, private equity continuation funds have become an increasingly vital solution within gp-led secondary transactions. By creating a new vehicle to hold an existing portfolio asset, a GP can offer limited partners liquidity without a full exit, while maintaining exposure to the asset’s upside potential. Single-asset continuation vehicles, in particular, have gained traction as a means to extend hold periods and inject growth capital in a market where traditional exit paths may be delayed.

    However, the structural complexity of these continuation funds demands rigorous evaluation. Key considerations—due diligence, alignment of interests between GPs and LPs, and pricing valuation—must be assessed through a specialized advisory lens. A mere financial review is insufficient; without a Full-Cycle M&A perspective, stakeholders risk misaligned incentives or mispriced assets.

    As a Boutique M&A and Capital Advisory Firm, Zaidwood Capital approaches continuation fund analysis with a disciplined, Full-Cycle M&A framework. Our process integrates market intelligence with deep transactional expertise, ensuring that every transaction is scrutinized for strategic fit, risk factors, and value creation. In the following sections, we break down the critical analytical pillars that define prudent decision-making in this space.

    Understanding Continuation Fund Mechanics

    Private equity continuation funds are a strategic mechanism that helps fund managers extend ownership of portfolio companies beyond a traditional fund’s term. Through our educational resources, we explain how a continuation fund—a newly created vehicle—purchases one or more assets from an existing fund, giving investors a liquidity option without a full exit.

    In a gp-led secondary transaction, the general partner orchestrates the sale of selected assets from a legacy fund to the continuation vehicle. Existing limited partners are offered a clear choice: cash out their interest at fair market value or roll their pro-rata stake into the new fund, preserving exposure to the asset’s future potential. The vehicle is typically capitalized by both rolling LPs and fresh capital from new institutional investors.

    A common structure is the single-asset continuation vehicle, which holds only one portfolio company. This design is often used for a manager’s highest-conviction assets that need additional time or growth capital to reach full value. Continuation fund structures have grown in popularity as a flexible alternative to a mandatory sale or IPO, delivering a measured liquidity event while maintaining alignment with the asset’s long-term story.

    GP-Led Secondary Transaction Structures

    Private equity continuation funds represent one of the most prominent categories of GP-led secondary transactions in the market today. These structures allow general partners to retain high-quality portfolio assets beyond the original fund term while providing partial liquidity to existing limited partners.

    A single-asset continuation vehicle focuses on one high-performing portfolio company. The GP transfers that company into a newly created vehicle, and existing LPs choose between selling their interest for cash or rolling their exposure into the new structure at a valuation-based price. Single-asset continuation vehicles concentrate capital behind a proven asset where the GP sees continued upside.

    Multi-asset continuation funds, sometimes called portfolio continuation vehicles, group several fund investments together. This approach extends the hold period for a collection of quality assets while raising fresh capital from new and returning investors. As described in our CADE FAQ, these GP-led secondary transactions typically include an independent valuation process and special LP negotiation to address the natural conflict of interest created when a sponsor sits on both sides of the trade. Executing these structures effectively is where dedicated secondary advisory expertise comes into play.

    Single-Asset Continuation Vehicles Explained

    Within private equity continuation funds, single-asset continuation vehicles (SACVs) represent a specialized structure. As outlined in our CADE FAQ, an SACV enables a general partner (GP) to move a single, high-performing portfolio company from an existing fund into a new vehicle.

    In gp-led secondary transactions, establishing an SACV serves a dual purpose. It provides existing limited partners (LPs) with the option to obtain liquidity while allowing the GP to retain management of an asset poised for further growth. We structure these transactions to align interests for the next phase of value creation.

    Unlike multi-asset continuation funds that pool several portfolio companies, an SACV focuses exclusively on one asset. This concentrated approach simplifies governance and permits the design of tailored capital structures. By isolating a single investment within an SACV, GPs can more precisely target operational improvements and exit timing for that specific company.

    Benefits Driving the Popularity of Continuation Vehicles

    Private equity continuation funds have gained popularity because they unlock capital efficiency, extend asset ownership, and offer liquidity on tailored terms. Through gp-led secondary transactions, sponsors create vehicles that hold high-quality companies beyond a typical fund life, giving existing LPs a choice to exit or roll over.

    From our perspective, a key driver is capital efficiency: private equity continuation funds allow a sponsor to raise new capital without the full roadshow of a traditional fund, preserving deal momentum. At the same time, these vehicles let managers support high-performing portfolio companies through additional growth cycles, avoiding a sale forced by a fund’s sunset date.

    For limited partners, these structures provide a liquidity option: exit at a transparent price or roll into a vehicle that continues to back a proven asset. Single-asset continuation vehicles concentrate that strategy on one high-conviction company, attracting institutional investors who prefer exposure to an established operation rather than a blind pool.

    However, these benefits come with structural considerations explored next.

    Risks and Key Considerations for Continuation Funds

    Although continuation funds can provide liquidity and continuity, they introduce several important risks and considerations in private equity continuation funds. In gp-led secondary transactions, the GP sits on both sides of the deal, representing existing and new investors, which creates inherent conflicts of interest that LPs must weigh carefully before electing their options.

    Valuation risk is a central concern in single-asset continuation vehicles. The underlying assets are often illiquid and difficult to value, and the valuation may rely on manager estimates or third-party opinions, which can materially affect LP economics and exit outcomes.

    LPs also face liquidity trade-offs, often with limited time to decide whether to roll over, sell, or receive a distribution, and the terms may differ meaningfully between those elections. Alignment of interests and fund governance require close scrutiny, including the role of the LP Advisory Committee, fee structures, co-investment opportunities, and ongoing information rights.

    These structures are complex and demand thorough LP due diligence, including evaluation of the manager’s track record, the underlying asset quality, and the final vehicle terms. Private equity investments involve risk, including the possible loss of principal, and no outcome is guaranteed. This content is for informational purposes only and does not constitute an offer, solicitation, or recommendation to buy or sell any security. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC.

    Understanding these risks is the first step; in the next section, we outline how our team advises on continuation-fund strategies.

    How Continuation Funds Deliver Liquidity to Limited Partners

    Private equity continuation funds are a growing source of liquidity for limited partners. As explained in Zaidwood Capital’s capital advisory FAQ, these structures allow a general partner to move a high-potential asset from an existing fund into a new vehicle, creating a liquidity event for LPs who choose to sell. The GP creates a new investment vehicle, often called a continuation fund, to hold the asset, offering existing limited partners either liquidity or the opportunity to maintain their exposure.

    Through gp-led secondary transactions, LPs are typically offered a choice: sell their interest into the new entity and receive cash, or roll over their stake to maintain exposure. A third-party valuer or secondary market process sets the pricing, ensuring an arm’s-length transaction. This mechanism differs from a traditional IPO or trade sale, offering an alternative when an asset may not be ready for a full exit but has a strong growth runway.

    Single-asset continuation vehicles focus on a single portfolio company, giving LPs concentrated exposure while the GP retains control to drive further value creation. This can be a strategic alternative to a forced sale, extending the hold period while providing potential liquidity.
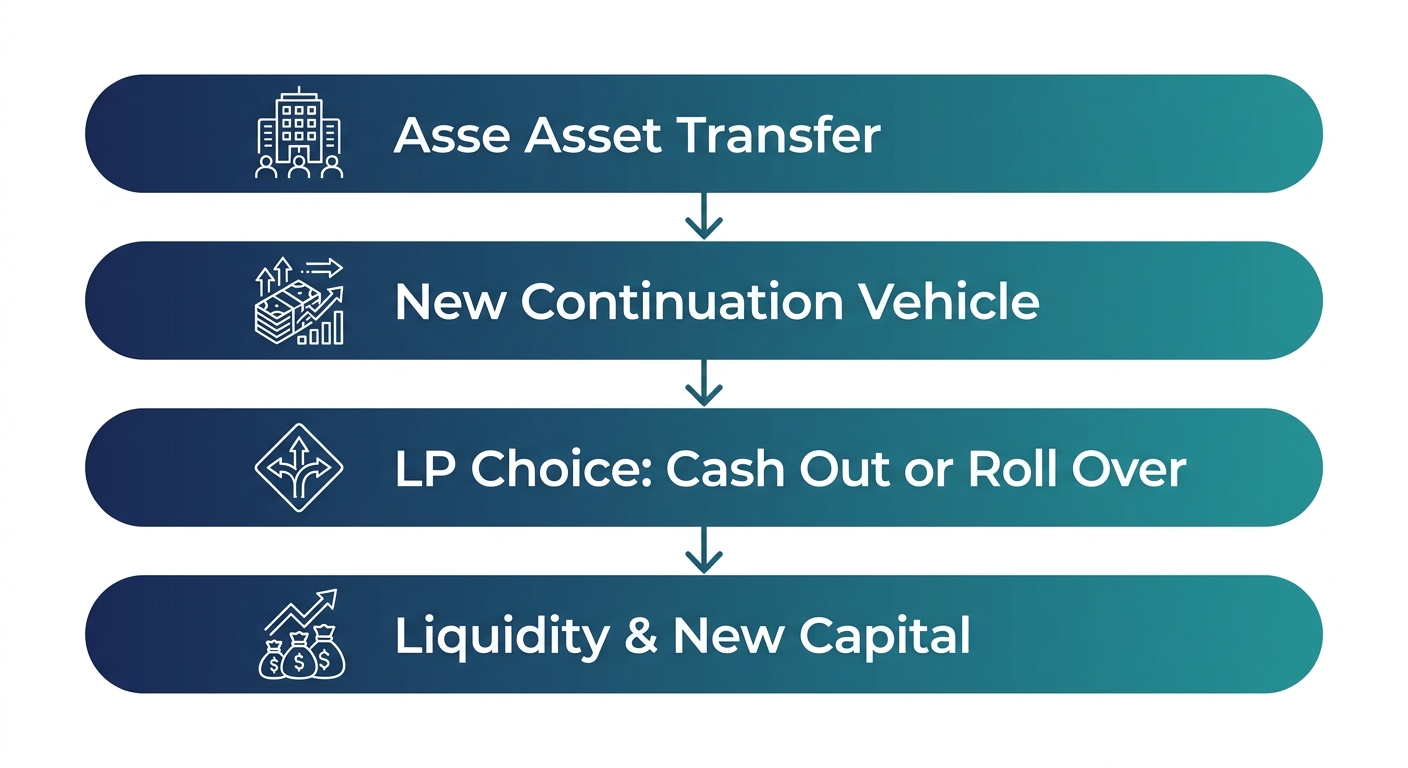
    Vertical process flow diagram with four connected steps showing how continuation funds deliver liquidity to limited partners, from asset transfer to new capital.
    How continuation funds deliver liquidity to limited partners in four steps.

    A Decision Framework for Evaluating Continuation Opportunities

    As the secondary market expands, private equity continuation funds gain traction, and a disciplined evaluation framework is essential to distinguish strong opportunities from structural risks. Our CADE methodology anchors this process with five core criteria:

    Sponsor alignment — is the GP rolling meaningful capital alongside LPs? Asset quality — does the underlying business have a credible multi-year growth thesis? Valuation discipline — is there independent support and evidence of an unforced sale? Structural terms — are rollover rights, liquidity provisions, and governance protections adequate? Realistic liquidity alternatives — how does the continuation offer compare with a traditional sale process?

    When evaluating a single-asset continuation vehicle, concentrated exposure demands stricter valuation governance and GP scrutiny than a diversified multi-asset continuation structure. For GP-led secondary transactions, our CADE framework uses the same five dimensions to test the strength of the opportunity.

    Applying this framework consistently marks the starting point, and our CADE FAQ provides the full checklist we use. No framework eliminates risk — investors should work with professional advisors.

    Troubleshooting Common Continuation Fund Challenges

    Sponsors navigating in private equity continuation funds often discover that the transaction introduces practical challenges requiring proactive management. Drawing on our work with middle-market managers, we see several recurring pain points that, with the right approach, can be systematically resolved.

    • The most persistent challenge in private equity continuation funds is the protracted LP consent timeline that catches GPs off guard. Early, structured outreach and a dedicated data room at least 60 days ahead of the process align LP expectations and accelerate the consent process.
    • In gp-led secondary transactions, valuation disagreements frequently erode LP confidence. Independent appraisals and fairness opinions provide objective benchmarks that satisfy fiduciary duties and reduce transactional friction, without implying the firm provides those services.
    • Governance risks — such as perceived self-dealing — can derail a continuation fund. Best practice includes early LPAC consultation, robust limitation-of-liability provisions, and rigorous re-underwriting of the underlying assets to strengthen alignment, not guarantee outcomes.
    • In single-asset continuation vehicles, sponsors face distinct complexities such as assuming existing debt, negotiating minority LP rollover and participation rights, and preparing for granular asset-level diligence. Addressing these early prevents cascading surprises at closing.

    For deal-tested, question-by-question answers spanning the full continuation process, consult our CADE FAQ. As a Boutique M&A and Capital Advisory Firm, we stand ready to support you with practical, transaction-informed guidance at every stage.

    This content is for informational purposes only and does not constitute an offer or solicitation; securities are offered through Finalis Securities LLC, and Zaidwood Capital is not a registered broker-dealer and is unaffiliated with Finalis.

    Confident navigation of the continuation fund landscape is a product of education, preparation, and clear-eyed evaluation—not a promise of certain returns. For private equity continuation funds, that means understanding the strategic rationale for these structures and the importance of disciplined due diligence. This approach enables both GPs and LPs to approach transactions with informed judgment rather than speculation.

    Confidence in GP-led secondary transactions, for example, comes from scrutinizing valuation methodologies, verifying alignment of interests between GPs and LPs, and demanding transparency throughout the process. Single-asset continuation vehicles, while a distinct structural variant within the broader GP-led secondary market, require the same rigorous attention to valuation, governance, and LP protections. Across the private equity continuation fund landscape, rigorous assessment of these factors builds a foundation for confident decision-making.

    As a Boutique M&A and Capital Advisory Firm, Zaidwood Capital provides Full-Cycle M&A guidance to clients evaluating continuation fund structures—without acting as a registered broker-dealer or offering broker-dealer services directly. For deeper educational answers, we invite you to explore our CADE FAQ, where we address common questions about continuation asset deal execution. Above all, we encourage you to conduct your own due diligence and consult legal, tax, and financial advisors before acting on any information presented here.
  • Private Equity Continuation Funds: Complete Guide for Investors

    Private Equity Continuation Funds: Complete Guide for Investors

    Table of Contents

    Private equity continuation funds explained

    Private equity continuation funds are GP-led secondary transactions where a new fund vehicle is established to hold existing portfolio assets beyond the original fund’s term. These structures can be arranged as single-asset continuation vehicles or as multi-asset pools. The objective is twofold: they provide limited partners with an early liquidity mechanism while enabling the general partner to continue managing and growing the assets.

    In a typical transaction, the GP sponsors the new vehicle and offers existing LPs a choice — a cash exit at a reset valuation or the opportunity to roll their interests into the successor fund. This approach aligns incentives and can supply follow-on capital for further value creation.

    For fund managers, executing a continuation fund requires specialized capital-raising and placement capabilities. Learn more about our capital formation services. This is not investment advice — consult your professional advisors.

    How Private Equity Continuation Funds Work

    Private equity continuation funds, also known as GP-led secondary transactions, are sophisticated financial vehicles that allow general partners to extend their holding period for high-potential portfolio companies or assets. At Zaidwood Capital, we have observed a significant increase in GP-led secondary transactions as fund managers seek innovative ways to maximize returns for their investors. These structures provide liquidity options for existing limited partners while enabling continued value creation in promising investments.

    The core mechanism involves a GP initiating a GP-led secondary transaction by transferring assets from an existing fund into a newly formed continuation vehicle. This process typically includes both existing LPs and new institutional investors, with the GP retaining a significant stake to demonstrate confidence in the assets’ future performance and align interests across all parties involved.

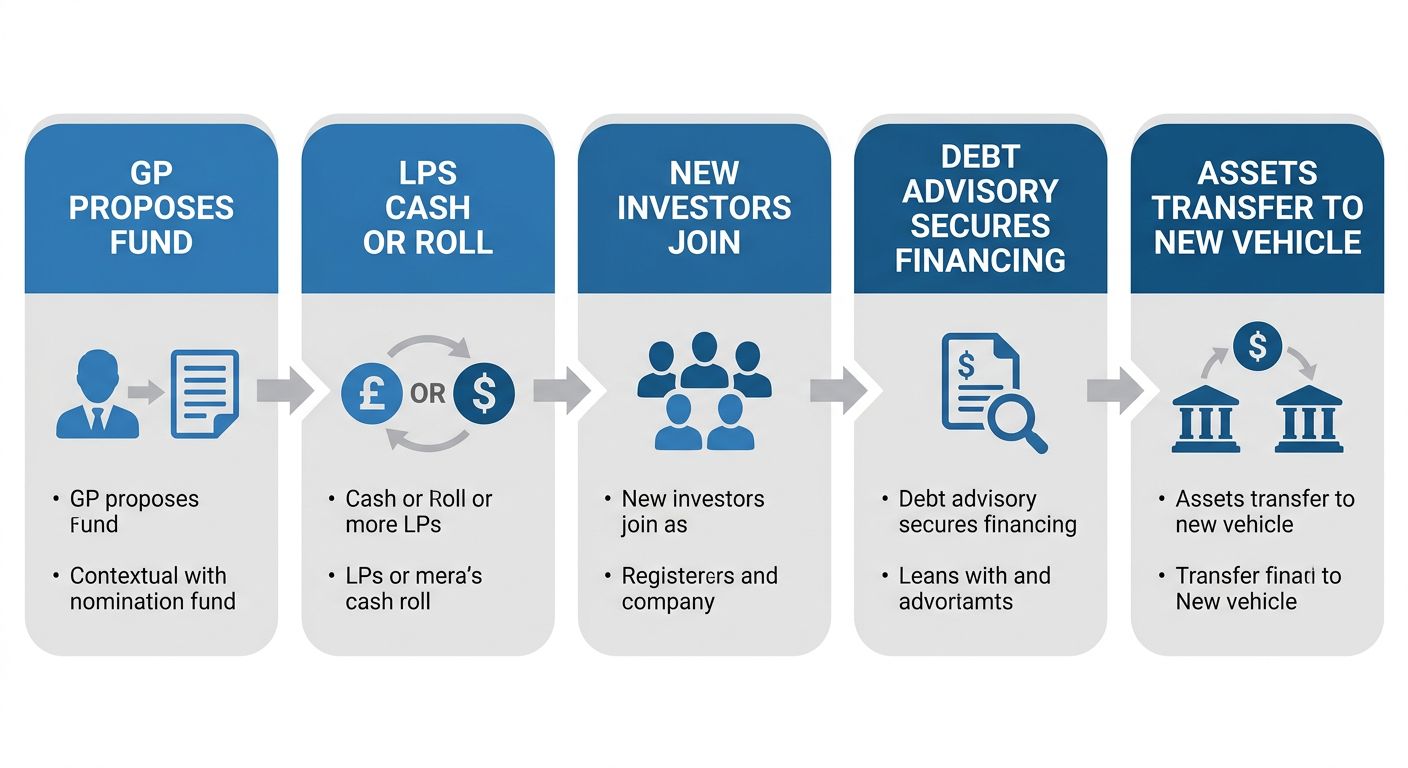
    Flowchart of a GP-led continuation fund transaction with five connected stages in a professional blue and gray palette

    GP-led continuation fund transaction process flow

    The transaction flow illustrated above demonstrates how these complex structures come together. The process begins with asset identification and valuation, followed by the formation of the new vehicle, capital raising from both new and existing investors, and ultimately the transfer of assets to the continuation fund.

    Financing plays a critical role in structuring these transactions, and debt advisory services from Zaidwood Capital can provide the necessary financing structures for these funds. According to Zaidwood Capital’s internal knowledge resources, our Full-Cycle M&A and capital advisory practice encompasses mezzanine debt, venture debt, and asset-based lending structures that support GP-led secondary transactions. With access to over 4,000 institutional investors and $15 billion in deployable capital, we help structure the optimal financing package for each unique situation.

    The valuation process requires rigorous fairness opinions and third-party advisory to ensure alignment with LP interests. Independent valuation firms assess the transferred assets to establish a fair market price, protecting all stakeholders involved in the transaction.

    Continuation funds can be structured as single-asset continuation vehicles or multi-asset vehicles, depending on the GP’s strategic objectives. A single-asset continuation vehicle focuses on one high-conviction portfolio company, while multi-asset structures consolidate several related holdings. These structures have become increasingly prevalent in today’s private equity landscape, offering flexible solutions for portfolio optimization and extended value creation timelines.

    GP-Led Secondary Transactions and Single-Asset Vehicles

    GP-led secondary transactions have become a defining feature of today’s private equity landscape, driven by the growing use of private equity continuation funds. In a GP-led deal, a general partner facilitates the sale of existing limited partner interests to new investors, often by transferring a portfolio company into a newly created continuation fund. This structure gives both continuing and exiting LPs greater flexibility than a traditional fund liquidation.

    A prominent subset of these transactions is the single-asset vehicle. Here, a single portfolio company is moved into a standalone fund, allowing the GP to hold a high-performing asset beyond the original fund’s life. This approach unlocks the runway needed for additional value creation while providing immediate liquidity to LPs who wish to exit. In our experience, these vehicles also enable more tailored governance terms and focused board oversight, which can accelerate strategic initiatives and operational improvements, provide clearer reporting metrics for investors concentrated on concentration risk and exit timing, and support alignment of incentives among continuing stakeholders while preserving LP choice and protections. We have seen demand for single-asset continuation vehicles increase significantly as GPs seek longer holding periods for prized assets.

    Why do GPs favor these structures? First, they can retain top-performing companies rather than selling them prematurely. Second, they raise follow-on growth capital to fund expansion or acquisitions. Third, they offer existing LPs a clear choice: cash out at fair value or roll their interest into the new vehicle. These transactions typically require independent valuations and approval from the LP advisory committee, ensuring alignment with capital market standards for secondary processes.

    At Zaidwood Capital, we advise clients on navigating these transactions from initial structuring through close. Our work in the private equity secondary market confirms that well-designed continuation funds balance the interests of all parties while capturing additional upside. The next section explores the valuation techniques that underpin fairness opinions in these evolving deal structures.

    Several interrelated factors explain this surge in popularity. We see that private equity continuation funds have become a cornerstone of liquidity solutions in 2026, driven by regulatory clarity, market demand for flexible exits, and the structural innovation of GP-led transactions.

    The U.S. Securities and Exchange Commission (SEC) has been a primary catalyst for this growth. SEC investor protection has been a key priority, with the SEC strengthening its initiatives to oversee GP-led secondary transactions. Through proposed rule changes and enforcement priorities, the regulator has clarified the framework for exempt offerings and secondary market activity, making it easier for fund managers to structure continuation vehicles that safeguard investor interests while providing much-needed transactional certainty.

    Market demand for liquidity solutions has further accelerated the trend. Institutional investors are increasingly turning to these structures to realize partial or full exits without triggering forced asset sales that could dilute returns. Private equity continuation funds give LPs the flexibility to recycle capital while GPs retain high-performing assets for further value creation. With fund lifespans extending beyond traditional horizons, the ability to execute gp-led secondary transactions has become essential for aligning the longer-term interests of managers and their limited partners.

    Structurally, the rise of single-asset continuation vehicles has been a defining feature of this cycle. These vehicles bundle a single portfolio company into a new fund, allowing the GP to extend the investment period and pursue additional growth while offering existing LPs the choice to liquidate or roll their interests. This targeted approach has gained traction as a flexible way to manage concentrated positions, reduce portfolio complexity, and align incentives without the legal and operational burden of full-fund restructurings. These examples show private equity continuation funds balance liquidity needs with longer-term investment horizons overall.

    Having examined the drivers, we now turn to the mechanics of these transactions and how they are structured to meet the needs of sponsors and investors alike.

    Benefits and Risks for LPs and GPs

    For GPs considering a continuation fund, the strategic advantages are compelling. Private equity continuation funds allow general partners to access liquidity from older fund portfolios without forcing a premature sale of assets that still have meaningful upside potential. We see this as a powerful tool that aligns interests by giving GPs the ability to extend their management of high-performing assets—particularly through the use of single-asset continuation vehicles—while simultaneously offering limited partners a clear choice between realizing gains and maintaining exposure. From an LP perspective, this structure provides valuable optionality. Rather than facing a binary outcome when a fund nears the end of its life, investors receive a liquidity event for their legacy fund interests coupled with the ability to roll over their commitment if they believe in the continued growth trajectory of the underlying portfolio.

    However, these transactions are not without complexity. One of the most persistent challenges lies in determining a fair market price for inherently illiquid assets, which requires rigorous third-party valuation work and independent fairness opinions. The inherent GP–LP conflict of interest sits at the center of every GP-led secondary transaction—the GP serves as both sponsor of the existing fund and, effectively, the buyer in the new continuation vehicle. To manage this, we advise clients to insist on transparent disclosure, independent governance structures, and the active involvement of legal and financial advisors who represent LP interests throughout the process.

    All GP-led secondary transactions are subject to FINRA regulatory compliance standards, including requirements for fairness opinions and transparent disclosure. When a broker-dealer such as Finalis Securities LLC is engaged, adherence to FINRA rules is mandatory. The Financial Industry Regulatory Authority (FINRA) establishes the regulatory framework that governs how securities firms involved in these transactions must operate, providing a baseline of investor protection through its oversight of disclosure practices, fair-dealing obligations, and conflict-of-interest management. This regulatory overlay reinforces the governance discipline that sophisticated LPs should demand.

    We emphasize that continuation funds are not risk-free. LPs should carefully evaluate the GP’s track record with similar structures, the specific governance protections built into the transaction, and whether the continuation vehicle genuinely aligns with their portfolio objectives. When structured thoughtfully and governed transparently, continuation funds can serve as a valuable liquidity and portfolio management solution—but the burden of due diligence rests squarely on all parties involved.

    This content is for informational purposes only and does not constitute investment advice or an offer, solicitation, or recommendation to transact. Investments involve risk and may be illiquid; investors may lose all or part of their investment. Zaidwood Capital LLC is not a registered broker-dealer. Securities are offered through Finalis Securities LLC, a separate entity.

    Best Practices for Evaluating Continuation Fund Opportunities

    Private equity continuation funds represent a growing segment of GP-led secondary transactions where a general partner transfers one or more portfolio assets from an existing fund into a new vehicle under the same management. While these structures can offer extended value-creation runway and fresh capital, they demand rigorous investor scrutiny to ensure the transaction serves limited partner interests fairly. We believe a methodical evaluation framework is essential for any LP assessing such opportunities.

    At the core of every analysis are several critical factors. First, we examine GP incentive alignment—specifically whether the manager is committing meaningful co-investment capital to the continuation vehicle and how the fee structure impacts net returns. Second, the fairness of the valuation process requires close attention, including whether an independent third-party opinion has been obtained and how the pricing compares to recent market benchmarks. Third, the composition and independence of the oversight committee or advisory board play a vital role in mitigating conflicts of interest, as does the transparency of disclosure around any existing GP–LP dynamics that may influence the proposed transaction.

    A thorough review must also consider the fund’s historical track record and the strategic rationale for retaining the asset rather than pursuing an outright sale. Investors should scrutinize the fee structure carefully, including management fees, any transaction-related costs, and the impact on carried interest calculations. Zaidwood Capital notes that evaluating the underlying financing terms is equally important, and our debt advisory team often helps clients analyze leverage arrangements embedded in continuation fund structures to ensure they align with long-term value-creation objectives. We also evaluate exit timing, market receptivity, and operational improvement plans to ensure the continuation path is realistic and achievable over time.

    These due diligence pillars—alignment, valuation integrity, independent oversight, and fee transparency—form the foundation of informed LP decision-making in GP-led secondary transactions. With these best practices in mind, our team can assist in structuring and vetting such opportunities.

    Key Takeaways and Next Steps in Continuation Fund Strategy

    Our earlier sections laid out how private equity continuation funds serve as flexible structures that extend fund life and deliver intermediate liquidity. These vehicles allow general partners to hold prized assets longer while giving limited partners options to roll over or exit.

    GP-led secondary transactions and single-asset continuation vehicles form the core of this strategy, aligning sponsor and investor interests through transparent pricing and governance. At Zaidwood Capital, we advise on structuring these transactions, from selecting the appropriate vehicle to managing the reinvestment process.

    As you evaluate your next move, you may consider:

    • Reviewing your current fund documents and limited partnership agreements for rollover provisions.
    • Weighing single-asset continuation funds against multi-asset GP-led solutions based on your portfolio concentration and return objectives.
    • Engaging a capital advisor experienced in secondary transactions and structured liquidity events.

    Our Continuation Fund FAQ details common questions, and we invite you to book a discovery call for tailored guidance on your specific situation.

    Resources