
Zaidwood Capital

Tag: supply chain financing

  • What Is Supply Chain Financing? Complete 2026 Guide

    What Is Supply Chain Financing? Complete 2026 Guide

    Table of Contents

    The Essentials of Supply Chain Financing for Business Leaders

    Supply chain financing (SCF) encompasses solutions such as reverse factoring and dynamic discounting that allow buyers to extend payment terms while suppliers receive early payment from a financial institution. This working capital optimization tool has become essential for business leaders seeking to strengthen liquidity and supplier relationships.

    Effective SCF arrangements involve three key stakeholders: the buyer, the supplier, and the financing provider. As a Boutique M&A and Capital Advisory Firm, we understand that buyers can improve Days Payable Outstanding (DPO) and suppliers can reduce Days Sales Outstanding (DSO) while lowering supply chain disruption risk. Unlike traditional factoring or invoice discounting, which are supplier-centric, SCF is a buyer-led approach that does not add debt to the buyer’s balance sheet and often enhances overall liquidity. By accelerating cash conversion cycles, SCF can free up internal funds for growth investments without increasing leverage.

    Our asset-based lending and working capital solutions can support SCF programs by providing the capital that flows between trading partners. Drawing on a network of over 4,000 investors and access to $15B+ in capital, Zaidwood Capital can structure bespoke working capital facilities that complement SCF arrangements. However, it is critical to recognize that supply chain financing does not guarantee improved financial outcomes. Each arrangement involves risk and requires thorough due diligence; companies should consult their own legal and financial advisors before proceeding.

    Understanding these fundamentals sets the stage for exploring the specific structures available for implementing an SCF strategy.

    How Supply Chain Financing Benefits Buyers and Suppliers

    Supply chain financing benefits both buyers and suppliers by optimizing payment cycles and strengthening trade relationships. Unlike traditional trade credit, which often pits buyer and supplier interests against each other, this strategic working capital tool enables companies to manage cash flow more effectively without incurring additional debt. We at Zaidwood Capital help clients implement these programs, creating value on both sides of the transaction.

    Benefits for Buyers

    For buyers, supply chain financing extends days payable outstanding (DPO) without damaging supplier trust. By allowing a company to defer payments to a later date—often up to 60 or even 90 days—while the supplier receives early payment through the financing platform, the buyer preserves cash that can be reinvested in growth or used to reduce existing debt. This arrangement mirrors the working capital preservation achieved through equipment financing: just as equipment loans allow a business to acquire assets without depleting cash reserves, supply chain financing frees up liquidity that would otherwise be tied up in short-term payables. Moreover, offloading early-payment pressure to a third-party funder strengthens supplier relationships, giving suppliers reliable capital access that fosters collaboration and reduces disruption risk. We advise structuring programs so extended terms don’t strain partnerships.

    Benefits for Suppliers

    For suppliers, supply chain financing provides early payment at a far lower cost than factoring or merchant cash advances. By leveraging the buyer’s credit profile, suppliers can convert approved invoices into cash within days rather than waiting 30, 60, or 90 days. This rapid liquidity reduces reliance on expensive debt consolidation, which merely restructures old obligations without improving ongoing cash flow. Supply chain financing acts as a form of working capital for merchants, offering early payment without traditional debt. Suppliers can use the accelerated payments to fund raw material purchases, meet payroll, or invest in efficiency improvements without taking on high-cost debt. Unlike reactive restructuring, SCF aligns payment timing with actual cash conversion cycles, helping suppliers maintain a healthy debt-service coverage ratio and avoid the downward spiral that often triggers the need for consolidation. This flexibility is especially valuable for middle-market companies operating with thin margins.

    These mutual benefits make supply chain financing a cornerstone of modern working capital management, transforming payment cycles into strategic assets for both parties. We at Zaidwood Capital help businesses design programs that unlock these advantages. Next, we will discuss how to implement a program effectively.

    Supply Chain Financing vs. Traditional Factoring: A Detailed Comparison

    Having explored the fundamentals of supply chain financing, we now compare this buyer-centric approach with traditional factoring. The differences in structure, risk, and relationship dynamics can substantially impact a company’s working capital strategy.

    The Working Capital Optimization Framework

    Supply chain financing is a cornerstone of modern working capital optimization, enabling companies to accelerate cash flow while preserving strong buyer–supplier relationships. By converting approved invoices into early payments for suppliers, this buyer-led approach shortens the cash conversion cycle and reduces days payable outstanding without straining the buyer’s own liquidity. In a typical SCF structure, the buyer approves an invoice and a third-party funder pays the supplier at a discount, with the buyer settling the full amount on the original due date—effectively extending the buyer’s DPO while injecting early cash into the supplier’s business. We integrate supply chain finance into a broader liquidity strategy that considers asset-based lending, dynamic discounting, and—where appropriate—global lending services to optimize cash flow across the supply chain.

    A well-designed supply chain financing program not only frees up cash tied in receivables but also provides suppliers with access to lower-cost credit, which in turn strengthens supply chain resilience. The framework evaluates invoice volumes, supplier segmentation, and payment terms to identify which invoices are best suited for early discounting, as opposed to traditional factoring or outright payment term extensions. As a boutique M&A and capital advisory firm with deep expertise in payables advisory and asset-based lending, we help mid-market businesses structure these programs to complement existing bank lines and support growth objectives. This disciplined approach ensures that SCF delivers measurable improvements to the weighted average cost of capital and working capital ratios.

    Key Differences from Traditional Factoring

    While both supply chain financing and factoring accelerate supplier payments, they differ sharply in initiation, relationship impact, and cost. The table below outlines six critical dimensions that corporate treasurers should weigh when selecting a working capital tool.

    Feature Supply Chain Financing Traditional Factoring
    Initiation Buyer-initiated, based on approved invoices Supplier-initiated, often requires sale of receivables
    Buyer/Supplier Relationship Strengthens partnership; buyer facilitates early payment Can strain relationship; supplier bears cost and gives up control
    Cost Structure Lower cost, often tied to buyer’s credit rating Higher discount rates; fees based on receivable quality
    Risk Credit risk primarily on buyer; lower overall systemic risk Supplier risk (non-payment by buyer) can be transferred to factor
    Flexibility Scalable; can be selectively applied to approved invoices Often requires selling entire receivable portfolio; less granular
    Credit Dependence Primarily buyer’s credit profile Supplier’s credit and the creditworthiness of its customers

    Because supply chain financing is buyer-initiated, it fosters a collaborative process: the buyer approves an invoice and invites the supplier to discount it, reinforcing commercial trust. Traditional factoring, by contrast, is supplier-driven and can strain relationships when a supplier sells receivables without the buyer’s knowledge, often signaling cash-flow pressure. Cost structures illustrate another clear divide—supply chain financing leverages the buyer’s stronger credit rating to secure lower financing rates, a dynamic confirmed by Securities Industry and Financial Markets Association (SIFMA) credit risk benchmarks that associate buyer-led programs with reduced default probabilities and cheaper terms. Factoring, however, prices risk based on each receivable’s quality, resulting in higher overall costs for the supplier.

    Risk allocation also separates the two approaches. Supply chain financing concentrates credit exposure on the buyer, who is typically a lower credit risk, thereby limiting systemic consequences for the funder. Factoring transfers non-payment risk to the factor, but that protection is embedded in the discount rate and ultimately borne by the supplier. On the flexibility front, a supply chain financing program can be tailored to specific approved invoices, giving treasurers precise control over cash outflows. Factoring frequently requires the sale of the entire accounts receivable portfolio, which sacrifices granularity and strategic liquidity management. Finally, credit dependence underscores a key accessibility advantage: SCF programs tie to the buyer’s credit profile, enabling even smaller or lower-rated suppliers to obtain affordable early payment, whereas factoring examines both the supplier’s credit and the creditworthiness of its customers, potentially excluding weaker participants from cost-effective options.

    These comparisons illustrate why many growth-focused companies prefer supply chain financing as a cornerstone of their working capital strategy. By selecting the right tool, companies can avoid the pitfalls of one-size-fits-all financing and strategically manage liquidity. The infographic below distills the core contrasts visually.
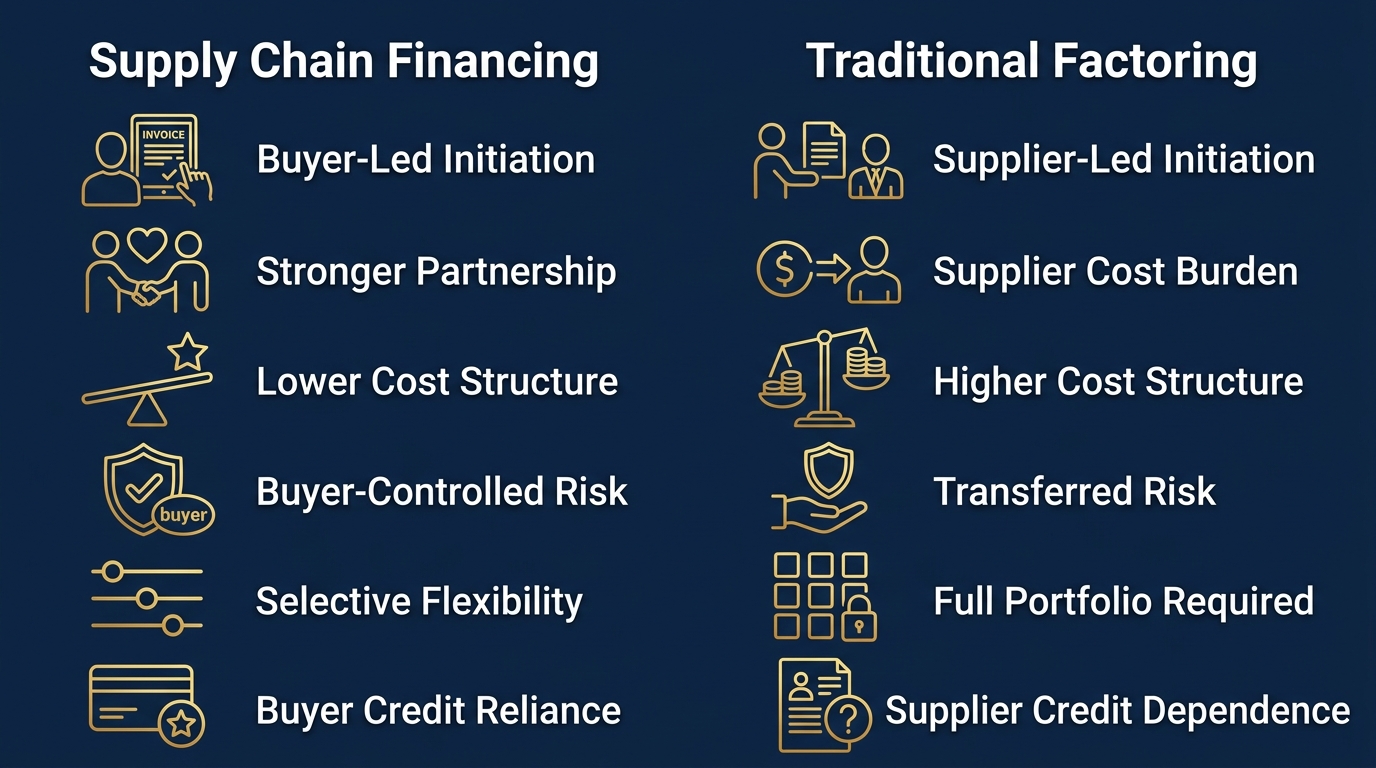
    Two-column comparison infographic showing Supply Chain Financing versus Traditional Factoring with gold outlined icons on deep navy background
    Supply chain financing vs. traditional factoring comparison

    In practice, adopting supply chain financing can reduce total financing costs, deepen supplier loyalty, and build a more resilient supply chain. For mid-market firms, the buyer-led model often aligns incentives across the supply base more effectively than traditional factoring. As the next section explores, implementing such a program demands careful alignment of invoice processes, funding partners, and payables strategy to match your company’s risk appetite and growth objectives.

    Managing Risks and Best Practices in Supply Chain Finance Implementation

    Identifying and Mitigating Implementation Risks

    While supply chain financing delivers significant liquidity benefits, companies must navigate a range of operational, credit, and regulatory risks. A disciplined risk assessment and a mitigation plan tailored to each category protect both the buyer and its supplier community.

    Risk Category Description Mitigation Strategy
    Buyer Credit Risk Risk of buyer defaulting on approved invoices Thorough credit assessment; use credit insurance or guarantees
    Supplier Onboarding Complexity Difficulty in educating and onboarding numerous suppliers Phased rollout; dedicated supplier support team; clear communication
    Legal/Regulatory Compliance Non-compliance with securities or lending regulations Engage legal counsel; comply with FINRA and state regulations (e.g., through Finalis for securities)
    Technology Integration Integration with existing ERP/accounting systems Use API-first platforms; pilot with a subset of transactions
    Program Scalability Unable to scale to larger supplier base or transaction volumes Design flexible program parameters; partner with experienced finance provider

    Among these, buyer credit risk and legal/regulatory compliance demand the highest attention. Buyer credit risk can undermine the entire program if an anchor buyer cannot meet its obligations, making robust credit analysis and, where appropriate, credit insurance or guarantees essential. On the regulatory side, any supply chain finance structure that touches securities must align with industry rules. The guidelines published by the Securities Industry Trade Association and FINRA emphasize rigorous compliance frameworks. We reinforce that Zaidwood Capital is not a registered broker-dealer; all securities transactions are conducted through Finalis Securities LLC, ensuring that programs adhere to applicable regulations without exposing the sponsoring company to unauthorized activities. Proactive legal counsel and early engagement with compliance resources help contain these risks.

    Best Practices for Program Success

    A well-designed supply chain financing program incorporates best practices that accelerate adoption, maintain operational integrity, and adapt to evolving business needs. Drawing on our experience with middle-market working capital solutions, we recommend the following:

    1. Structured supplier education and dedicated support. Phased rollouts, clear communication of the program’s value, and a dedicated onboarding team reduce friction and drive higher supplier participation. Suppliers that understand how early payment improves their cash flow are far more likely to enroll and remain active. Buyers can further incentivize early adoption by offering favorable early payment terms during the initial phase.
    2. Technology-first platform selection. Choose API-first platforms that integrate seamlessly with existing ERP and accounting systems. A pilot phase with a subset of transactions validates system performance before full-scale deployment. Our own Precision Catalyst platform illustrates how data-driven matchmaking and digital engagement can streamline supplier onboarding and transaction processing—without adding unnecessary complexity. The Velocity Matrix framework ensures technology deployment stays aligned with execution timelines.
    3. Ongoing performance monitoring. Establish KPIs such as days payable outstanding (DPO), supplier adoption rates, and early-payment discount capture. Regular reviews of these metrics, combined with feedback loops from suppliers, allow for continuous refinement. As we discuss in our debt consolidation and cash-flow resources, improving working capital efficiency often depends on visibility into real-time financial data and disciplined performance tracking. Internal dashboards and structured supplier surveys reinforce the feedback loop and provide early warnings.
    4. Scalable program architecture. Design flexible program parameters from the start, including tiered financing limits and the ability to add new suppliers without major reconfiguration. Partnering with an experienced finance provider that understands middle-market dynamics ensures the program can grow alongside the buyer’s transaction volumes. Regular scalability reviews help the program keep pace with corporate growth.

    With these best practices in place, companies can confidently explore more advanced SCF structures and unlock the full strategic potential of their working capital.

    Evaluating Supply Chain Financing as a Strategic Capital Solution

    Beyond traditional debt and equity, supply chain financing (SCF) provides a strategic way to optimize working capital without diluting ownership or incurring high-interest debt. SCF is a suite of solutions that improve cash flow by allowing buyers to extend payment terms while suppliers receive early payment on approved invoices, enhancing supply chain resilience.

    SCF typically involves a third-party financier—often a bank or fintech—that advances funds to suppliers based on the buyer’s approved payables. For example, a manufacturer in West Palm Beach could approve a $100,000 supplier invoice, have the financier pay the supplier immediately, and then repay the financier 90 days later, preserving its own working capital. The supplier gains faster access to cash, often at a lower cost than factoring, while the buyer strengthens the relationship and reduces supply chain risk.

    When evaluating SCF as a strategic capital solution, we consider several criteria: the cost of capital relative to other short-term financing, whether the arrangement is treated as on- or off-balance-sheet debt, how seamlessly it integrates with existing ERP and invoicing systems, and its scalability as transaction volumes grow. Unlike business acquisition financing—where Zaidwood Capital structures layered debt and equity for transformative transactions—and the capital raises we advise for food and beverage brands, SCF focuses on recurring working-capital needs rather than one-time events. It is not a one-size-fits-all solution; companies must assess their cash conversion cycle, supplier concentration, and financial covenants. Like all financial solutions, supply chain financing carries costs and risks that must be evaluated carefully. Additionally, businesses should verify that any SCF platform or financier complies with applicable regulations, including oversight by the Financial Industry Regulatory Authority.

    SCF is most valuable for companies with stable buyer-supplier relationships and predictable payment cycles, helping them unlock trapped cash to fund growth without sacrificing equity. However, it is only one part of a comprehensive capital strategy, and advisory guidance can help firms choose the right mix.

    Frequently Asked Questions About Supply Chain Financing

    Now that we’ve covered the fundamentals of supply chain financing, let’s address common questions.

    What is supply chain financing? Supply chain financing is a collaborative, technology-enabled set of solutions that optimize payment terms between buyers and suppliers, improving working capital without traditional borrowing.

    Who can benefit from supply chain financing? Mid-market and growth-stage companies seeking to strengthen supplier relationships, reduce supply chain risk, and free up cash for strategic initiatives are ideal candidates for supply chain finance.

    Does Zaidwood Capital offer supply chain financing advisory? Yes. As a Boutique M&A and Capital Advisory Firm, we advise on supply chain financing within our Asset-Based Lending / Working Capital advisory. Results vary; we recommend independent due diligence and consultation.

    Leveraging Supply Chain Financing for Sustainable Growth

    Beyond traditional capital formation, supply chain financing optimizes working capital between buyers and suppliers. According to Zaidwood Capital’s global lending guide, types like invoice financing, reverse factoring, and dynamic discounting unlock liquidity, while specific solutions such as equipment financing address asset needs without draining cash reserves. This approach underpins our full-cycle advisory, leveraging over $15 billion in accessible capital to match businesses with the right financing mix. Through our advisory in asset-based lending, we integrate these instruments to fuel sustainable growth, always within a risk-managed framework.
    Resources

  • Supply Chain Financing Explained: Essential Guide for 2026

    Supply Chain Financing Explained: Essential Guide for 2026

    Table of Contents

    The Foundations of Supply Chain Financing

    Supply chain financing encompasses a set of technology-driven solutions that allow buyers and suppliers to improve working capital without relying on traditional trade finance instruments such as letters of credit. According to Zaidwood Capital’s resource library, SCF is a vital component of global lending alternatives, helping businesses stabilize cash flows while deepening trading relationships.

    Reverse factoring is one of the most widely adopted structures. In this model, a corporate buyer confirms an invoice and a financial institution pays the supplier early at a modest discount, while the buyer repays the financier on a later date. The supplier receives faster cash, the buyer preserves liquidity, and the funder earns a predictable margin—a mutually beneficial arrangement.

    Dynamic discounting offers an alternative mechanism: the buyer uses its own cash to pay invoices ahead of term in exchange for a sliding-scale discount. This gives suppliers near-immediate access to funds at a cost that adjusts with the speed of payment. Inventory finance rounds out the toolkit by providing dedicated funding against stock held in the supply chain, reducing carrying costs and freeing capital for growth.

    Many businesses also layer in equipment financing to complement these solutions, funding the tangible assets that keep supply chains moving. Together these instruments provide greater cash-flow predictability, reduce supplier concentration risk, and strengthen the resilience of the entire supply network.

    Understanding Supply Chain Financing Benefits and Distinctions

    Supply chain financing has emerged as a key buyer-led solution that enables companies to optimize working capital while strengthening supplier relationships. Unlike traditional factoring, which is initiated when a supplier sells its receivables, SCF is initiated by the buyer, leveraging its own credit rating to secure attractive financing terms for its suppliers. This fundamental shift creates a more collaborative and cost-effective financing environment. In this section, we explore the core benefits and six critical distinctions that set supply chain financing apart from traditional factoring.

    The table below compares these financing methods across six critical aspects:

    Supply Chain Financing vs Traditional Factoring
    AspectSupply Chain FinancingTraditional Factoring
    InitiationInitiated by the buyer, leveraging its credit ratingInitiated by the supplier selling its receivables
    Credit AssessmentBased on buyer’s creditworthiness, not supplier’sBased on supplier’s customer credit and invoice quality
    Cost of CapitalLower cost, typically buyer’s cost of funds plus a small marginHigher fees, discount plus service charges
    Working Capital ImpactExtends buyer’s payables without straining supplier, optimizes cash conversion cycleAccelerates supplier cash flow but may not benefit buyer’s DPO directly
    Supplier RelationshipStrengthens buyer-supplier relationship through collaborative liquidityCan be perceived as supplier distress; may damage relationship
    Risk ExposureCounterparty risk primarily on the buyer; operational and legal risksRisk of non-payment by debtor; recourse arrangements common

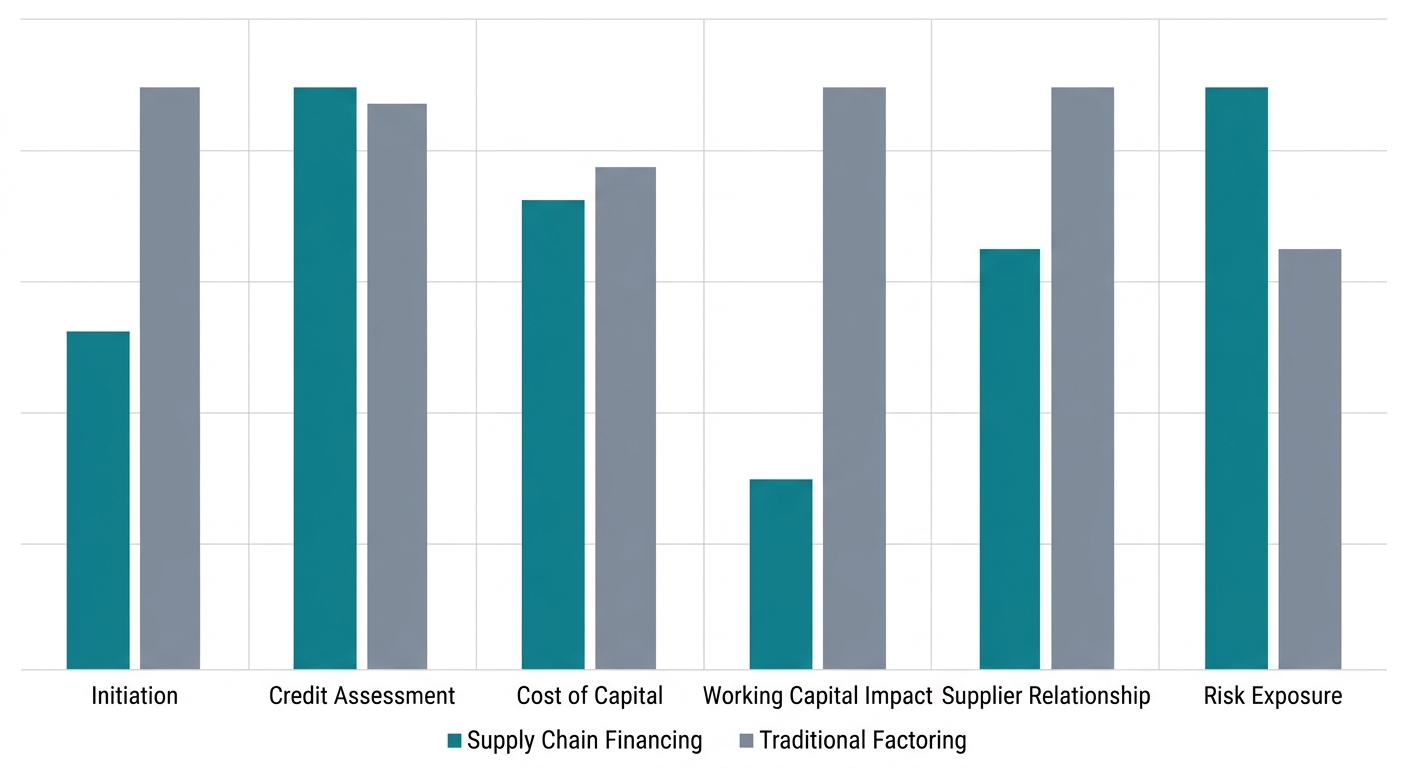
    From a strategic standpoint, supply chain financing delivers a decisive edge by lowering the cost of capital—leveraging the buyer’s credit rather than relying on supplier-level assessments—while simultaneously extending payment terms without squeezing supplier liquidity. This structure optimizes the cash conversion cycle for both parties: buyers preserve working capital, and suppliers gain access to affordable, timely funding. Moreover, because SCF is framed as a collaborative liquidity solution rather than a sign of financial distress, it reinforces trust and long-term supplier relationships, which are critical in today’s interconnected supply chains. The risk profile also shifts favorably; counterparty risk concentrates on the financially stronger buyer rather than on diverse, often smaller, suppliers. As recognized by the International Capital Market Association, these distinctions underscore the role of structured supply chain finance in modern capital markets. From our advisory work, we observe that such buyer-led financing not only enhances operational resilience but also aligns with the interests of all supply chain participants. The chart below visualizes how SCF outperforms traditional factoring across these performance dimensions, reinforcing why it has become a preferred strategy for resilient supply chains.

    Bar chart comparing supply chain financing and traditional factoring across six key performance aspects using teal and gray bars

    Supply chain financing versus traditional factoring comparison across six key business aspects

    Key Mechanisms and Structures in Supply Chain Finance

    Modern supply chain financing (SCF) helps businesses optimize working capital through a variety of structured instruments, each designed to align the liquidity needs of buyers and suppliers. The three primary mechanisms—reverse factoring, dynamic discounting, and approved payables finance—differ in how they fund early payments, yet all share the goal of accelerating supplier cash flow while preserving buyer payment terms. Understanding their inner workings and when to apply each is essential for corporate treasurers seeking to build resilient, financially stable supply networks.

    How Reverse Factoring Unlocks Liquidity

    Reverse factoring, often called approved payables finance, follows a disciplined sequence that centers on the buyer’s credit strength. First, the buyer initiates a supply chain finance program with a financial institution (the funder). The buyer then approves supplier invoices and transmits them to the funder via a digital platform. Upon receiving approved invoices, the funder pays the supplier early—generally after applying a small discount—while the original invoice due date remains unchanged. The buyer ultimately repays the funder at the agreed-upon extended term, thereby preserving its own cash on hand. This structure enables suppliers to access lower-cost capital than traditional factoring because the funding cost is benchmarked against the buyer’s superior credit rating, not the supplier’s.

    For buyers, the arrangement stretches payment terms without squeezing the financial health of their supply chain partners, reducing the risk of supplier insolvency. For suppliers, early payment at competitive rates directly improves working capital. Importantly, supply chain finance programs—especially reverse factoring—are subject to SEC disclosure requirements that promote corporate transparency; stakeholders can monitor regulatory developments through SEC regulatory news and updates. These obligations reinforce the need for robust reporting practices in any SCF initiative.

    Dynamic Discounting vs Approved Payables Finance

    Dynamic discounting takes a different approach: it is a buyer-funded mechanism where the buyer voluntarily offers early payment to suppliers in exchange for a discount that increases the earlier payment is made. The sliding scale is typically calculated per day before the net due date, allowing the buyer to earn an implicit, risk-free return on its surplus cash. Because no external funder is involved, dynamic discounting is most attractive to corporate treasuries that hold ample liquidity and seek to optimize cash returns without introducing third-party credit risk.

    By contrast, approved payables finance (including reverse factoring and multi-bank platforms) relies on an external funder that purchases approved receivables against the buyer’s credit. This model is preferred when the buyer wants to inject liquidity into its supply chain without deploying its own cash, or when it lacks the excess balances needed for dynamic discounting. The following table summarises the key instruments available:

    Types of Supply Chain Finance Instruments
    InstrumentDescriptionTypical UsersBenefitsLimitations
    Reverse FactoringBuyer-initiated program where a funder pays supplier invoices early against the buyer’s credit ratingLarge buyers with strong credit, multiple SME suppliersLower financing cost, stable supply chainRequires buyer commitment; supplier onboarding complexity
    Dynamic DiscountingBuyer offers early payment to suppliers in exchange for a sliding-scale discount based on how early payment is madeBuyers with excess cash; suppliers needing liquidityNo third-party funder; buyer earns better return on cashOnly works if buyer has surplus cash; discount negotiation can be complex
    Approved Payables FinanceSimilar to reverse factoring but often includes multiple buyers and suppliers on a multi-bank platformMultinational corporates, banks, and large supplier networksScalable, automated, integrated with ERP systemsHigh setup costs; requires robust technology integration

    Selecting the right instrument depends on a corporation’s treasury priorities. Reverse factoring shines when the goal is to fortify the supply chain without significant cash outlay, leveraging the buyer’s credit for the benefit of the entire supplier base. Dynamic discounting offers the best fit when the buyer holds surplus cash and can capture a safe, immediate return. For large multinationals managing sprawling supplier networks, approved payables finance delivered through multi-bank platforms delivers the scalability and automation needed to process thousands of invoices efficiently while maintaining compliance with evolving disclosure standards.

    Integrating Technology Platforms into Supply Chain Finance

    Technology platforms are the connective tissue that makes modern supply chain finance practical at scale. Through ERP-integrated portals and, increasingly, blockchain-based ledgers, these systems automate invoice verification, trigger early-payment offers, and execute fund transfers with minimal manual intervention. As soon as a buyer approves an invoice, the platform can instantly notify the supplier and, if the program rules are met, initiate payment to a designated account. Real-time dashboards then allow all parties—buyers, suppliers, and funders—to track invoice status, discount terms, and cash positions, reducing both operational friction and the opportunity for fraud.

    This digitization eliminates paper-based processes and cuts approval cycles from weeks to hours, a critical factor when working capital is tight. Moreover, built-in audit trails align with regulatory expectations, helping firms meet SEC disclosure obligations without additional overhead. As supply chain financing continues to evolve, the seamless integration of these platforms will remain a cornerstone for driving efficiency, transparency, and resilience across global trade ecosystems.

    Implementing Supply Chain Finance for Working Capital Optimization

    Having established the strategic value of supply chain financing for working capital optimization, this section moves from theory to execution. For mid-market CFOs and treasurers, capturing the liquidity benefits demands a structured, three-phase approach: internal readiness assessment, partner selection, and a controlled pilot-to-rollout journey. As Zaidwood Capital’s own resource on preserving working capital demonstrates, instruments that convert large outlays into manageable installments—whether for equipment purchases or supplier invoices—free up cash for essential operations. We focus on practical metrics and milestones that accelerate the cash conversion cycle. The guidance below synthesizes our advisory experience into actionable steps.

    Assessing Your Company’s Readiness for Supply Chain Finance

    Before approaching funders, we recommend a thorough internal review. Several key indicators signal that a company will benefit from receivables financing and can attract competitive terms.

    • Cash Conversion Cycle Metrics: A high days sales outstanding (DSO) or a meaningful opportunity to extend days payable outstanding (DPO) relative to days inventory outstanding (DIO) indicates trapped working capital. If your DPO is well below industry peers, a supply chain finance program can generate immediate liquidity.
    • Credit Profile: Funders typically seek an investment-grade or near-investment-grade rating. Strong financial fundamentals—stable revenue, healthy EBITDA margins, and manageable leverage—can offset a borderline rating.
    • Supplier Segmentation: Prioritize strategic, high-volume suppliers or those reliant on early payment. A segmentation framework identifies the top 10–20 suppliers whose early-payment discount appetite will maximize working-capital lift and simplify onboarding.
    • Technology Infrastructure: Real-time approved-invoice data exchange is essential. Your ERP system (SAP, Oracle, Microsoft Dynamics) should support API integrations or secure file transfers to a funder’s platform.
    • Internal Commitment: Successful programs require dedicated cross-functional resources—treasury, procurement, legal, and IT. Our team provides a readiness checklist to ensure all stakeholders are aligned before launch.

    Selecting the Right Supply Chain Finance Partner

    Choosing the right SCF partner is critical. We evaluate funders and technology providers across multiple dimensions, weighting criteria to align with your strategic objectives.

    • Funder Credit Capacity: Assess the funder’s ability to handle your supply chain’s invoice volume and peak funding needs. Look for a track record of stability and diverse capital sources.
    • Platform Scalability: The technology platform must integrate with your ERP and support rapid supplier onboarding. Examine API capabilities, security protocols, and dashboard analytics.
    • Legal and Structuring Expertise: The partner should possess deep experience with receivables purchase agreements, true-sale opinions, and cross-border trade finance if relevant. Our team can review legal terms to mitigate counterparty risk.
    • Supplier-Onboarding Support: A partner offering dedicated enrollment resources accelerates adoption and reduces internal strain.
    • Pricing Transparency: Evaluate the discount margin relative to your weighted average cost of capital (WACC) and confirm all fees are clearly disclosed.

    We run a structured RFP with weighted scoring. Early preparation of documents—financials, tax returns, credit application—mirrors the requirements Zaidwood Capital’s equipment financing resource outlines.

    Steps to Launch and Manage a Program

    With readiness confirmed and a partner selected, execution follows a phased roadmap. We guide clients through:

    1. Pilot Design: Select 5–10 friendly suppliers and run a controlled invoice-discounting cycle. Measure the impact on DPO and supplier satisfaction, then refine workflows.
    2. Legal Documentation: Finalize master receivables purchase agreements and supplier participation agreements. The onboarding documentation process mirrors the requirements for equipment financing—Zaidwood Capital can help you prepare the necessary financial information.
    3. Supplier Onboarding: Communicate program benefits, provide training, and assist with platform enrollment to drive adoption.
    4. Full Rollout: Expand to the broader supplier base, integrating governance and KPI monitoring.

    The table below outlines the full implementation roadmap, mapping each phase to key activities, timelines, and responsible parties.

    Supply Chain Finance Implementation Roadmap
    PhaseKey ActivitiesTypical TimelineResponsible Party
    Internal Readiness AssessmentAnalyze cash conversion cycle, supplier segmentation, credit rating4–6 weeksCFO / Treasury
    Partner SelectionRFP to funders and tech platforms; legal due diligence6–12 weeksProcurement & Legal
    Pilot ProgramOnboard top 10 suppliers, test workflows, validate savings8–12 weeksCross-functional team
    Full Rollout & GovernanceExpanding to full supplier base, establishing KPIs, ongoing risk monitoring6–12 monthsTreasury & Operations

    Ongoing governance tracks KPIs like DPO improvement, supplier adoption rate, and cost-of-funds versus WACC, with periodic risk reviews. This content is educational, not investment advice. To discuss your implementation, we invite you to Book A Call.

    Mitigating Risks and Ensuring Success in Supply Chain Finance Programs

    As companies expand their supply chain financing initiatives, the complexity of managing counterparties, operations, and regulatory landscapes introduces a range of risks that can undermine program stability. We understand that a structured approach to identifying and mitigating these risks is essential for building lasting SCF resilience. The following table outlines the primary risk categories, along with their concrete manifestations and proven mitigation strategies.

    Risk Category Description Examples Mitigation Strategy
    Counterparty Risk Buyer payment default or credit downgrade Default, rating decline Credit analysis, diversification, credit insurance
    Operational Risk Process failures, IT disruptions, invoice errors Platform outage, data errors Dual-approval workflows, disaster recovery testing
    Legal & Regulatory Risk Non-compliance with securities/tax laws Misclassification, tax challenges Legal counsel, SEC monitoring, ICMA guidelines
    Technology & Cybersecurity Risk Data breaches, hacking, integration gaps Ransomware, data leak Cybersecurity audits, encryption, vendor assessments

    While these targeted measures address distinct vulnerabilities, truly robust supply chain financing programs require an integrated risk management framework. Counterparty due diligence must be paired with operational resilience so that a single buyer default does not cascade through the entire supply network. Similarly, legal compliance—guided by standards from the International Capital Market Association (ICMA)—should be embedded alongside aggressive cybersecurity protocols. Implementing regular audits and engaging specialized cyber security consulting services can help fortify the SCF platform against evolving digital threats.

    Continuous monitoring and adaptive governance are what keep risk controls effective over time. We recommend stress testing exposure under adverse scenarios, conducting periodic independent audits of processes and technology, and updating governance structures to reflect new threats. By embedding proactive oversight into the program’s DNA, companies can move from reactive firefighting to sustained resilience. This forward-looking posture not only safeguards capital flows but also strengthens the confidence of suppliers and investors alike, setting the stage for scalable growth.

    Common Questions About Supply Chain Financing

    With foundational concepts in place, we turn to the questions businesses most often ask about supply chain financing.

    What exactly is supply chain financing?

    Supply chain financing—also called reverse factoring—is a buyer-led program. The buyer’s stronger credit standing lets suppliers collect early payment at a lower cost than traditional borrowing.

    How does the process work step by step?

    First the buyer approves invoices. Then a financial institution pays the supplier early, deducting a small fee. Finally the buyer remits the full invoice amount to the institution on the original due date.

    How does supply chain funding differ from factoring?

    Factoring is initiated by the supplier and can be more expensive. Reverse factoring, in contrast, relies on the buyer’s credit quality and happens only with the buyer’s direct participation.

    Who qualifies for these supply chain funding programs?

    Suppliers need approved invoices from a participating buyer. They also must complete the financing platform’s know-your-customer verification before accessing the early-payment facility.

    Having addressed the most frequent questions, the next stage is understanding how to put this knowledge into action.

    Strategic Considerations for Corporate Finance Leaders

    Corporate finance leaders should view M&A as a strategic growth lever, not just a transaction. Supply chain financing unlocks working capital and strengthens liquidity without adding traditional debt. The right mix of mezzanine, venture debt, and equity aligns capital structure with company stage and goals. Comprehensive due diligence—financial, legal, operational, human capital—flags risks and value drivers before any deal. Tailored advisory matches financial strategy to corporate objectives, and our network of 4,000+ investors and $15B+ capital accelerates deal flow and improves terms. Once strategic direction is clear, execution becomes the priority.

    This article was researched and written with the assistance of AI tools.

    Resources