Tag: Middle Market M&A

  • What Is an Investment Bank? Key Services Explained

    What Is an Investment Bank? Key Services Explained

    Table of Contents

    The Role of Investment Banks in Modern Finance

    Understanding what is an investment bank is essential to grasping modern financial markets, as these institutions serve as vital intermediaries between companies seeking capital and the investors who provide it. According to the CFA Institute, the global standard-setter for the investment industry, investment banks facilitate capital formation, mergers and acquisitions, and market making, driving economic growth globally today.

    Investment banks perform three primary functions: capital raising, mergers and acquisitions advisory, and market making. In capital raising, we offer capital raising solutions that leverage our extensive investor network to secure equity and debt financing. In mergers and acquisitions, we advise on deal structuring, valuation, and negotiation, ensuring strategic alignment. Market making provides liquidity and price discovery, but boutique firms typically focus on advisory, delivering personalized, high-touch service enhanced by tools like our Sovereign Data Nexus and Velocity Matrix. These functions collectively channel capital to productive enterprises, fueling innovation and economic expansion.

    At Zaidwood Capital, we are redefining Financial Services 3.0 as a Boutique M&A and Capital Advisory Firm, combining proprietary data access via our Sovereign Data Nexus with precision execution through our Velocity Matrix to accelerate deals. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Investment Banking Services: From Advisory to Capital Markets

    When clients ask what is an investment bank, we answer with a clear definition: A financial institution that provides strategic advisory and capital-markets services to corporations, governments, and institutions. Unlike commercial banks that focus on deposit-taking and lending, investment banks operate on a fee-based model, guiding complex transactions like mergers and acquisitions and large-scale capital raising.

    Investment Bank vs. Commercial Bank
    Feature Investment Bank Commercial Bank
    Primary Focus Advisory & Capital Markets Deposits & Lending
    Revenue Model Fee-based Interest-based

    This distinction is foundational. While commercial banks serve everyday financial needs, investment banks unlock growth through corporate finance advisory, deal orchestration, and access to deep capital pools.

    Our firm’s advisory practice spans the full continuum of mergers and acquisitions—from target identification and valuation to negotiation and close—while our capital-markets capabilities help clients structure and secure equity, debt, and structured solutions. For a growing enterprise seeking capital raising, we craft strategic materials like pitch decks, business plans, and pro forma financials, then leverage our global network of over 4,000 institutional and private investors to create institutional introductions.

    Mergers and Acquisitions: How Investment Banks Drive Deal Execution

    To fully appreciate what an investment bank does in the context of mergers and acquisitions, it helps to examine the entire deal lifecycle. Investment banks serve as strategic partners that bring financial expertise, proprietary data tools, and a global investor network to the table. We follow a three-phase framework that covers deal sourcing and initial pitch, rigorous due diligence and financial modeling, and finally negotiation, structuring, and closing.

    Deal Sourcing and Initial Pitch

    We proactively identify acquisition targets or divestiture opportunities through our proprietary Sovereign Data Nexus and long-standing industry relationships. By continuously monitoring market signals and capital flows, we surface potential transactions that align with a client’s strategic objectives. Once a promising opportunity is identified, we craft a tailored pitch book that outlines a compelling investment thesis, preliminary valuation ranges, and a roadmap for value creation.

    Due Diligence and Financial Modeling

    Once a letter of intent is signed, we lead a comprehensive due diligence process that examines financial statements, operational metrics, legal risks, and market conditions. Following the best practices outlined by the CFA Institute, our team validates the target’s earnings quality, working capital dynamics, and growth assumptions. We build a suite of valuation models—discounted cash flow, precedent transaction, and leveraged buyout analyses—to triangulate intrinsic value and stress-test deal economics.

    Negotiation, Structuring, and Closing

    With due diligence findings in hand, we advise on deal structure—whether a stock or asset purchase, and how earn-outs, seller financing, or contingent consideration can bridge valuation gaps. We take the lead in negotiations, coordinating closely with legal and tax advisors to translate commercial terms into binding documents. Throughout this phase, our secure deal vaults serve as central hubs for all transaction materials, accelerating the exchange of sensitive information.

    Capital Raising Strategies: Equity and Debt Financing Pathways

    A core function of an investment bank is helping companies raise capital to fuel growth, execute strategic initiatives, or navigate complex transactions. At Zaidwood Capital, we specialize in capital raising as part of our Full-Cycle M&A and Capital Advisory services, connecting businesses with the right mix of equity and debt financing.

    Equity Financing: Private Placements and Growth Equity

    Equity financing allows businesses to raise capital by selling ownership stakes. Investment banks facilitate private placements, offering shares to accredited investors and institutional investors rather than public markets, which can be faster and more flexible. At Zaidwood Capital, we leverage a network of more than 4,000 investors to connect companies with the right capital providers.

    Debt Financing and Structured Solutions

    Debt financing allows companies to borrow capital without diluting ownership, preserving control for existing shareholders. Investment banks structure a range of instruments: senior debt is secured by company assets, carries a lower interest rate, and ranks first in repayment priority; mezzanine financing is subordinated, carries higher cost, and often includes equity warrants.

    Equity vs. Debt Financing
    Dimension Equity Debt
    Ownership Diluted Preserved
    Repayment None Regular Payments

    Preparing Your Business for a Capital Raise

    Thorough preparation significantly increases the likelihood of a successful capital raise. Start by compiling audited or reviewed financial statements that demonstrate historical performance and projections. A credible business valuation sets realistic expectations for deal terms. Develop a compelling investor pitch deck that clearly articulates the company’s value proposition, growth strategy, and use of funds.

    Boutique Investment Banking: The Zaidwood Capital Advantage

    If the searcher’s question is what is an investment bank, the clearest answer begins with the distinct categories of the industry. Investment banks facilitate the flow of capital, but they operate across a spectrum from boutique advisory firms to global full-service institutions and the largest bulge-bracket banks. At one end, boutique firms like Zaidwood Capital deliver high-touch, specialized guidance for mid-market and growth companies.

    Boutique vs. Full-Service vs. Bulge-Bracket
    Type Focus Advantage
    Boutique Advisory Senior Attention
    Bulge-Bracket Global Markets Balance Sheet
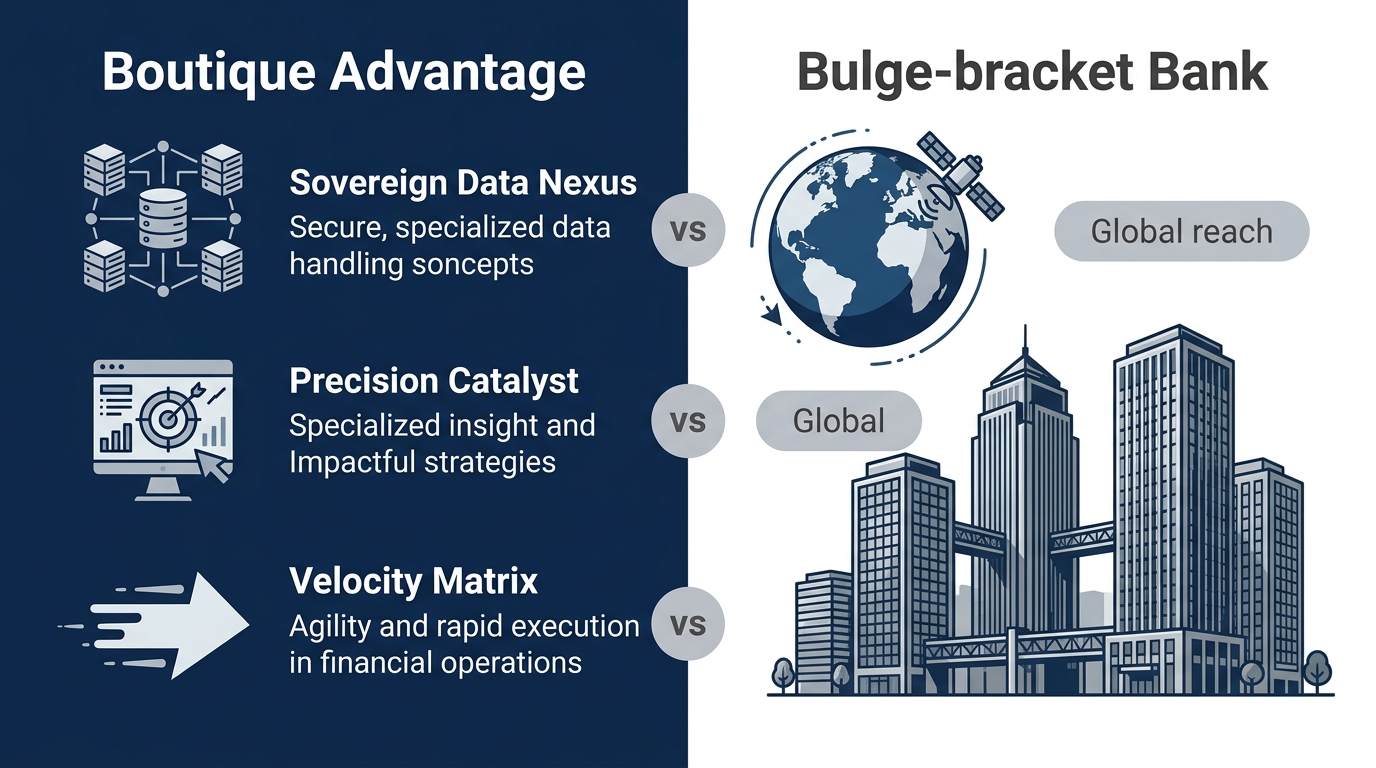
    Side-by-side infographic comparing boutique investment bank advantages with data, marketing, and speed icons versus traditional bulge-bracket bank with globe and buildings

    Comparison infographic showing boutique versus traditional banking advantages

    Common Questions About Investment Banking

    What is an investment bank?
    An investment bank is a financial intermediary that helps companies raise capital and execute mergers and acquisitions. They range from large bulge-bracket institutions to specialized boutique firms like ours, which provide senior-led, personalized advice and sector expertise.

    Unlike traditional investment banks, our boutique advisory provides end-to-end support throughout your transaction lifecycle. Our team brings expertise in mergers and acquisitions and capital raising, leveraging proprietary tools like the Sovereign Data Nexus for data-driven insights and the Velocity Matrix to accelerate execution. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC.
    Resources

  • Best Quality of Earnings Report for Mid-Market Deals 2026

    Best Quality of Earnings Report for Mid-Market Deals 2026

    Table of Contents

    The Role of Quality of Earnings Reports in Mid-Market M&A

    Following a comprehensive due diligence review, buyers and lenders in mid-market M&A transactions focus on the Quality of Earnings (QoE) report, an independent assessment of a target company’s historical financial performance, adjusted for non-recurring items. This analysis goes far beyond audited financials by evaluating revenue sustainability, customer concentration, and the normalization of operating expenses and working capital. A well-prepared quality of earnings report provides a clearer view of recurring EBITDA, which serves as the foundation for valuation and debt sizing.

    Why QoE Matters in Mid-Market Deals

    The insights from an earnings quality analysis routinely reshape transaction terms. Buyers use the adjusted EBITDA to support purchase price adjustments, earnout structures, and net-working-capital targets. Lenders, in turn, demand a validated earnings baseline before committing acquisition debt. Moreover, the QoE often uncovers deferred-revenue patterns or concentration risks that, if ignored, can surface as costly post-close liabilities. In mid-market transactions where information gaps are common, a thorough QoE report reduces post-close surprises and gives the commissioning party a stronger negotiating position.

    Because mid-market companies frequently lack the internal resources to produce a GAAP-independent earnings analysis on their own, many engage specialized M&A advisors to manage the QoE process. At Zaidwood Capital, we integrate the QoE directly into our full-cycle due diligence offering, coordinating with independent accounting firms to deliver a report that buy-side and sell-side clients can rely on during negotiation and financing. We handle all financial data in accordance with rigorous confidentiality standards. For information on how we protect client information, please review Zaidwood Capital Privacy Policy.

    What Defines a Quality of Earnings Report

    A critical subset of due diligence, central to mid-market transaction diligence, is the Quality of Earnings Report, a financial analysis that evaluates the recurring, normalized earnings of a target company. At Zaidwood Capital, we define a QoE report as a rigorous assessment of earnings sustainability, designed to strip out non-recurring items and present a true picture of operating performance. This analysis is a cornerstone of our full-cycle due diligence process for mid-market M&A transactions.

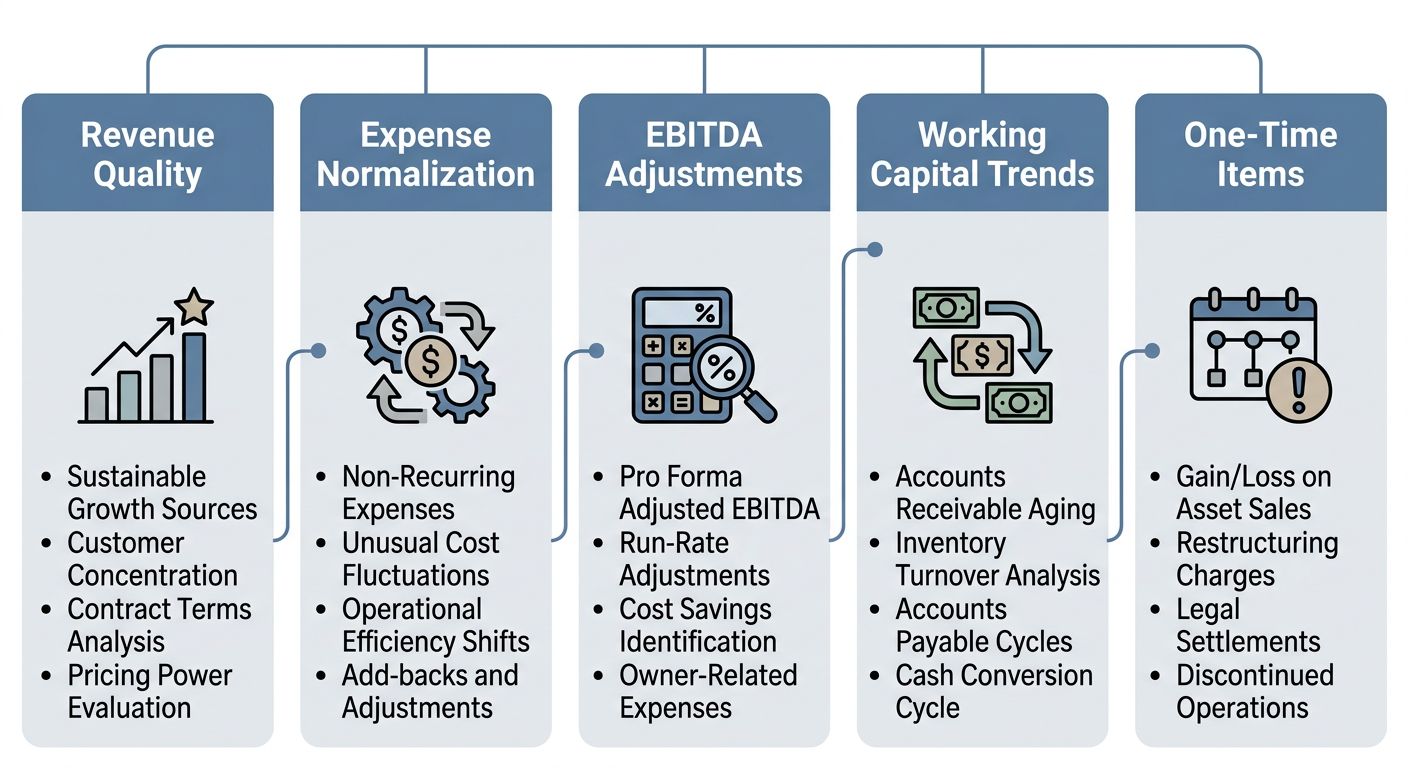
    A comprehensive earnings quality analysis examines several critical areas. Revenue quality scrutinizes the predictability and diversification of income streams. Expense normalization adjusts for one-time costs, owner’s compensation, or other out-of-ordinary expenses. EBITDA adjustments remove non-operating or non-cash items to reflect sustainable earnings. Working capital trends highlight operational liquidity needs and potential cash drags. One-time items, such as litigation settlements or asset sales, are excluded to reveal the underlying earning power. These dimensions collectively inform whether the company’s earnings are sustainable and repeatable for future periods.

    Infographic with five columns representing core areas of a quality of earnings analysis: Revenue Quality, Expense Normalization, EBITDA Adjustments, Working Capital Trends, and One-Time Items, each with icons and bullet lists on a muted blue and gray palette.

    Zaidwood Capital’s Quality of Earnings analysis framework visualized in five key areas.

    By producing a normalized earnings base, the QoE report helps both buyers and sellers reach consensus on valuation. For buy-side M&A professionals, this analysis highlights the true recurring profitability of a target, removing distortions that could inflate or deflate the purchase price. Sellers also benefit, as a well-documented QoE report can justify a premium and accelerate negotiation.

    As part of our Full-Cycle M&A and capital advisory services, we integrate QoE analysis into every engagement to provide clients with clear, defensible financial insights. The report is not an audit; it does not verify financial statement accuracy in compliance with accounting standards. Instead, it offers transaction-specific intelligence that traditional audits often miss. Zaidwood Capital utilizes QoE reports as a core component of its full-cycle due diligence, ensuring that both buy-side and sell-side mandates are grounded in reliable earnings data. By identifying true economic earnings, a QoE report streamlines negotiations and reduces the risk of post-close surprises.

    Next, we examine the core components that define a comprehensive QoE analysis.

    Securities are offered through Finalis Securities LLC, an independent entity from Zaidwood Capital. This content is for informational purposes and does not constitute investment advice.

    Core Components of a Quality of Earnings Analysis

    A quality of earnings report for mid-market deals goes beyond audited financials to uncover the true recurring cash flow a buyer can rely on. In this section, we break down the three pillars of a quality of earnings analysis: normalization adjustments, working capital scrutiny, and EBITDA sustainability. Drawing on Zaidwood Capital’s due diligence expertise, we show how each component strengthens deal-making for institutional and private investors.

    Normalization Adjustments and Add-Backs

    Normalization adjustments strip away non-operational or inflated expenses to present a clean EBITDA. These adjustments are critical because audited financials may include non-recurring gains or expenses that distort the company’s sustainable earning power. In our analyses, we identify above-market owner compensation, one-time legal fees, personal expenses run through the business, and related-party transactions at non-market terms.

    • Owner’s Compensation Adjustment: Aligning above-market owner salary and benefits to industry-standard compensation for a replacement manager
    • Non-Recurring Expenses: One-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition
    • Personal Expenses: Personal travel, entertainment, vehicles, or family members on payroll not related to business operations
    • Related-Party Transactions: Above-market rent, management fees, or service charges paid to entities owned by the seller or their family

    We substantiate each adjustment with corroborating evidence—payroll records, lease agreements, invoices—and provide a clear rationale in our reports. A quality of earnings analysis also flags off-balance-sheet liabilities like operating leases or contingent obligations that can alter deal value. For example, an owner drawing $600,000 when market rate is $200,000 inflates expenses by $400,000, a typical adjustment we see. By documenting every add-back, we give buyers confidence in the normalized earnings figure. Additionally, QoE reports look beyond the balance sheet to identify contingent payments or environmental indemnities that may not be booked but represent real future cash outflows.

    Working Capital Analysis and Debt-Like Items

    Working capital analysis determines the normalized net operating capital needed post-acquisition. We assess seasonal needs, payment cycles, and industry norms, then compare that to the target company’s actual levels. The gap—whether surplus or deficit—becomes an adjustment to the purchase price. For instance, if a business has excess working capital relative to its normalized requirement, the buyer may credit the seller for that amount at closing; conversely, a deficiency reduces the price. Our QoE reports present these adjustments with supporting schedules so that both buyers and sellers can negotiate from a common understanding.

    Debt-like items are obligations that function as debt but are not on the balance sheet as such. Examples include deferred revenue, underfunded pensions, or installment sale obligations. We identify these, quantify their impact, and deduct them from the equity value, just as we would formal debt. This analysis prevents the buyer from inheriting hidden financial burdens and ensures the enterprise value accurately reflects the business’s true financial position.

    EBITDA Quality and Sustainability Assessment

    EBITDA sustainability evaluation dissects the recurring nature of earnings. We examine revenue concentration risk—if a company depends on a single customer for more than 10% of revenue, that concentration creates vulnerability. Customer retention trends, contract renewal probabilities, and churn rates indicate how sticky the revenue base is. We also assess margin stability, checking whether gross and operating margins are sustainable or eroded by pricing pressure. In emerging markets M&A, we place extra focus on revenue concentration and retention because currency swings, regulatory shifts, and political instability can quickly reshape earnings. We evaluate supplier relationships to ensure margins are not artificially supported by short-term concessions, and we consider macroeconomic trends that could influence future earnings. Through our QoE reports, we help buyers distinguish durable cash flows from those that could evaporate post-acquisition, providing a forward-looking perspective essential for informed investment decisions.

    Selecting a Quality of Earnings Provider for Your Mid-Market Deal

    A quality of earnings report for mid-market deals is one of the most important tools for de-risking an acquisition, and choosing the right provider directly influences the credibility of your financial analysis. For companies in the $20M–$100M revenue range, the provider’s expertise, speed, and post-engagement support can make a material difference in how the QoE findings are received by lenders, underwriters, and counterparties.

    Evaluating Boutique Firm Expertise for QoE Analysis

    Boutique firms such as Zaidwood Capital specialize in delivering a highly tailored Quality of Earnings analysis that aligns with the specific dynamics of mid-market transactions. Their teams typically bring deep industry knowledge and direct senior partner involvement, ensuring that the engagement is led by an experienced professional who understands both the financial and strategic dimensions of the deal. In contrast, Big Four accounting firms offer a broad, generalist approach with standardized QoE templates that can miss the nuances of niche sectors. Mid-tier regional firms occupy a middle ground, providing moderate specialization but often with less senior oversight than a dedicated boutique.

    The critical differentiator is the level of partner engagement. At a boutique, the senior team leads the QoE analysis from start to finish, which shortens feedback loops and results in a more focused report. Big Four firms typically rely on junior staff for the bulk of the fieldwork, with partner review at the conclusion, while mid-tier firms show variability in senior involvement. This direct access to senior talent often translates into faster turnaround times and more actionable insights for the acquirer.

    The following comparison table summarizes key distinctions to inform your selection.

    Common Add-Backs and Adjustments in Quality of Earnings Reports
    Adjustment TypeDescriptionTypical EBITDA ImpactCommon Example
    Owner’s Compensation AdjustmentAligning above-market owner salary and benefits to industry-standard compensation for a replacement manager+$150,000 to $500,000 add-backOwner paying themselves $600,000 when market rate for a general manager is $200,000
    Non-Recurring ExpensesOne-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition+$50,000 to $300,000 add-back$200,000 in legal fees from a one-time litigation matter
    Personal ExpensesPersonal travel, entertainment, vehicles, or family members on payroll not related to business operations+$25,000 to $150,000 add-backCompany-leased luxury vehicle used primarily for personal use
    Related-Party TransactionsAbove-market rent, management fees, or service charges paid to entities owned by the seller or their family+$75,000 to $400,000 add-backPaying $30,000/month rent to a seller-owned LLC when market rate is $15,000

    Boutique firms consistently deliver deep specialization and hands-on partner involvement, often completing a QoE engagement in as little as 2–4 weeks—roughly half the time of a Big Four engagement. Moreover, firms like Zaidwood Capital adhere to established capital markets best practices, incorporating frameworks from ICMA capital markets to ensure the analysis meets rigorous industry standards. This commitment to both speed and quality makes boutique advisors a compelling choice for mid-market acquirers.

    Scope and Cost Expectations for Mid-Market Companies

    For a $20M–$100M-revenue company, the scope of a Quality of Earnings engagement should be calibrated to deal complexity and the acquirer’s specific concerns. A one-size-fits-all report rarely adds value; instead, the engagement scope must be defined collaboratively, focusing on revenue recognition policies, working capital trends, customer concentration risks, and any carve-out adjustments that could affect normalized EBITDA. At Zaidwood Capital, we work directly with buyers to design a custom scope that addresses the unique drivers of the target business, avoiding unnecessary line items that inflate cost without improving decision-making.

    Cost expectations reflect the level of customization. Boutique firms like Zaidwood Capital typically quote $25,000–$50,000 for a $20M-revenue company, while Big Four firms can range from $75,000 to over $150,000 for a similar-sized engagement. Mid-tier regional firms generally fall between $40,000 and $80,000. All figures are custom quotes and depend on data availability, the number of entities involved, and the speed required. We emphasize that our pricing is never a fixed fee; each engagement is priced based on the precise scope and timeline agreed upon, with full-cycle support extending from the initial QoE analysis through deal close.

    Integrating QoE Findings into Deal Structuring

    A Quality of Earnings report is not just a diligence artifact—it directly shapes the final deal terms. When normalized EBITDA adjustments reveal that reported earnings overstate true recurring cash flow, buyers can negotiate purchase price reductions or post-closing true-ups. Earnout structures become more defensible when the QoE identifies revenue volatility or concentration risks that warrant contingent payments. Similarly, representation and warranty insurance underwriters increasingly rely on QoE findings to set coverage limits and exclusions, making a thorough report a valuable risk-transfer tool.

    At Zaidwood Capital, our full-cycle advisory model ensures that QoE insights flow seamlessly into the negotiation and documentation phases. We translate EBITDA adjustments into specific purchase price adjustment mechanisms, design earnout milestones linked to verifiable financial metrics, and help acquirers present the QoE to insurers to secure favorable underwriting terms. This integrated approach reduces re-trading risk and accelerates the path to a signed purchase agreement. Once you have selected the right partner, the next step is implementing a disciplined QoE process that turns financial analysis into concrete deal terms. As with any investment, past performance does not guarantee future results, and we recommend consulting professional advisors to tailor the approach to your deal.

    How Quality of Earnings Reports Influence Purchase Price and Deal Terms

    A quality of earnings report for mid-market deals does more than flag accounting irregularities; it serves as the core negotiating lever for adjusting the purchase price and crafting protective deal provisions. At Zaidwood Capital, we treat the QoE report as the definitive source for reconciling reported financials with normalized economic reality. This alignment is essential before we engage in price discussions.

    In our experience, the most direct impact of the QoE report is a purchase price adjustment derived from normalized EBITDA. When the report strips out non-recurring revenue or one-time expenses, it recalibrates the basis on which the acquisition multiple is applied. A lower sustainable EBITDA can reduce the implied valuation, prompting the buyer to seek a price reduction. Conversely, a seller whose earnings prove clean and recurring can leverage the report to sustain or elevate the offer. Beyond EBITDA, the working capital peg—determined by historical QoE trend analysis—can shift the final cash consideration. If the report reveals that the target’s normalized net working capital is lower than originally represented, the buyer rightfully demands a dollar-for-dollar reduction at closing. Sellers with positive QoE results often use this as a shield against overly burdensome indemnification clauses, while buyers rely on the analysis to insert additional covenants or expand representations and warranties when risks are evident.

    Earnout structures are another area where QoE findings carry substantial weight. We typically link earnout payments to forward-looking financial metrics that have been validated by the quality of earnings (QoE) review. This ensures that post-closing milestones are both achievable and reflective of the business’s true earning power, reducing disputes later. Likewise, indemnification horizons and escrow amounts are calibrated to the specific risks flagged in the report. A revenue recognition issue might extend the survival period for related claims and increase the escrow holdback, while a clean report shortens those protections. Underpinning this rigor are regulatory standards that shape our financial analysis. FINRA securities regulation, administered by the Financial Industry Regulatory Authority, sets expectations for broker-dealer reporting that influence how we assess earnings quality in private transactions. Similarly, SEC securities regulation, enforced by the U.S. Securities and Exchange Commission, mandates GAAP compliance and reinforces the importance of accurate data in all valuations. In the following section, we demonstrate how these adjustments play out in a real mid-market transaction.

    Common Questions About Quality of Earnings Reports in Mid-Market Deals

    After establishing the importance of a quality of earnings report for mid-market deals, we address the most common questions buyers and sellers ask before engaging a QoE provider.

    What is a quality of earnings report, and why is it essential for mid-market deals? A QoE analysis examines earnings sustainability and quality, revealing adjustments needed in private-company financials and uncovering risks like customer concentration.

    How does a QoE differ from standard due diligence, and what adjustments does it uncover? Unlike standard due diligence, a QoE report serves as a complementary tool—used by advisors like Zaidwood Capital—to examine normalized EBITDA, margin trends, and working capital, separating recurring from one-time items and revenue mix.

    How does a QoE report impact valuation and deal structure? By surfacing these insights, a QoE can bridge valuation gaps and influence purchase price multiples, giving both sides clearer grounds for negotiation.

    Next, we’ll walk through the practical steps of commissioning a QoE report for your mid-market transaction.

    Leveraging Quality of Earnings Reports for Smarter M&A Decisions

    A Quality of Earnings report for mid-market deals dissects financials to expose sustainable earnings by stripping out one-offs. It flags risks like premature revenue booking, strengthening your negotiation position. Mid-market firms with less polished reporting especially benefit. At Zaidwood Capital, a quality of earnings report for mid-market deals anchors our full-cycle due diligence, alongside operational, commercial, and IT assessments, to deliver a complete picture. Compliance with SEC securities regulation ensures data reliability, and leveraging QoE minimizes post-close shocks. Deeper insight drives smarter M&A decisions.

    Resources

  • Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Table of Contents

    Choosing Between Boutique and Bulge Bracket Investment Banking

    When weighing boutique vs bulge bracket investment banking, the core distinction lies in service scope and client intimacy. Specialist advisory firms offer focused, senior-led strategies that often result in faster execution and stronger alignment with client goals. Large global banks provide extensive capital markets access and resources suited for complex cross-border mandates. For companies considering private equity exit opportunities, boutique advisors frequently deliver customized positioning within their specific industry ecosystems. Similarly, talent dynamics around investment banking compensation packages reflect the differing demands of these models. We track SEC regulatory updates closely, as heavier compliance overhead affects larger institutions disproportionately while we leverage our full-cycle M&A and capital advisory approach to integrate deep advisory with proprietary data, streamlining transactions without the structural friction of multi-layered global firms.

    Ultimately, choosing between these paths depends on your transaction scope and strategic priorities. Our model bridges the gap by combining the personalized guidance of a boutique with the data-driven precision and investor network scale that growing companies require, a balance explored further in the next section.

    1. Senior Banker Attention and Personal Service

    In the boutique vs bulge bracket investment banking debate, one key differentiator is the level of senior attention you receive. At large, full-service firms, deal execution is often delegated to junior teams while managing directors appear only at critical milestones. We find this approach can dilute accountability and slow decision-making.

    Our model is fundamentally different. When you engage a boutique investment banking firm like Zaidwood Capital LLC, your mandate is led directly by our principals from pitch to close. As outlined in our description of M&A advisory services, senior bankers provide strategic guidance, valuation, negotiation support, and hands-on deal management throughout the entire lifecycle. This structure ensures decades of combined experience are applied to your specific strategic goals, delivering more tailored advice and faster execution.

    This personalized service is particularly valued by private equity firms seeking seamless exit execution and by companies requiring discreet, high-touch advisory. By leveraging our proprietary network and data resources, our senior team simplifies complex transactions, embodying our commitment to Streamlining Transactions with precision and focus.

    2. Tailored Fee Structures for Mid-Market Deals

    When considering boutique vs bulge bracket investment banking, the fee negotiation dynamics shift substantially for middle-market transactions. Unlike the rigid, standard pricing grids common at large institutions, we design our compensation around each mandate’s unique contours. This flexibility ensures your advisory costs reflect actual deal complexity rather than a one-size-fits-all schedule, aligning our incentives directly with your outcome.

    A typical framework might blend an initial retainer with a success-based component, or we may structure a milestone-driven fixed fee for a carve-out divestiture. The mix is always negotiated, absorbing variables like target size, cross-border diligence, and sector-specific resource requirements. For private equity firms managing portfolio company exits, this custom approach preserves more equity value while delivering institutional-quality execution. Our compensation benchmarks, detailed on our FAQ page, illustrate how tailored structures sit competitively within industry norms. As we always clarify, fees are custom-quoted and subject to mutual agreement rather than a published rate card.

    This disciplined yet adaptable approach removes friction from the engagement, letting you forecast costs with clarity. Next, we will walk through how our execution process turns that aligned structure into deal momentum.

    3. Specialized Industry Expertise

    Specialized industry expertise is a defining hallmark of the boutique model in investment banking. Unlike generalist institutions, boutique firms concentrate intellectual and relational capital into targeted verticals, cultivating an intimate understanding of sector dynamics, competitive landscapes, and value drivers. In private equity exit opportunities, this depth translates directly into superior deal sourcing because advisory teams speak the same operational language as founders, operators, and institutional buyers. Drawing from our own capital network exceeding $15 billion and an aggregate transaction volume surpassing $24.4 billion, we see consistent evidence that specialization sharpens valuation insight and accelerates execution.

    Sector-specific knowledge also shapes how boutique teams prepare portfolio companies for exit. Advisors often bring prior operating experience within the industries they serve, allowing them to anticipate buyer diligence questions and position assets around the metrics that matter most to private equity firms. When general partners evaluate acquisition targets, they rely on advisors who can interpret unit economics, regulatory nuances, and customer concentration risks without a learning curve, an advantage that industry depth systematically delivers.

    Industry depth shortens timelines and reduces transaction friction, qualities that matter acutely when fund lifecycles and market windows dictate exit timing. The structural alignment between boutique specialization and private equity mandates explains why sector-focused advisory teams continue gaining share in middle-market transactions. As the discussion shifts toward compensation structures, that same specialized expertise becomes a tangible factor influencing how transaction professionals are rewarded for execution.

    4. Agile Decision-Making and Speed

    Agile decision-making and speed represent some of the most compelling differentiators when evaluating boutique vs bulge bracket investment banking advisory services. At Zaidwood Capital, our lean, partner-led structure eliminates the multiple layers of approval and internal bureaucracy that typically slow down larger institutions. This streamlined architecture translates into faster, more decisive action for our clients.

    The role of an M&A advisor is inherently to accelerate deal timelines through proactive market intelligence and efficient coordination of due diligence. We execute this through our proprietary Velocity Matrix framework, which drives transaction velocity without compromising the depth or quality of our analysis. This systematic approach ensures that while we move quickly, we never sacrifice the financial, legal, and operational rigor that complex transactions demand.

    This responsiveness is particularly critical for owners pursuing private equity exit opportunities, where market windows can close rapidly and timing often correlates directly with value realization. Our direct partner involvement and efficient processes allow us to respond to these dynamics with the urgency they require. This structural speed also enables us to deliver a level of service intensity and personalization that more layered organizations find difficult to match.

    Agility here is not about cutting corners. It is the natural outcome of a flatter organizational design, empowered decision-makers, and a proprietary operating system purpose-built to optimize transaction timelines. This foundation of responsive execution supports the personalized and cost-effective approach that distinguishes true partnership in M&A advisory.

    5. Comprehensive Network Access and Deal Sourcing

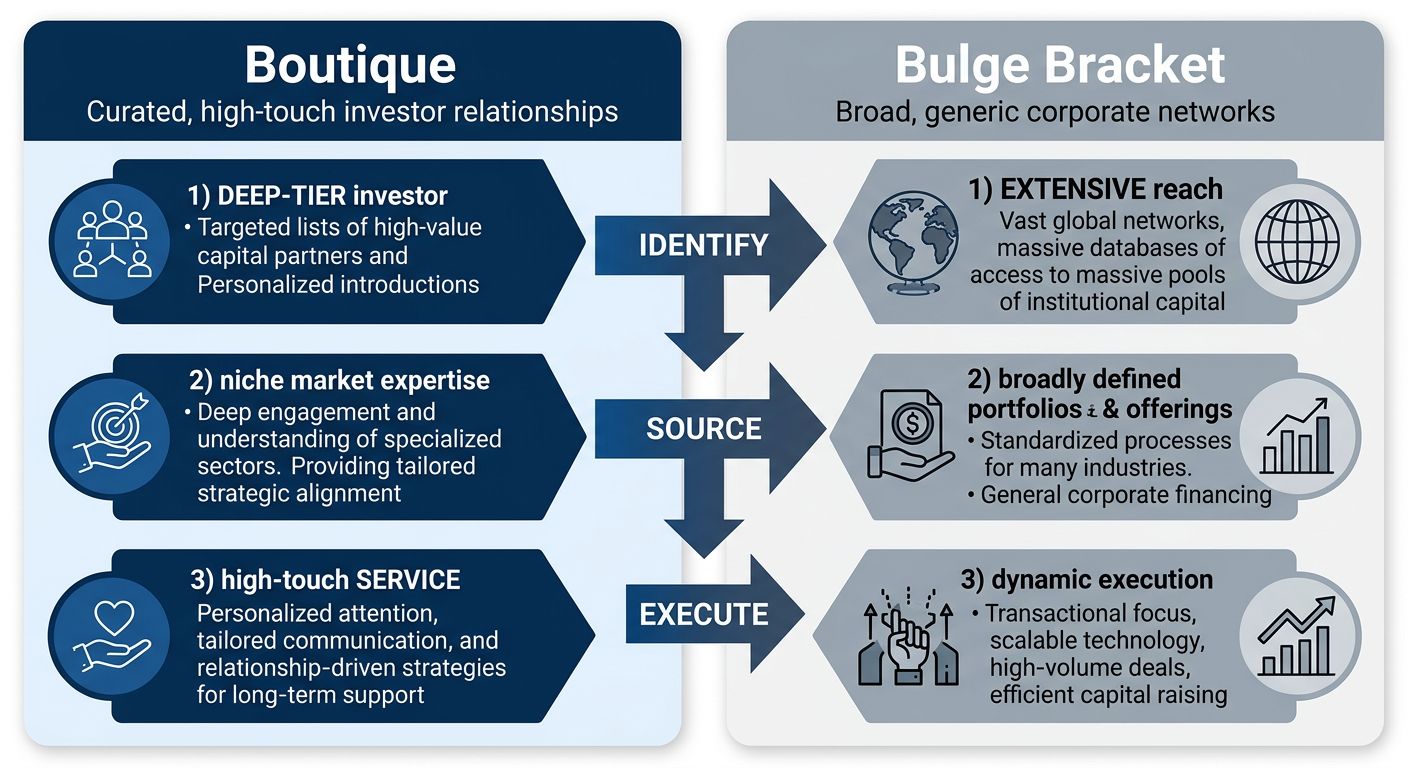
    Beyond our advisory capabilities, the real differentiator in the boutique vs bulge bracket investment banking landscape is the depth of our network. We connect clients with 4,000+ global investors and $15B+ in deployable capital, creating private equity exit opportunities that rival the largest institutions while maintaining the agility of a specialized boutique.

    Infographic comparing boutique M&A firm's high-touch investor network against bulge bracket's broad corporate network with deal sourcing funnel stages.
    Boutique vs. bulge bracket network access comparison at Zaidwood Capital.

    This integrated approach is powered by proprietary tools, including the Sovereign Data Nexus, Precision Catalyst, and Velocity Matrix, which sharpen deal sourcing and analysis. Our $24.4B+ aggregate transaction volume across full-cycle M&A, equity, and debt mandates confirms the scale we deliver. Exclusive access to Deal Vault and our curated Investor Rolodex further extends our partners’ reach. As our internal resources explain, these capabilities streamline the entire capital formation lifecycle, from LP placement and debt structuring to equity advisory.

    Whether you are evaluating private equity exit opportunities or structuring a capital raise, this institutional-grade infrastructure, delivered by a boutique firm, provides a clear advantage over traditional bulge bracket models. Our approach ensures you receive both the scale and the personalization that today’s complex deals demand. We’ll next explore how our fairness opinions and transaction advisory services add another layer of diligence.

    6. Cultural Alignment and Communication

    The choice in boutique vs bulge bracket investment banking extends beyond structure and into the softer, yet equally critical, dimensions of culture and communication. At Zaidwood Capital, we believe that a strong advisory relationship depends on transparency, trust and open dialogue — qualities that are built through consistent interaction rather than brand reputation alone. How a firm communicates directly shapes your experience during what is often the most consequential financial event in a company’s lifecycle.

    Communication style and responsiveness matter because M&A processes move quickly and demand real-time judgment. Boutique firms typically offer direct access to senior partners and a highly personalized cadence, while larger platforms operate through more structured teams and formalized reporting. Neither approach is inherently superior; the right fit depends on how you prefer to receive information, make decisions and manage pressure. Our internal resource on what M&A advisors do outlines how advisors facilitate fit assessments early in the process, helping clients evaluate both technical capability and interpersonal compatibility.

    Finding the right cultural fit also means considering how an advisor handles long-term strategic goals such as private equity exit opportunities or structuring investment banking compensation packages. These conversations require discretion, deep industry knowledge and a relationship grounded in mutual confidence. Full-Cycle M&A mandates succeed when the advisory team aligns with your organization’s values, communication norms and decision-making rhythm — a principle we prioritize through every phase of engagement.

    Streamlining Transactions depends as much on human chemistry as it does on financial engineering. In our experience, the most successful partnerships are those where both sides invest in candid, ongoing communication. The next section outlines practical steps you can take to evaluate and engage an advisor who fits your unique organizational culture.

    Making the Right Choice for Your M&A Needs

    Given the distinct advantages of each model, selecting the right advisor depends on your transaction size, industry focus, and desired level of partner attention. M&A advisors typically provide comprehensive support across buy-side and sell-side representation, valuation, due diligence, and deal negotiation. At Zaidwood Capital, we deliver Full-Cycle M&A and capital advisory that combines the personalized service of a boutique firm with access to over 4,000 institutional investors and $15B+ in deployable capital. Our approach ensures seamless execution from initial due diligence through final closing, backed by $24.4B+ in aggregate transaction volume. We encourage you to assess your specific requirements and book a call for tailored guidance on your M&A journey.

    Resources

  • Middle Market M&A Trends 2026: Expert Guide to Private Equity

    Middle Market M&A Trends 2026: Expert Guide to Private Equity

    Table of Contents

    The middle market M&A trends 2026 are reshaping the dealmaking environment through several interconnected forces:

    • Private credit unitranche financing is replacing traditional capital stacks, simplifying structures and reducing closing friction.
    • Record private equity dry powder is driving aggressive consolidation, particularly in mid-size sectors.
    • Proprietary data platforms, including Zaidwood Capital’s Velocity Matrix, are Streamlining Transactions by cutting due diligence timelines and widening buyer visibility.
    • Shifting interest rate expectations and regulatory scrutiny are compressing deal windows, elevating the importance of speed and precision.

    These dynamics are redefining the middle-market M&A landscape in 2026. According to Zaidwood Capital’s analysis of leading M&A advisors, firms that embed data-driven execution and full-cycle capabilities are winning mandates. Our own Full-Cycle M&A and capital advisory approach integrates these innovations, helping clients capitalize on these middle market deal trends before the window closes. The following section examines how leading advisory firms align with each of these forces.

    1. Rising Deal Volume and Momentum

    Middle market M&A trends 2026 point to a significant acceleration in deal volume as we move through the first half of the year. Across the U.S. middle market, transaction activity is building momentum driven by a convergence of favorable conditions that are reshaping how deals get done. The surge in deal volume has placed increased demand on M&A advisors who can navigate this increasingly complex landscape with precision.

    A primary catalyst is the expanded availability of private credit unitranche financing, which has become a preferred debt solution for sponsors and companies alike. By blending senior and subordinated debt into a single facility, unitranche structures streamline execution and provide certainty of close — a critical advantage in competitive processes. This financing innovation directly fuels the 2026 mid-market M&A momentum we are observing.

    At the same time, record levels of private equity dry powder deployment are intensifying competition for quality assets. With substantial uninvested capital waiting to be deployed, sponsors are under pressure to transact, driving valuations higher and accelerating timelines. According to Federal Reserve System data, the current interest rate environment — while still elevated relative to the prior decade — has provided enough stability for buyers and sellers to align on pricing expectations, removing a major impediment to deal activity.

    As deal momentum builds, the financing structures and institutional players driving these transactions warrant closer examination.

    2. Sector Spotlight: Where M&A Activity Is Concentrated

    Building on the broader M&A landscape, middle market M&A trends 2026 point to a clear concentration of activity across several key industries. Our analysis, informed by internal expertise in cyber security consulting and deal execution, identifies the technology sector as the undisputed leader. Demand for AI, cloud infrastructure, and heightened security needs are compelling companies to consolidate at a rapid pace.

    Beyond technology, we observe significant sector concentration in healthcare and life sciences, driven by an aging global demographic and an accelerating pace of innovation. The energy transition and cleantech sectors are also emerging as major M&A hot spots, fueled largely by governmental incentives and corporate sustainability commitments. This broad-based activity is being supercharged by private equity dry powder deployment, as sponsors actively seek platform investments in these favored niches.

    • Technology: Dominated by cybersecurity and AI-driven scalability.
    • Healthcare: M&A centered on biotech innovation and service consolidation.
    • Energy: Deal activity focused on renewables and grid infrastructure.

    Geographically, North America remains the epicenter for these transactions, though deal flow in Europe and select Asia-Pacific markets is rising. Understanding which sectors are active sets the stage for examining the top advisory firms driving these deals.

    3. Private Credit Unitranche Financing Reshaping the Landscape

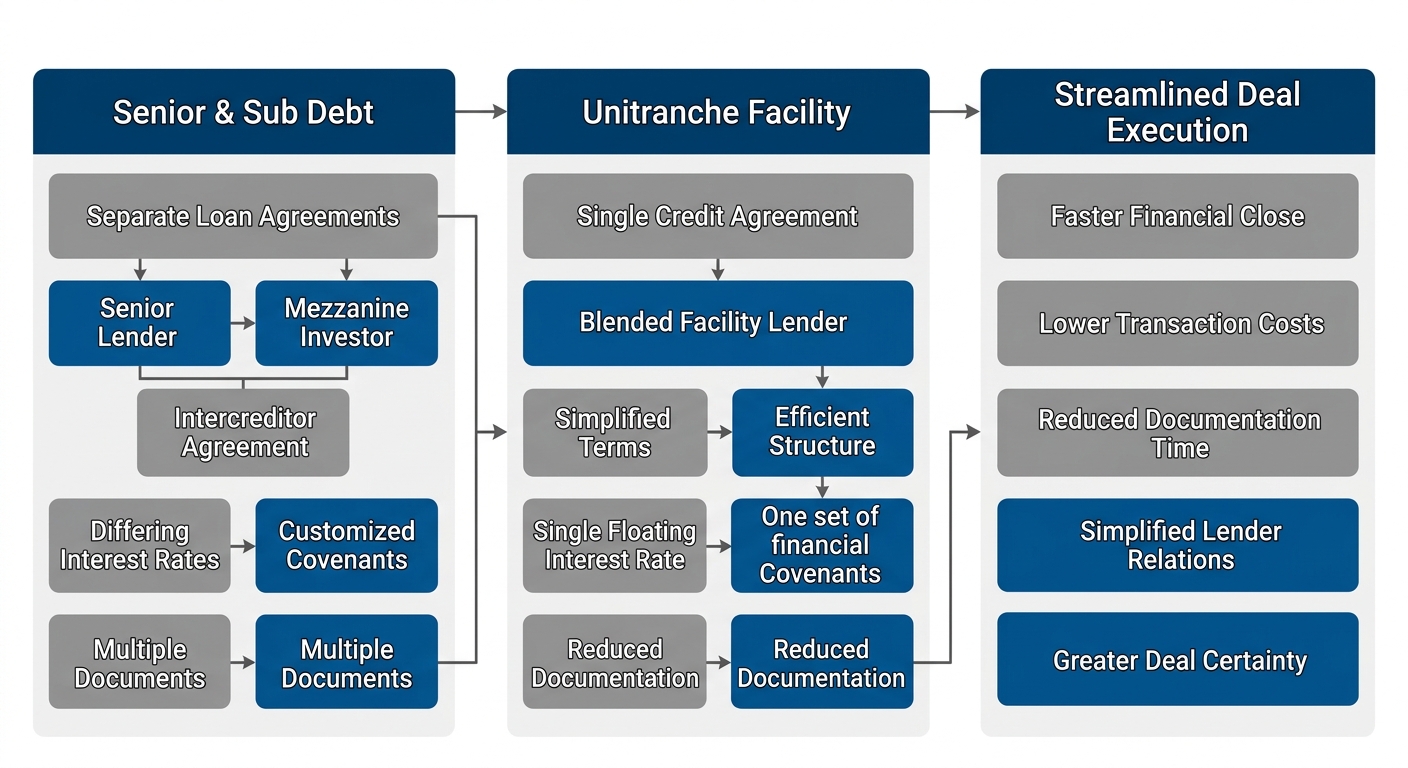
    Building on the broader M&A advisory trends, unitranche financing has emerged as a transformative force in middle-market deal execution. A single-tranche facility combines senior and subordinated debt into one combined debt instrument, offering both speed and simplicity for buyers and sellers navigating complex transactions.

    Leading advisory firms increasingly recommend unitranche structures, evidenced by the criteria Zaidwood Capital uses to identify top M&A advisors—transaction volume, network access, and specialized industry expertise. Our full-cycle M&A and capital advisory approach connects clients with over 4,000 institutional investors, streamlining transactions through proprietary frameworks like the Velocity Matrix.

    These unitranche structures align with capital market standards established by the International Capital Market Association (ICMA), ensuring documentation practices meet global benchmarks for transparency. This alignment with Financial Services 3.0 principles reduces the need for separate capital layers, accelerating close times significantly.

    For middle market m&a trends 2026, private credit unitranche financing enables more leveraged buyouts and growth equity transactions. Our Sovereign Data Nexus and Precision Catalyst methodology provide the execution speed modern dealmakers require.

    Horizontal process-flow diagram with three connected boxes labeled Senior & Sub Debt, Unitranche Facility, and Streamlined Deal Execution, using blue and gray colors.

    Illustration of unitranche financing mechanics combining senior and subordinated debt into a single facility.

    Through our extensive investor network and disciplined deal structuring, we facilitate unitranche transactions that deliver certainty and efficiency—foreshadowing how these financing innovations directly influence deal execution strategies in the sections ahead.

    4. Interest Rates and Their Impact on Deal Financing

    In middle market M&A trends 2026, interest rate impact remains a decisive variable shaping deal financing strategies. The federal reserve system has set the fed funds target range at 3.50% to 3.75%, directly influencing the cost of senior debt, mezzanine financing and unitranche financing structures. When rates rise, borrowing costs climb and private equity firms often adjust by lowering leverage ratios and increasing equity contributions to maintain acceptable returns.

    We observe that private credit unitranche financing has gained prominence in the current higher-rate environment as borrowers seek alternatives to traditional bank debt. This single-tranche solution simplifies capital structures and can provide covenant flexibility that syndicated loans lack.

    The rate environment also drives sponsor behavior. Common adjustments we see include:

    • Prudent leverage reduction to offset higher interest expense
    • Greater equity checks to de-risk capital structures
    • Increased use of floating-to-fixed rate swaps

    Top M&A advisory firms—including Goldman Sachs, Morgan Stanley and Houlihan Lokey—help clients structure financing to mitigate rate risk. At Zaidwood Capital, we provide Full-Cycle M&A and capital advisory, supporting clients with debt and equity advisory to navigate rate volatility while preserving deal momentum.

    With rates redefining cost of capital, the next section examines specific financing structures—such as unitranche debt and equity solutions—that can optimize outcomes in this dynamic environment.

    5. Valuation Multiples and the Dry Powder Effect

    In the landscape of middle market M&A trends 2026, understanding valuation multiples is essential for buyers and sellers alike. A valuation multiple — often expressed as an EBITDA multiple — represents the ratio of a company’s enterprise value to its earnings before interest, taxes, depreciation, and amortization, serving as a standardized metric for comparing deal pricing across transactions. In the middle market, these multiples typically range based on company size, sector dynamics, and growth trajectory, with premium valuations reserved for businesses demonstrating scalable operations and defensible market positions. As we observe current 2026 middle market deal trends, the interplay between abundant capital and limited quality assets continues to reshape pricing expectations.

    The dry powder effect — the accumulation of uninvested private equity dry powder capital — has become one of the most significant forces driving valuation multiples upward heading into 2026. Record levels of dry powder reported through 2024-2025, estimated in the trillions globally, have intensified competition for quality middle market assets as fund managers face deployment deadlines. This oversupply of capital chasing a finite pool of attractive acquisition targets creates natural upward pressure on purchase multiples, a dynamic that aligns with the broader mid-market M&A outlook for sustained elevated pricing. Buyers armed with significant dry powder are increasingly willing to stretch valuation parameters to secure platform investments and add-on acquisitions that strengthen their portfolio strategies.

    Supporting this high-multiple environment, private credit unitranche financing has emerged as a critical enabler for acquirers looking to bridge valuation gaps. Unitranche structures combine senior and subordinated debt into a single facility, streamlining execution and reducing refinancing risk — key advantages when aggressive bidding pushes enterprise values beyond what traditional senior lenders are willing to support. This financing flexibility allows buyers to compete effectively in auctions and negotiate with confidence, reinforcing the competitive bidding dynamics that characterize today’s middle market. Sectors such as technology, healthcare, and business services have seen particularly pronounced multiple expansion, though the degree of premium varies significantly by industry and company size.

    Navigating this high-multiple, high-competition environment demands sophisticated advisory support. Our comparative analysis of the best M&A advisors for 2026 highlights firms with the sector expertise and transaction experience necessary to maximize outcomes under these conditions. Similarly, our overview of top M&A advisory firms identifies the capabilities clients need when facing competitive processes influenced by significant dry powder deployment. At Zaidwood Capital, we bring full-cycle M&A and capital advisory expertise to every engagement, leveraging our access to over 4,000 institutional investors and deep transaction experience to help clients achieve optimal results in an increasingly complex market.

    6. Private Equity Dry Powder: The Urgency to Deploy

    In examining current middle market M&A trends 2026, one fundamental driver stands apart: private equity dry powder. This term describes the massive pool of committed capital that private equity firms have raised from limited partners but have not yet invested. As these unallocated reserves reach historically high levels, fund managers face an intensifying race against predefined investment periods. Capital that sits idle beyond its mandated deployment window risks being returned to investors, creating a structural urgency that directly fuels acquisition activity across the middle market.

    We see how this private equity dry powder deployment timeline pushes sponsors toward decisive action. Competing funds vie for quality assets before investment horizons expire, compressing due diligence cycles and elevating the importance of accelerated execution. In this environment, private credit unitranche financing has emerged as an alternative capital tool that can streamline deal timelines by combining senior and subordinated debt into a single facility. Navigating this accelerated deal landscape demands precision, and our resources on top M&A advisory firms provide guidance for those seeking expertise in Full-Cycle M&A execution. This urgency to deploy makes an experienced advisor less of a luxury and more of a competitive necessity.

    7. Regulatory Shifts and Macroeconomic Considerations

    Understanding middle market M&A trends 2026 requires examining the evolving regulatory and economic landscape that directly shapes financing dynamics. The U.S. Securities and Exchange Commission continues to refine disclosure requirements and rulemaking agendas—including recent proposals to rescind certain Regulation NMS Rules—while providing essential SEC investor tools that help market participants stay informed about compliance obligations affecting transaction structures.

    The Board of Governors of the Federal Reserve System maintained a Fed Funds Target Range of 3.50% to 3.75% as of mid-2026, with PCE inflation at 3.8% and GDP growth at 1.6% in Q1, according to official data. This rate environment sustains elevated financing costs for leveraged transactions while simultaneously fueling demand for private credit unitranche financing as sponsors seek flexible alternatives to traditional bank lending. The persistence of approximately $1.5 trillion in private equity dry powder deployment pressure continues driving middle-market deal activity despite macroeconomic headwinds, creating a complex environment where regulatory fragmentation across state and federal jurisdictions demands sophisticated advisory capabilities.

    At Zaidwood Capital, our Full-Cycle M&A and capital advisory approach helps clients navigate these intersecting forces—translating regulatory complexity and monetary policy signals into actionable transaction strategies without making assumptions about guaranteed outcomes.

    8. Operational Due Diligence and Full-Cycle Advisory Imperative

    As middle market m&a trends 2026 accelerate transaction timelines, operational due diligence has emerged as a decisive factor beyond traditional financial review. This discipline assesses a target’s operations, supply chain resilience, IT infrastructure, and human capital — areas where fragmented advisory can create blind spots. When legal, financial, and operational workstreams operate in silos, inefficiencies multiply, particularly as competition intensifies.

    Rising private credit unitranche financing demands deeper operational underwriting from lenders, who now scrutinize continuity and integration readiness as closely as debt-servicing capacity. Concurrently, record private equity dry powder deployment forces buyers to differentiate through execution certainty rather than price alone. A robust operational due diligence framework becomes the differentiator.

    We address these pressures through full-cycle advisory, a model that unifies pre-deal strategy, execution, and post-merger integration under a single, coordinated process. By leveraging proprietary tools like the Velocity Matrix, we streamline transactions without compromising rigor — a necessity in the middle market today. This integrated approach sets the stage for the execution frameworks we detail next.

    Capitalizing on 2026 M&A Opportunities

    The middle market m&a trends 2026 point to a landscape ripe with transaction potential driven by structural shifts in financing and capital availability. Private equity dry powder continues to accumulate, creating urgency among sponsors to deploy capital into disciplined acquisition strategies. Simultaneously, private credit unitranche financing has matured as a flexible, single-tranche solution that simplifies deal execution and accelerates closing timelines for mid-sized transactions.

    These tailwinds do not guarantee outcomes—deal success depends on precision in execution. Drawing on insights from our internal FAQ on what makes a top M&A advisory firm, we believe the firms that capture these opportunities will be those with full-cycle capabilities, deep institutional networks, and sector-specific expertise. As middle market m&a trends 2026 intensify competition for quality assets, our team at Zaidwood Capital brings together capital advisory, due diligence rigor, and access to a global investor base to help clients move from analysis to action without crossing into broker-dealer services.

    Resources

  • Due Diligence Explained: Financial and Commercial Guide

    Due Diligence Explained: Financial and Commercial Guide

    Table of Contents

    Mastering Due Diligence in Mergers and Acquisitions

    Building on Streamlining Transactions in mergers and acquisitions, due diligence is the comprehensive investigation verifying a target company’s viability. It plays a pivotal role in risk mitigation and value confirmation, ensuring informed decisions throughout the deal process.

    Financial due diligence involves scrutinizing historical financials, cash flow projections, debt obligations, and working capital adequacy. We leverage proprietary tools to deliver precise insights that uncover hidden liabilities and opportunities.

    Commercial due diligence validates market size, competitive positioning, customer retention rates, and revenue sustainability through rigorous industry benchmarking. Our full-cycle approach integrates financial, legal, operational, IT, and human capital reviews using the Velocity Matrix for accelerated execution and Precision Catalyst methodologies.

    This mastery enables informed negotiations, minimizes post-deal surprises, and facilitates seamless integration into our Full-Cycle M&A and capital advisory services. Book A Call today for tailored support.

    Preparing for Your Due Diligence Process

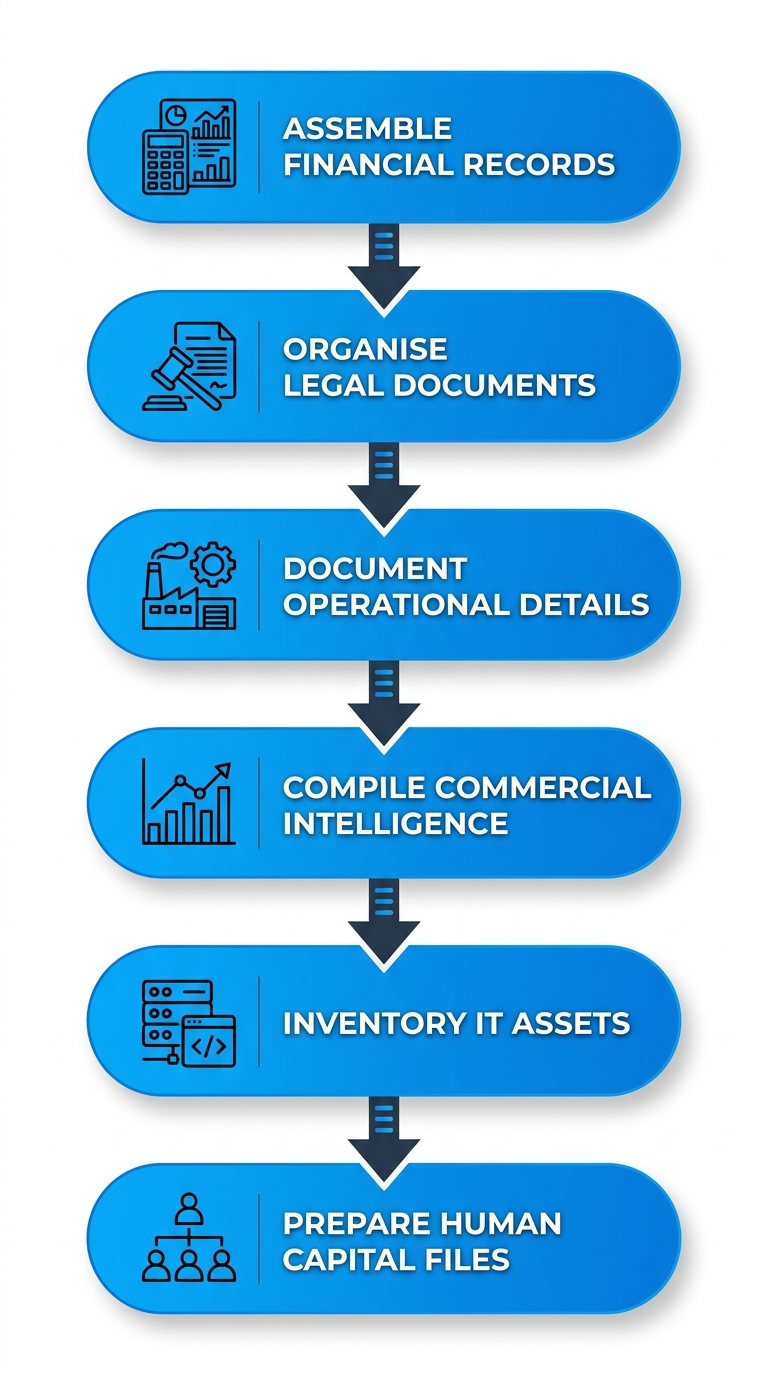
    Building on our overview of due diligence, we recommend proactive preparation to ensure smooth Full-Cycle Due Diligence across financial, legal, operational, commercial, IT, and human capital aspects. This Streamlining Transactions approach positions your M&A or capital deal for efficiency and success.

    Vertical process flow diagram illustrating six key steps for preparing M&A due diligence: assembling financial records, organizing legal documents, documenting operations, compiling intelligence, inventorying IT assets, and preparing HR files.

    Six-step vertical flowchart for efficient M&A due diligence preparation

    Key preparation steps include:

    • Assemble complete financial records, including audited statements, tax returns, cash flow projections, and debt schedules for the past three years to support financial due diligence.
    • Organize legal documents such as incorporation papers, shareholder agreements, litigation files, and material contracts.
    • Document operational details like supply chain mappings, key KPIs, inventory ledgers, and facility leases.
    • Compile commercial intelligence, including customer concentration analyses, market reports, sales pipelines, and benchmarking for commercial due diligence.
    • Inventory IT assets with software licenses, cybersecurity protocols, data backups, and architecture diagrams.
    • Prepare human capital files covering org charts, employee contracts, compensation benchmarks, and retention plans.
    • Create a secure data room indexed by category with access logs and assign point persons per diligence category.

    Contact us via Book A Call to initiate your tailored process. This is informational only; consult advisors. Past performance does not guarantee future results.

    Planning and Kickoff Phase

    Building on our Full-Cycle M&A and capital advisory process, the Planning and Kickoff Phase serves as the critical starting point. Here, we collaborate closely with clients to define transaction goals, timelines, and success metrics within 1-2 weeks, incorporating due diligence scoping powered by our Velocity Matrix for streamlined execution.

    We initiate kickoff activities with a structured onboarding call to align objectives. Our team then executes NDAs, sets up the secure Deal Vault data room, and conducts an initial diagnostic review of financials and market position to identify key priorities.

    Planning emphasizes full-cycle due diligence, prioritizing financial due diligence such as pro forma financials review and commercial due diligence including market validation and competitive analysis.

    Using our Precision Catalyst approach, we customize scope leveraging our 4,000+ investor network. With planning complete, we advance to the Due Diligence Execution Phase, ensuring efficient transactions through proprietary data access.

    Financial Analysis Review

    Within our full-cycle due diligence as part of Full-Cycle M&A and capital advisory services, our financial analysis review ensures transaction integrity by rigorously evaluating financial statements, projections, and risks. This due diligence evaluation provides the quantitative backbone for informed decisions in mergers and acquisitions.

    We begin our financial review process with targeted steps:

    • Examining historical financials for revenue trends and cost structures.
    • Validating pro forma projections against market benchmarks.
    • Assessing working capital efficiency and debt sustainability through key ratios like EBITDA margins and cash conversion cycles.

    Our financial due diligence leverages proprietary data access via the Velocity Matrix for faster insights, drawing from $24.4B+ in transaction experience. This pairs with commercial due diligence for holistic risk assessment.

    Book A Call for a custom financial review in your deal. Not investment advice — consult advisors; investments involve risk.

    Complementing financial due diligence, our legal document examination uncovers hidden liabilities in Full-Cycle M&A and capital advisory services. As a vital part of comprehensive due diligence, we scrutinize key documents to mitigate risks, drawing on our access to 4,000+ global investors and $24.4B+ transaction volume.

    Shareholder Agreements: Review control provisions for ownership disputes.

    Material Contracts: Analyze termination clauses for exit risks.

    Litigation Records: Identify pending disputes.

    IP Assignments: Verify ownership clarity.

    Regulatory Filings: Assess compliance history.

    1. Cross-verify authenticity via proprietary Deal Vault access.
    2. Flag non-compete issues in employment contracts.
    3. Coordinate findings with financial due diligence teams for liability impacts.

    This integrates with commercial due diligence for a holistic view, Streamlining Transactions through the Velocity Matrix. Our process reduces execution friction and aligns legal, financial, and commercial teams. Not investment advice—consult advisors. Book A Call today.

    Commercial Market Assessment

    Within our full-cycle due diligence, commercial market assessment builds on financial analysis by analyzing target market size, trends, customer demand, competitive positioning, and entry barriers. This commercial due diligence ensures informed decisions in Full-Cycle M&A and capital advisory.

    We conduct primary research through our institutional network of 4,000+ global investors. Our team reviews proprietary data via Velocity Matrix for market velocity, assesses go-to-market strategies, and benchmarks peers using Precision Catalyst tools. This commercial evaluation pairs with financial due diligence to deliver holistic insights, avoiding siloed analysis while Streamlining Transactions.

    Key benefits include spotting risks in buyer-seller dynamics and unlocking value through Sovereign Data Nexus access. This market lens informs our broader evaluation phases, ensuring comprehensive support.

    Book A Call today for a custom assessment, backed by our $24.4B+ transaction volume expertise.

    This is informational only; consult advisors. Not investment advice. Securities via Finalis Securities LLC; we are not a broker-dealer.

    Operational Efficiency Evaluation

    Building on financial due diligence, our operational efficiency evaluation examines execution capabilities in Full-Cycle M&A and capital advisory transactions. We analyze production processes, supply chain logistics, workforce productivity metrics like output per employee hour, and cost-to-revenue ratios to identify bottlenecks and improvement opportunities.

    Our step-by-step process includes: (1) conducting on-site facility walkthroughs and data room reviews for operational KPIs; (2) benchmarking against peers using anonymized industry data from our $24.4B+ transaction database; (3) modeling post-transaction efficiency gains via scenario analysis integrated with our Velocity Matrix for Streamlining Transactions.

    We integrate operational insights with financial due diligence by quantifying capex savings and with commercial due diligence by validating revenue sustainability through throughput validations. These insights complement commercial due diligence revenue projections.

    We deliver customized reports with 15-25% typical efficiency uplift recommendations. Book A Call for implementation quotes and scheduling.

    IT and Human Capital Review

    Building on financial due diligence and commercial due diligence, our IT and human capital review forms a core component of Full-Cycle M&A and capital advisory services. We assess technology infrastructure, cybersecurity, data systems, workforce talent, and organizational structure to identify risks and opportunities, streamlining transactions as a Precision Catalyst.

    In IT review, we evaluate software scalability, cloud migration readiness, API integrations, and cybersecurity frameworks like zero-trust architecture. Our human capital review includes skills gap analysis via competency matrices, employee turnover metrics from HR data, executive succession planning charts, and cultural alignment scoring.

    These findings integrate with financial due diligence and commercial due diligence phases to produce a unified risk profile report. Our proprietary Velocity Matrix accelerates IT audits and talent assessments using institutional network insights.

    These insights directly inform our transaction advisory and fairness opinions. Book A Call to discuss custom due diligence scopes.

    This is informational only, not investment advice—consult advisors. Securities via Finalis Securities LLC; Zaidwood not a broker-dealer.

    Synthesis and Reporting

    Building on these analyses from commercial due diligence and other phases, our synthesis and reporting phase completes the full-cycle due diligence process. We integrate key insights into unified, actionable reports that empower informed M&A decisions within our Full-Cycle M&A and capital advisory services.

    Our team synthesizes data from financial due diligence alongside commercial due diligence. Using the Velocity Matrix, we streamline the reporting process to produce:

    • Executive summaries and risk matrices highlighting critical findings;
    • Recommendation sections with clear, prioritized actions;
    • Tailored deliverables like comprehensive due diligence reports, fairness opinion inputs, and strategic briefs for buy-side or sell-side clients.

    The Precision Catalyst approach ensures these reports accelerate transaction velocity while mitigating identified risks across all phases. These reports inform our full-cycle M&A advisory and next steps. Book A Call to explore custom due diligence synthesis for your needs.

    Overcoming Common Due Diligence Challenges

    While due diligence is critical in M&A transactions, common pitfalls like incomplete data rooms, regulatory complexities, and integration risks often derail deals. At Zaidwood Capital, our Full-Cycle M&A and capital advisory services provide a comprehensive solution through our Streamlining Transactions approach. We help clients anticipate and mitigate risks early in deals.

    Delays in financial due diligence frequently arise from scattered financial data across multiple sources. We overcome this by conducting thorough financial due diligence using proprietary data access and private servers via our Velocity Matrix, accelerating verification and ensuring accuracy without compromising security. Our teams normalize inputs, prioritize material items, and shorten review cycles to reduce rework.

    Gaps in commercial due diligence often stem from market misalignments that undermine deal viability. Our methodology integrates commercial due diligence with strategic financial consulting, validating market potential and aligning opportunities with client objectives for informed decision-making. We pair market sizing with customer segmentation and competitor analysis for realistic forecasts.

    Operational and IT due diligence oversights can lead to costly post-deal surprises. We address these through full-cycle due diligence encompassing operational, IT, and human capital aspects, leveraging Precision Catalyst tools to identify risks early and facilitate seamless integration. Cross-functional teams build integration playbooks to accelerate day-one readiness effectively.

    With over $24.4B in aggregate transaction volume and access to 4,000+ global investors, we deliver proven expertise. Book A Call today for tailored support on your next transaction.

    Achieving M&A Success Through Thorough Due Diligence

    Building on common M&A transaction risks, thorough due diligence stands as the Precision Catalyst for success. Studies indicate 70-90% of deals fail due to inadequate processes, underscoring the need to identify risks and opportunities early in our Full-Cycle M&A and capital advisory at Zaidwood Capital.

    Financial due diligence involves scrutinizing historical financials, normalizing EBITDA, projecting future cash flows, and detecting off-balance-sheet liabilities to ensure fiscal accuracy.

    Commercial due diligence validates market size, assesses customer concentration risks, evaluates competitive positioning, and confirms revenue sustainability using our proprietary Velocity Matrix tools.

    Our full-cycle approach extends to legal, operational, IT, and human capital due diligence, Streamlining Transactions while mitigating post-deal surprises. With access to our 4,000+ investor network and $24.4B+ transaction volume, we drive integrated advisory outcomes. Past performance does not guarantee future results.

    Book A Call for tailored due diligence support.

    This article was researched and written with the assistance of AI tools.

    Resources and Insights

  • Harris and Partners Alternatives: Top Boutique Banks for M&A

    Harris and Partners Alternatives: Top Boutique Banks for M&A

    Table of Contents

    In the dynamic landscape of middle market M&A, where transactions typically range from $10 million to $500 million, companies seek agile partners to navigate complex deals. Firms like harris and partners exemplify how boutique investment banks provide tailored advisory in this space, focusing on niche sectors and personalized service. At Zaidwood Capital, we specialize in streamlining these transactions for private equity firms, family offices, and businesses with revenues exceeding $1 million.

    Middle market M&A involves mergers, acquisitions, and strategic partnerships that drive growth for mid-sized enterprises. Boutique investment banks, or specialized M&A advisors, differ from larger institutions by offering focused expertise and faster execution without bureaucratic delays. Niche investment firms like ours emphasize relationship-driven approaches to ensure seamless outcomes.

    We at Zaidwood Capital bring unmatched credentials, with an aggregate transaction volume of $24.4 billion across more than 300 completed deals. Our full-cycle M&A advisory services encompass due diligence in financial, legal, and operational areas, alongside capital introductions to our network of over 4,000 institutional and private investors and access to $15 billion in deployable capital. Through Zaidwood Capital Services, we integrate digital marketing and capital markets savvy for efficient buy-side and sell-side mandates.

    This guide explores fundamentals of boutique banking, advanced strategies, and best practices. We transition next to core principles, equipping you to leverage opportunities in this evolving market.

    Core Principles of Middle Market M&A Advisory

    Middle market mergers and acquisitions represent a dynamic segment of the financial landscape, focusing on companies with annual revenues between $10 million and $500 million. These transactions often involve complex negotiations tailored to the unique needs of growing businesses, where boutique M&A advisory firms play a pivotal role. Our team at Zaidwood Capital specializes in guiding clients through these processes, leveraging our extensive experience to ensure seamless execution.

    At the core of middle market M&A are key deal structures, including asset purchases, stock acquisitions, and mergers of equals. Buy-side processes involve identifying targets, conducting initial valuations, and negotiating terms, while sell-side engagements focus on preparing confidential information memorandums and soliciting bids. Due diligence forms the backbone of these transactions, encompassing financial audits to verify revenue streams, legal reviews for compliance and liabilities, and operational assessments of supply chains and management teams.

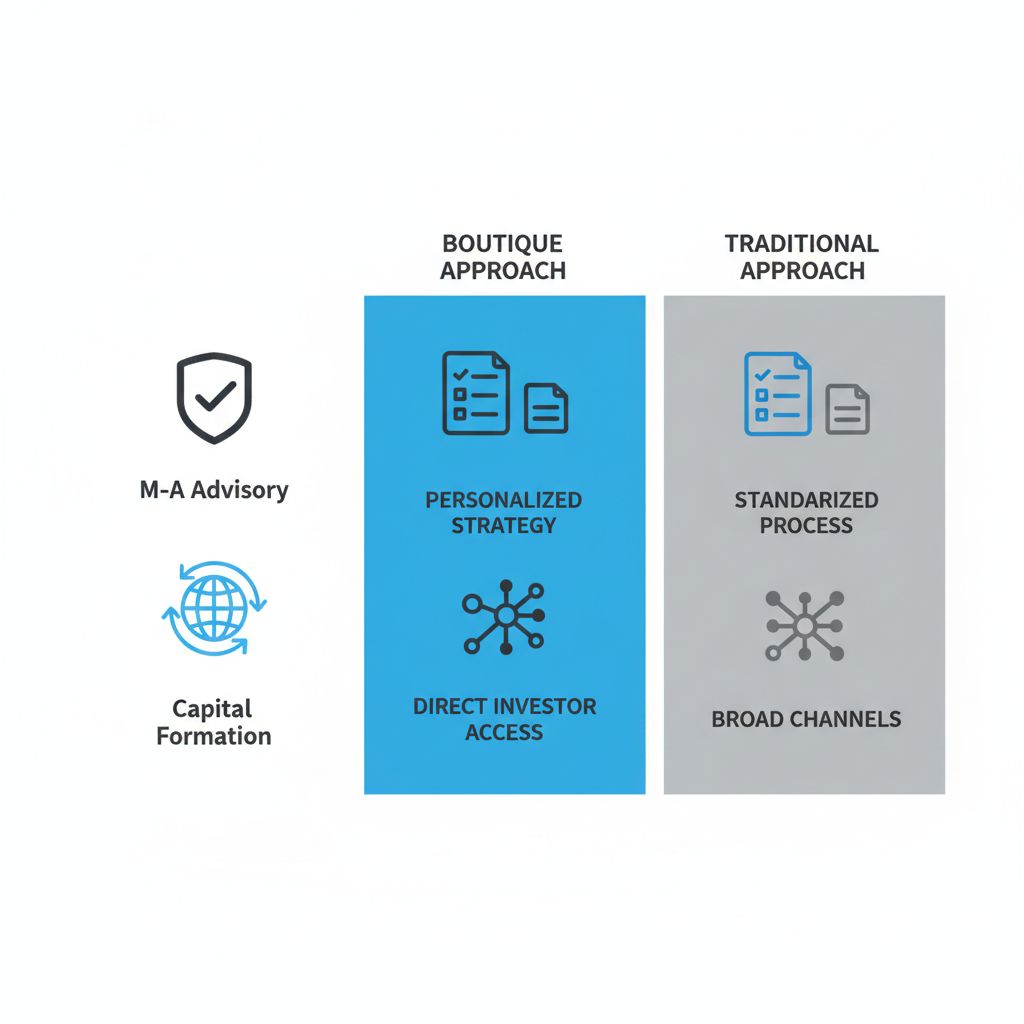
    Boutique vs Traditional Banks: Key Service Differences

    Service AreaBoutique Approach (e.g., Zaidwood)Traditional Bank Approach
    M&A AdvisoryTailored buy/sell-side with full due diligence (300+ deals experience)Broad mandates with standardized processes
    Capital FormationDirect access to 4,000+ investors via Velocity MatrixLimited network introductions

    Building on these differences, boutique firms excel in integrating capital raising with advisory services. This holistic approach not only streamlines transactions but also enhances strategic positioning in competitive markets.

    Infographic comparing boutique versus traditional bank approaches in middle market M&A advisory services

    Boutique vs traditional M&A advisory comparison for middle market

    In-Depth Analysis of Capital Formation Strategies

    Equity and Debt Advisory Essentials

    We structure mezzanine debt as a hybrid financing tool, positioned between senior debt and equity to provide flexible capital for expansion. This subordinated option offers businesses higher leverage while minimizing ownership loss, ideal for firms scaling operations post-acquisition. Venture debt complements this by extending cash runways for early-stage companies, often without warrants that dilute equity.

    Financing TypeZaidwood CapabilitiesTypical Harris-Style Firm
    Debt AdvisoryMezzanine, asset-based with $15B networkLimited to basic loans
    Equity AdvisoryGrowth equity introductions to 4,000+ investorsStandard placements

    Due Diligence in Boutique Deals

    Our full-cycle due diligence process is a cornerstone of successful boutique deals, encompassing financial, operational, and legal reviews to identify synergies and red flags early. We begin with financial modeling, scrutinizing pro forma statements and cash flow projections to validate deal viability. Legal reviews follow, examine contracts, IP rights, and regulatory compliance. In specialized financing firms, we extend this to emerging markets M&A, where geopolitical factors demand rigorous scrutiny.

    Implementing M&A and Capital Strategies in Practice

    Step-by-Step Deal Execution Guide

    • Investor Matching: Drawing from our network of over 4,000 institutions and $15B in deployable capital, we curate tailored introductions.
    • Due Diligence Execution: We conduct full-cycle reviews, encompassing financial audits, legal compliance checks, and operational evaluations using SEC regulatory resources.
    • Documentation Preparation: Clients receive customized pitch decks, pro forma financials, business plans, and fairness opinions.
    Tool/AspectZaidwood OfferingStandard Boutique
    Investor Network4,000+ institutions, $15B capitalSmaller, regional focus
    DocumentationPitch decks, pro formas via Deal VaultBasic templates

    Case Studies in Middle Market Success

    Through rolodex-driven introductions to family offices and venture capital sources, we structured a hybrid mezzanine debt facility for a manufacturing firm that bridged senior loans and equity, minimizing dilution. In another case, we developed a compelling narrative around intellectual property for a tech firm, utilizing investor outreach to sovereign wealth funds and endowments for competitive bidding.

    Advanced Topics in Boutique Debt and Equity Advisory

    Advanced due diligence forms the backbone of our process, encompassing human capital assessments to evaluate team dynamics and commercial viability to scrutinize market positioning. Capital introductions represent a cornerstone of our elite advisory networks, connecting clients to sovereign wealth funds and endowments. profissionais who cultivate deep relationships with private equity sponsors position themselves for success. Our investment bankers 2025 insights validate this strategy.

    Advanced FeatureZaidwood StrengthBoutique Baseline
    Investor Access$15B deployable via 4,000+ connectionsLimited introductions

    Common Questions on Boutique M&A Services

    • How do I select a boutique investment bank? Evaluate track records and sector focus. At Zaidwood Capital, our $24.4B transaction volume provides proven expertise.
    • Timeline for due diligence? Usually 4-8 weeks, covering financial, legal, and operational reviews.
    • Regulatory considerations? Utilize FINRA regulatory tools for filings and disclosures.

    Leveraging Boutique Expertise for Your M&A Success

    In navigating middle market M&A, boutique investment banks offer tailored strategies that drive efficient transactions. At Zaidwood Capital, we provide full-cycle advisory, from due diligence to capital formation, empowering clients with innovative tools like our Velocity Matrix for rapid execution. contact us today to explore how our expertise can support your success.

    Resources