Tag: Corporate Finance

  • Commercial and Industrial Loans: Complete Guide for Businesses

    Table of Contents

    Understanding Commercial and Industrial Loans

    Commercial and industrial loans — commonly referred to as C&I loans — are short-to-medium-term financing solutions designed to fund a company’s daily operations, working capital needs, or capital expenditures. These instruments form a core part of corporate debt financing, and businesses can access them on either a secured or unsecured basis.

    In practice, companies qualify for C&I loans through one of two primary frameworks: asset-based lending or cash flow financing. Asset-based lending centers on the quality of a borrower’s collateral, such as inventory, equipment, or accounts receivable. Cash flow financing, by contrast, emphasizes the strength of historical and projected revenue streams.

    According to Zaidwood Capital’s own advisory resources, institutional investors evaluate applicants using additional metrics — including a detailed business plan, audited financial statements, and multi-year cash flow projections — before matching a company with an appropriate lender. While banks have long dominated this space, a growing pool of institutional investors now provides business loans for commercial purposes, offering a viable alternative for mid-market and growth-stage firms.

    Zaidwood Capital’s Debt Advisory practice helps businesses navigate these two qualification models, acting as a bridge to institutional capital sources. Through its platform, Zaidwood Capital provides global lending services that connect companies with the right C&I lending partners, ensuring a structured and transparent path to financing.

    Commercial and Industrial Loans vs. Other Financing Options

    While the previous section outlined what C&I loans are, this section helps you distinguish them from other common financing products. Understanding the distinctions between commercial and industrial loans, commercial real estate loans, and equipment financing is essential for any business owner evaluating the right capital structure. Each product is designed to meet fundamentally different business needs, from funding day-to-day operations to acquiring major assets. At Zaidwood Capital, we help clients navigate this landscape, leveraging our advisory expertise and access to over 4,000 institutional investors to secure the right financing for their unique situation.

    C&I Loans vs. CRE vs. Equipment Financing
    FeatureCommercial & Industrial LoansCommercial Real Estate LoansEquipment Financing
    Primary Use CaseWorking capital, inventory, operational expensesAcquiring, developing, or refinancing real propertyPurchasing machinery, vehicles, or technology
    Collateral TypeReceivables, inventory, equipmentReal estate asset being financedEquipment being acquired
    Repayment TermShort to medium term (1–5 years)Long term (10–30 years)Medium term (3–10 years)
    Interest Rate TypeFixed or floating, tied to working capital cyclesFixed or floating, typically lower spreadsFixed or floating, often with equipment retention clauses

    The primary use case immediately highlights the distinct purpose for each loan. Commercial and industrial loans are the go-to solution for fueling organic growth, covering payroll, and managing seasonal inventory swings. In contrast, commercial real estate loans are structured for the long-term acquisition or development of property, reflecting the extended lifespan and stable value of real estate assets.

    When we look at collateral, C&I loans typically rely on a company’s assets like accounts receivable, inventory, and existing equipment. This differs significantly from CRE loans, where the property itself serves as collateral, and equipment financing, where the newly purchased machinery, vehicles, or technology secures the debt. This collateral structure directly influences the repayment term, where C&I loans often operate with shorter 1-5 year horizons aligned with operational cycles, whereas CRE loans can amortize over much longer periods of 10 to 30 years.

    These differences underscore why there is no single “best” option—only the right instrument for a specific business objective. Our advisory process, highlighted on our Raise platform, involves a detailed review of a company’s financial standing, cash flow projections, and strategic goals to match you with appropriate lending structures.

    Comparison of C&I loans, commercial real estate loans, and equipment financing options.

    Understanding these differences is the first step. The next section will walk you through the qualification process for a C&I loan. We encourage you to review the details carefully, and when you’re ready to explore how a tailored debt solution can support your growth, you can Book A Call with our team.

    This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to transact. This is not investment advice; please consult your legal, tax, and financial advisors before making decisions.

    Collateral, Eligibility, and Loan Structuring for C&I Lending

    Beyond the basic loan purpose, successful C&I financing depends on three pillars: collateral, borrower eligibility, and loan structure. For businesses seeking commercial and industrial loans, understanding how lenders assess each of these areas is essential to securing terms that align with operational needs and growth goals. Our advisory team at Zaidwood Capital helps companies navigate these criteria, drawing on institutional requirements to build a strong lending case.

    Types of Collateral in C&I Lending

    The collateral securing the facility is a primary driver of advance rates and overall credit appetite. Lenders evaluate asset quality, liquidity, and valuation risk to determine how much they are willing to advance against each class. The table below summarizes the most common collateral types accepted in C&I loans, alongside their typical advance ranges and how institutional lenders generally view each asset class.

    Accounts receivable financing consistently receives the most favorable treatment, with advance rates reaching 70 to 90 percent. Because these assets convert to cash relatively quickly, they represent the most liquid form of collateral in C&I lending. Inventory, by contrast, carries more uncertainty. Advance rates of 30 to 60 percent reflect obsolescence risk, shelf-life concerns, and the challenge of liquidation if a borrower defaults. Equipment and machinery can provide solid collateral support at 50 to 80 percent of appraised value, provided the assets are well-maintained and have a clear secondary market. Real estate, while strong, is often carved out for commercial real estate-specific products rather than traditional C&I lines.

    Lender Eligibility Criteria

    Institutional lenders apply a consistent set of financial metrics to gauge a borrower’s ability to service C&I obligations. Per Zaidwood Capital’s guidance on asset-based lending, a debt-service coverage ratio of 1.25x or higher is a typical baseline. This means the company’s operating cash flow should cover all scheduled debt payments with a comfortable margin. Lenders also examine liquidity through the current ratio, generally expecting it to remain above 1.0x, though stronger ratios improve negotiating power.

    Beyond ratios, the documentation package is critical. Institutional investors require audited financial statements covering at least the last three fiscal years, detailed accounts receivable aging reports, and third-party inventory or equipment appraisals. The U.S. Securities and Exchange Commission’s reporting standards underpin many of these requirements, ensuring that the financial information lenders rely on meets a recognized threshold of accuracy. Our role is to assemble and present this package in a format that aligns with how institutional credit committees evaluate risk.

    Loan Structuring: Rates and Terms

    Once collateral and eligibility are confirmed, the loan structure defines how the capital is priced and repaid. Interest rate choice is often the first decision point. Variable-rate loans are typically tied to the Secured Overnight Financing Rate, or SOFR, plus a spread that reflects the borrower’s credit profile and transaction size. While this structure can offer lower initial costs, payments fluctuate with market conditions. Fixed-rate loans carry a premium for the interest-rate certainty they provide, making them attractive for companies that prioritize predictable budgeting over potential savings in a declining rate environment.

    Repayment terms can be just as important as the rate itself. For businesses with uneven revenue cycles, seasonal or deferred payment structures are often built into the agreement. For capital-intensive purchases, equipment financing can be structured with seasonal or deferred payment plans, linking directly to our detailed FAQ. This flexibility allows borrowers to match debt service to cash generation, reducing strain during off-peak periods. With the collateral and structure defined, the next step is preparing a complete application package. To discuss how these terms can be tailored to your specific situation, we invite you to Book A Call for a custom quote.

    Strategic Uses of C&I Loans: Working Capital and Equipment Financing in Practice

    Now that we understand the broad benefits of C&I loans, let’s explore two of their most strategic applications in practice. Commercial and industrial loans provide the structured capital that businesses need for specific operational and growth objectives, from managing day-to-day cash flow to acquiring essential equipment. At Zaidwood Capital, our Debt Advisory team helps clients navigate these applications, structuring solutions that align with both immediate needs and long-term business plans.

    The following table matches common business needs to the appropriate loan structure, documentation requirements, and typical use cases.

    Common Collateral Types for C&I Loans
    Collateral TypeDescriptionTypical Advance RateLender Preference
    Accounts ReceivableInvoices from creditworthy customers70%–90%Highly preferred due to liquidity
    InventoryRaw materials, WIP, finished goods30%–60%Moderate; depends on obsolescence risk
    Equipment & MachineryFixed assets with appraised value50%–80%Good; stable collateral if well-maintained
    Real EstateCommercial or industrial property60%–75%Strong, but often used in CRE-specific products

    These three structures cover the most frequent strategic uses of C&I loans we encounter in our advisory work. Selecting the right one depends on your specific objective, the collateral available, and the documentation you can provide to support the request.

    Financing Working Capital with C&I Loans

    For businesses facing seasonal demand fluctuations or uneven cash flow cycles, working capital financing through an asset-based revolving line of credit offers a practical solution. This structure uses your company’s accounts receivable aging and inventory reports as collateral, creating a borrowing base that increases as your operational assets grow. Rather than waiting for customer payments to arrive, you draw against the value of outstanding invoices and on-hand inventory to cover immediate needs.

    Qualifying for this type of facility requires clear cash flow projections that demonstrate your ability to service the debt across different points in your business cycle. Lenders reviewing your application will want to see consistent patterns in your A/R aging, turnover rates on inventory, and realistic forward-looking projections that account for both peak and off-peak periods.

    A real-world example helps illustrate how this works in practice. Consider a wholesale distributor in Baltimore that experiences a predictable seasonal inventory buildup ahead of the summer months. To purchase stock and cover operating expenses during the slower winter period, the business establishes an asset-based line of credit secured by its receivables and inventory. This structure provides the liquidity needed to make supplier payments on time without depleting cash reserves, and the credit line contracts as receivables are collected, keeping the cost of capital aligned with actual usage.

    All documentation and loan structuring must comply with relevant securities regulation and investor protection standards where applicable. For the working capital example above, the key documents needed include:

    • Accounts receivable aging reports showing outstanding invoice balances and due dates
    • Inventory reports detailing stock levels, valuation, and turnover rates
    • Cash flow projections covering seasonal peaks and troughs

    Equipment Financing: A Practical Application

    Commercial and industrial loans also provide a structured path for acquiring machinery, vehicles, or IT infrastructure without depleting working capital. Equipment financing typically takes the form of a term loan secured by the purchased asset itself, meaning the equipment serves as collateral for the loan. This approach preserves liquidity while allowing the business to put the new asset to productive use immediately. According to internal resources from Zaidwood Capital, the process follows a clear, step-by-step sequence.

    Start by obtaining a professional equipment appraisal to establish the fair market value of the machinery you want to purchase. Next, secure a detailed invoice or purchase order from the vendor that specifies the equipment, pricing, and delivery terms. With these documents in hand, our Debt Advisory team can structure the term loan to match the useful life of the equipment, with repayment terms that align to your projected cash flow from using the asset.

    Businesses with seasonal revenue patterns can also benefit from structured flexibility in their equipment financing. In Baltimore, a company that generates the majority of its revenue during the summer tourism season can arrange a payment schedule with higher installments during peak months and reduced or skipped payments in the winter. This alignment ensures that debt service never outpaces available cash flow. Documentation best practices for equipment financing applications include:

    • Equipment appraisal establishing fair market value
    • Detailed invoice or purchase order from the vendor
    • Two to three years of business financial statements and tax returns
    • Business plan or statement outlining the intended use of the financed equipment

    With these structured applications in mind, we can now examine how businesses and advisors proceed through the full lifecycle of a C&I loan transaction.

    Optimizing Financial Health with Commercial and Industrial Loans

    A core component of debt advisory is helping companies optimize their financial health through commercial and industrial loans, a category of short-to-medium-term financing designed to fund day-to-day operations. C&I loans can be used for various purposes, from purchasing inventory and machinery to covering working capital needs. By strategically deploying these loans, businesses can maintain momentum without sacrificing equity. We work with our clients to structure C&I loans that enhance liquidity, building a stronger foundation for scalable growth.

    C&I loans are often structured as asset-based lending, secured by a company’s receivables or inventory. This approach unlocks capital tied up in current assets, improving cash flow without ownership dilution. For businesses with strong recurring revenue, cash flow financing serves as a complementary tool, allowing them to borrow based on their ability to generate predictable revenue streams. Institutional investors in our network, which comprises over 4,000 entities, can offer flexible terms that may not be available through traditional banks. According to our qualification framework, lenders evaluate collateral quality, EBITDA trends, and comprehensive business plans during the due diligence process.

    Our debt advisory team aligns each client’s C&I loan structure with its specific growth stage and operational cycles. By assessing financial statements, projected cash flows, and expansion plans, we match companies with institutional lenders whose investment criteria align with their sector and deal size. This tailored approach ensures that the resulting capital structure supports working capital efficiency and positions the business for future capital raises. Our team has successfully raised over $800 million in financing solutions, leveraging access to more than $5 billion in deployable debt.

    Proper structuring of C&I loans can strengthen a company’s balance sheet and credit profile, while adherence to financial industry regulation and investor education standards helps ensure transparency in C&I loan agreements. We encourage businesses to discuss their C&I loan structuring needs with our debt advisory team.

    Now let’s address some common questions businesses have about commercial and industrial loans. The regulatory landscape is shaped significantly by federal oversight, with the FTC consumer and business protection division playing a key role. Our team emphasizes that awareness of these protections is a fundamental step in responsible commercial and industrial financing.

    What is the FTC’s role in C&I lending?

    The Federal Trade Commission enforces truth-in-lending requirements and prohibits unfair or deceptive acts against businesses. This oversight creates a baseline of borrower protection for C&I loans, ensuring lenders provide transparent terms and cannot engage in predatory practices.

    How can businesses evaluate lender credibility?

    Business owners should verify lender registrations, review financing terms carefully, and consult the FTC’s business guidance on lending to identify red flags. We advise our clients to avoid any lender unwilling to disclose clear, written documentation.

    What should borrowers know about collateral and guarantees?

    Many commercial and industrial loans require collateral or personal guarantees. The FTC’s truth-in-lending standards mandate that these obligations be clearly disclosed upfront, helping borrowers make informed decisions without hidden risk.

    For more detailed guidance on securing C&I financing, our team can help.

    Partnering with a Capital Advisory Firm for C&I Financing

    Navigating the complexities of commercial and industrial loans demands more than a strong balance sheet—it requires a partner who understands institutional lending at scale. Zaidwood Capital’s debt advisory team evaluates a company’s financial position, cash flow profile, and collateral base to structure tailored C&I financing solutions. By leveraging a network of over 4,000 investors and more than $15 billion in deployable capital, we streamline the transaction process and connect businesses to the right capital partners. Through our Full-Cycle M&A and capital advisory approach, we guide clients from initial due diligence through closing, ensuring every phase moves with precision.

    Securities are offered through Finalis Securities LLC, a registered broker-dealer. Zaidwood Capital LLC is not a registered broker-dealer, and no content herein constitutes an offer or solicitation of securities. Investments involve risk, and past performance does not guarantee future outcomes.

    Resources

  • Best Asset Based Lending for 2026: Top Companies Compared

    Best Asset Based Lending for 2026: Top Companies Compared

    Table of Contents

    Asset-Based Lending as a Strategic Financing Tool

    Beyond traditional cash-flow loans, asset-based lending offers a strategic alternative for companies seeking flexible, secured financing against their balance-sheet assets. The U.S. Securities and Exchange Commission defines collateral as an asset a lender accepts as security for a loan, including real estate, equipment, inventory, and accounts receivable—precisely the assets that underpin asset-based lending structures.

    Through asset-based lending, businesses can often achieve higher leverage than unsecured debt and benefit from lower interest rates because the loan is backed by tangible collateral. This approach is especially valuable for companies with strong asset bases but uneven earnings, as the financing capacity is tied to asset values rather than cash-flow metrics alone.

    Qualifying typically requires a disciplined institutional process. As outlined in our FAQ, investors commonly look for collateral coverage ratios—often 1.5x to 2.0x advance rates—together with audited historical financials, minimum EBITDA thresholds, and thorough asset-quality audits. These benchmarks help our team identify the right institutional match from a network of over 4,000 investors, including banks, credit funds, and specialty finance firms.

    Unlike cash-flow financing, which depends heavily on EBITDA, asset-based lending unlocks liquidity directly from receivables, inventory, equipment, or real estate. Many companies use both structures concurrently, blending them to optimize cost of capital and funding flexibility. Through our global lending services, we connect clients with institutional investors specializing in asset-based lending and other secured debt structures.

    Asset-based lending can fund acquisitions, bridge equity gaps, or provide seasonal working capital—but outcomes are not guaranteed and depend on asset quality and deal structure. While many companies qualify, each transaction is subject to investor approval and due diligence.

    In the following section, we explore how ABL can be structured alongside equity financing to maximize transaction efficiency.

    This is not an offer or solicitation; consult your advisor.

    Understanding Asset-Based Lending Fundamentals

    Having defined asset-based lending, let us examine its core mechanics and how it compares with traditional financing. Asset based lending is a secured financing facility where the borrowing amount is determined by the value of specific pledged assets rather than primarily by cash flow or credit history. This type of secured lending relies on four main asset classes: accounts receivable, inventory, equipment, and real estate, each valued with distinct advance rates that reflect their liquidity and liquidation potential.

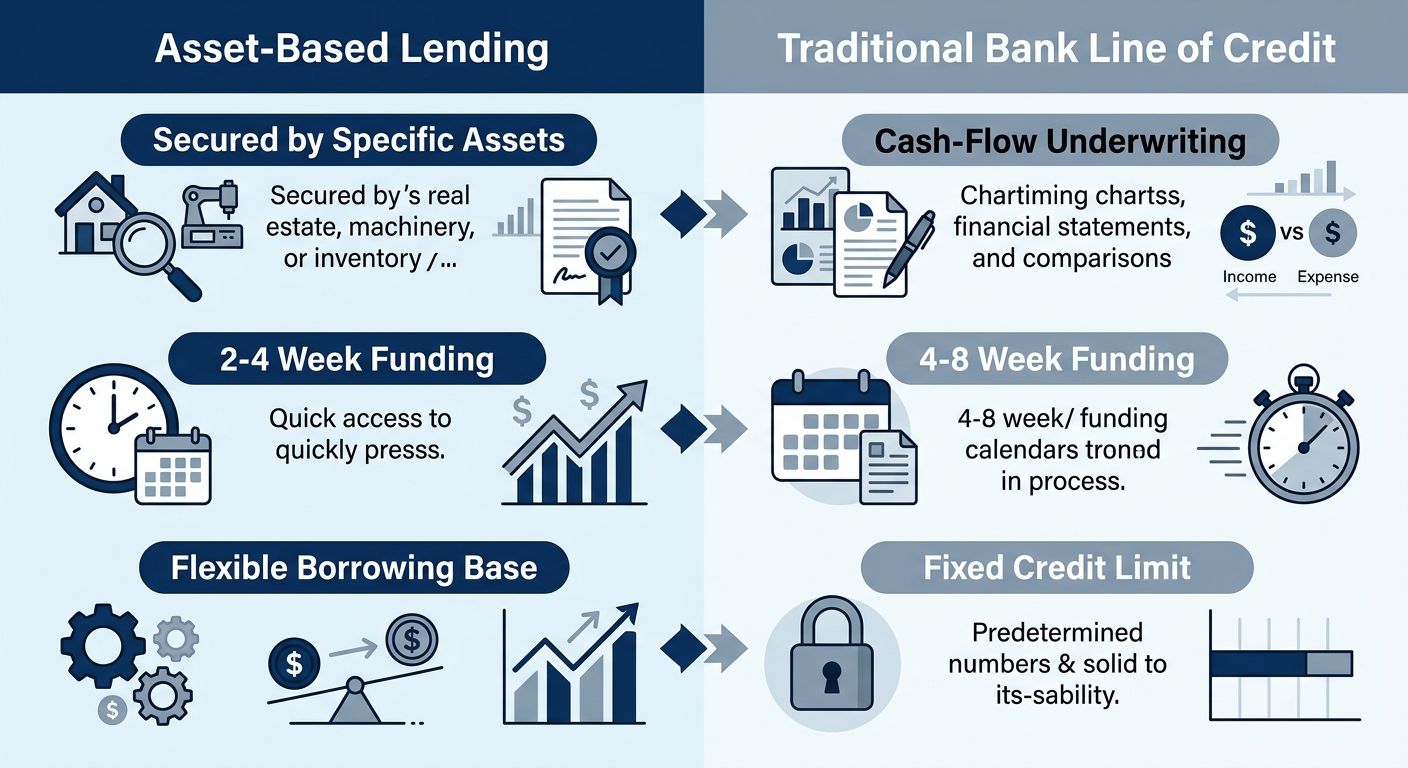
    The following table highlights the key differences between asset-based lending and a traditional bank line of credit.

    Asset-Based Lending vs. Traditional Bank Line of Credit
    DimensionAsset-Based LendingTraditional Bank Line of Credit
    Collateral RequirementSecured by specific assets (AR, inventory, equipment, real estate)Often unsecured or blanket lien; may require personal guarantees
    Underwriting FocusAsset quality and liquidation value; less emphasis on cash flowCash flow, credit history, and overall financial health
    Funding SpeedTypically 2–4 weeks; faster for revolving facilitiesCan take 4–8 weeks or longer for approval and funding
    FlexibilityHighly flexible; borrowing base adjusts with asset levelsFixed credit limit; less responsive to asset fluctuations
    CovenantsFewer financial covenants; focus on asset reportingStrict financial covenants (debt service coverage, leverage ratios)

    An ABL facility emphasizes the quality and liquidation value of collateral, with fewer financial covenants and a borrowing base that flexes alongside asset levels. For businesses with strong collateral but variable cash flow, such as manufacturers, wholesalers, or distributors, secured asset lending often provides faster access to capital and greater responsiveness to seasonal or growth-driven asset fluctuations.

    Comparison infographic of asset-based lending versus traditional bank line of credit highlighting differences in security, funding timeline, and flexibility
    Comparing asset-based lending and traditional bank line of credit

    Underwriting in asset-backed financing concentrates on the quality, liquidity, and liquidation value of the pledged collateral. Advance rates vary by asset class, with accounts receivable typically commanding higher advance rates than inventory or equipment. This approach shifts reporting toward asset monitoring rather than strict debt service coverage ratios, making ABL accessible to companies that may not meet conventional bank criteria. For a broader perspective on financing options, our coverage of global lending services alternatives provides key considerations for borrowers comparing ABL with other structures.

    Deep Dive into Asset-Based Lending Structures and Collateral Types

    To understand how asset based lending works, it is essential to examine the four primary collateral types that underpin every ABL structure. Each asset class carries distinct risk profiles, valuation methodologies, and advance rate ranges that directly influence the amount of capital a business can access and the speed at which funds become available.

    Primary Collateral Categories and Their Characteristics

    In asset based lending, collateral types determine both eligibility and borrowing capacity. The U.S. Securities and Exchange Commission defines collateral broadly as assets pledged to secure a loan, and within ABL structures, lenders focus on four principal categories based on their liquidity and ease of valuation.

    Accounts receivable represent the most liquid and preferred collateral class. Lenders evaluate AR through aging reports that identify overdue invoices, dilution analysis that measures returns and allowances against gross sales, and concentration limits that cap exposure to any single debtor. Because receivables convert to cash through normal collection cycles, they carry the highest advance rates and fastest funding timelines.

    Inventory serves as a common but more complex collateral type. Valuation requires third-party appraisal that accounts for obsolescence risk, seasonal demand patterns, and turnover velocity. Finished goods ready for sale command stronger valuations than raw materials or work-in-progress, which have limited liquidation markets.

    Equipment and real estate round out the primary categories, with valuations based on orderly liquidation value and professional appraisal, respectively. Equipment financing benchmarks indicate ABL structures typically extend 50 to 80 percent of orderly liquidation value depending on age, condition, and secondary market demand. Real estate requires the most extensive due diligence, including title searches and environmental assessments.

    Loan-to-Value Determinants and Advance Rate Mechanics

    Loan-to-value ratios in asset based lending emerge from a lender’s assessment of advance rates, eligibility criteria, and concentration limits applied to each asset class. The LTV is not a fixed percentage but a calculated figure reflecting the lender’s confidence in recovering principal through liquidation of the pledged collateral.

    Collateral Types and Advance Rates in Asset-Based Lending
    Asset TypeTypical Advance RateValuation MethodLiquidity / Speed of Funding
    Accounts Receivable70–90% of eligible ARAging reports, dilution analysis, concentration limitsFast; funds available within days of invoice submission
    Inventory40–60% of appraised valueAppraisal by third-party; considers obsolescence and turnoverModerate; requires field exam and appraisal
    Equipment50–80% of orderly liquidation valueAppraisal based on age, condition, and secondary marketModerate; appraisal and documentation needed
    Real Estate60–75% of appraised valueProfessional appraisal, title search, environmental assessmentSlower; due diligence and legal process required

    Advance rates represent the percentage of an asset’s appraised or eligible value that a lender will fund. Accounts receivable command the highest rates at 70 to 90 percent of eligible receivables because they self-liquidate through customer payments. Inventory advance rates sit lower at 40 to 60 percent, reflecting the inherent risk of physical goods degradation and market fluctuation.

    Funding Speed and the Asset-Based Lending Process

    The timeline from application to funding in asset based lending varies considerably by asset type and the intensity of due diligence required. Borrowers who prepare documentation thoroughly and understand lender expectations can materially compress the timeline.

    The ABL due diligence process typically begins with a field exam, where auditors physically inspect assets, verify accounting systems, and test the accuracy of borrowing base reports. For AR-heavy structures, this involves confirming invoice validity and analyzing customer payment patterns. Businesses exploring global lending services alternatives can compare ABL timelines against other capital sources to determine the optimal structure.

    Practical Guide to Securing Asset-Based Lending for Growth and Acquisitions

    Now that you understand the fundamental structure and purpose of asset-based lending, it’s time to explore a practical guide for securing this flexible financing tool. For companies with strong balance sheets but uneven cash flow, asset-based lending provides a tactical pathway to fund growth initiatives and execute acquisitions.

    Preparing Your Business for an Asset-Based Lending Application

    • Compile Detailed Financial Statements: Gather at least three years of audited financial statements, including balance sheets, income statements, and cash flow reports.
    • Prepare Precise Asset Schedules: Create comprehensive, up-to-date schedules for all assets that will serve as collateral, including accounts receivable aging reports and inventory listings.
    • Assemble Due Diligence Materials: Organize corporate documents, tax returns, customer and supplier contracts, and legal records.

    Using Asset-Based Lending for Acquisitions and Growth

    Asset-based lending is a powerful engine for mergers and acquisitions, offering flexible structures that traditional cash-flow loans often cannot match. We consistently see clients use ABL facilities in three principal ways during M&A: Leveraged Buyouts, Post-Acquisition Working Capital, and Bridge Financing.

    Advantages of Asset-Based Lending for Corporate Growth

    For asset-rich companies, the strategic advantages of asset-based lending are significant and multifaceted. The structure is designed to support rapid scaling and operational flexibility, which is why it is often recommended for companies navigating high-growth phases.

    Asset-Based Lending vs. Alternative Debt Structures
    Debt StructureCollateral FocusTypical Cost (Interest + Fees)Best For
    Asset-Based LendingSpecific assets (AR, inventory, equipment, real estate)LIBOR/SOFR + 3–6%Working capital, growth, acquisitions with asset-rich borrowers
    Cash-Flow LoanGeneral business assets / blanket lienPrime + 2–5%Established companies with strong cash flow and credit history
    Mezzanine DebtSubordinated; often unsecured with equity warrants12–20% (including equity upside)Growth capital, acquisitions, buyouts for mid-market companies
    Equipment FinancingSpecific equipment being purchased6–12%Capital-intensive businesses acquiring machinery or vehicles

    This website is for informational purposes only and is not an offer, solicitation, or commitment to transact. It is not investment advice. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Advanced Considerations in Asset-Based Lending for M&A and Complex Transactions

    While ABL is versatile for general purposes, its application becomes more nuanced in M&A and complex deals. In an acquisition context, asset based lending serves as a senior secured facility, often structured to support working capital, bridge financing, or leveraged buyout (LBO) debt.

    Asset-Based Lending vs. Mezzanine Debt vs. Equity for M&A
    Financing TypeCost RangeDilution / ControlBest Use in M&A
    Asset-Based LendingSOFR + 3–6%No dilution; lender has lien on assetsSenior secured facility for working capital, bridge financing, or LBO debt
    Mezzanine Debt12–20% (including warrants)Minimal dilution; warrants may give equity upsideSubordinated layer to fill gap between senior debt and equity
    Equity Financing15–30%+ expected returnSignificant dilution; investors gain ownership and control rightsGrowth equity, buyouts, or when debt capacity is limited

    Frequently Asked Questions About Asset-Based Lending

    Q: What is asset based lending? Asset based lending is a secured financing structure where a business pledges balance-sheet assets such as accounts receivable, inventory, or equipment as collateral. Unlike traditional cash-flow lending that emphasizes credit scores and profitability, ABL focuses on the liquidation value of the pledged assets.

    Q: How does collateral work in an asset-based loan? Collateral is property offered to secure a loan—the U.S. Securities and Exchange Commission defines it as something a lender can seize if the borrower defaults. In asset-based lending, lenders first appraise the pledged assets and then set a borrowing base that reflects their realizable market value.

    Q: What are typical advance rates for asset-based loans? Advance rates vary by asset quality, but receivables commonly qualify for 70–85 percent and inventory for 50–60 percent of the appraised value.

    Leveraging Asset-Based Lending with Zaidwood Capital’s Debt Advisory Expertise

    Asset based lending uses a company’s receivables, inventory, and equipment as collateral, unlocking more flexible capital than unsecured debt. Our debt advisory team structures ABL facilities around your cash flow and collateral profile, connecting you to over 4,000 institutional investors and more than $15 billion in deployable capital. We engineer tailored terms that deliver higher leverage and greater flexibility than conventional bank loans—especially for growing or cyclical businesses.

    Resources

  • Asset-Based Lending: Complete Guide for Businesses

    Asset-Based Lending: Complete Guide for Businesses

    Table of Contents

    Asset-Based Lending: A Strategic Financing Option for Growth

    Asset-based lending (ABL) is a form of financing secured by a company’s assets, typically accounts receivable, inventory, equipment, or real estate. Unlike cash-flow-based loans that rely on credit history, ABL focuses on the collateral’s value, making it accessible even for businesses with limited operating history. Advance rates vary: receivables often command 80–90%, while inventory may secure 50–70% of its appraised value.

    ABL provides liquidity and flexibility through revolving credit lines that expand as your asset base grows, supporting working capital and growth initiatives. With faster funding than traditional loans, ABL helps companies seize opportunities without delay. At Zaidwood Capital, we leverage our network of 4,000+ institutional investors and access to over $15 billion in deployable capital to structure tailored ABL facilities. As a full-cycle M&A and capital advisory firm, we streamline the process from due diligence to closing. Our advisory team helps you evaluate asset eligibility and structure a facility that aligns with your strategic goals. By unlocking the value of your balance-sheet assets, ABL provides the working capital necessary for expansion, acquisitions, or seasonal cash-flow management.

    For companies exploring complementary solutions, we also facilitate venture debt to support growth. Contact us to Book A Call and discover how ABL can fuel your business expansion.

    Revolving Credit Facility (ABL)

    A Revolving Credit Facility (ABL) is an asset-based lending structure providing a secured line of credit backed by accounts receivable, inventory, and sometimes equipment. We use these facilities to supply working capital for seasonal inventory builds and growth initiatives. The borrowing base is recalculated monthly against pledged receivables and inventory to reflect current collateral. Companies with a PEO often combine it with an ABL facility for cash management.

    Inventory Financing

    Inventory financing is a type of short-term, asset-based lending that uses a company’s existing inventory as collateral to secure working capital. Businesses typically use it to purchase additional stock, bridge cash flow gaps, or capitalize on seasonal demand surges. Lenders advance a percentage of the inventory’s value—often 50% to 80%—and repayment occurs as the goods are sold. Through our global lending services debt advisory, we structure these inventory-secured arrangements to secure optimal advance rates and covenants for your business.

    Accounts Receivable Financing

    Accounts receivable financing, a form of asset-based lending, lets businesses borrow against unpaid invoices rather than waiting 30 to 90 days for payment. Companies sell or collateralize receivables to receive a percentage of the invoice value upfront. This asset-backed solution suits B2B firms, manufacturers, and wholesalers with extended cycles. Underwriting hinges on payer creditworthiness, not the borrower, and we help clients unlock this flexible path to improved working capital.

    Equipment Financing

    Within our debt advisory practice, we offer specialized equipment financing solutions. Equipment financing is a common form of asset-based lending where the equipment itself serves as collateral, enabling businesses to acquire needed assets. Structures include loans for ownership or leases for usage rights, applicable to machinery, vehicles, technology, and medical equipment. We advise on structuring and connect clients with appropriate capital sources, and all terms are custom-quoted based on credit, equipment type, and market conditions. Book A Call for a personalized consultation.

    Asset-Based Term Loan

    Within asset-based lending, an asset-based term loan is a single-draw, asset-backed loan commonly used for business acquisitions, capital expenditures, and debt refinancing. Unlike a revolving line, it provides a lump sum with a fixed repayment schedule. Loan amounts are based on collateral values, typically 70–85% of accounts receivable and 50–70% of equipment appraisals. At Zaidwood Capital, we structure these solutions by leveraging our institutional network.

    Purchase Order Financing

    Purchase Order Financing helps businesses fulfill large orders when working capital is tight. A lender pays the supplier, and the business repays after the customer invoice is settled. Unlike traditional loans, approval depends on the purchase order’s value, not credit history. We offer it through our debt advisory network, alongside asset-based lending and tailored structured solutions. Contact us to discuss how we can bridge your cash-flow gaps.

    Warehouse Lending

    Warehouse lending is a specialized form of asset-based lending—a short-term revolving facility that funds asset accumulation, such as loan origination, before permanent takeout financing is arranged. Through our Debt Advisory practice, we assist clients in structuring and sourcing these collateralized facilities. Leveraging our network of over 4,000 institutional investors, we identify appropriate warehouse lending partners. This solution focuses on liquidity and speed, not long-term capital, and is one of several debt options we help clients evaluate.

    Bridge Loan (Secured by Assets)

    A bridge loan is a short-term, asset-backed financing solution that helps you bridge a funding gap, secured by collateral like real estate, inventory, or receivables. Common uses include M&A, recapitalizations, and pending asset sales. At Zaidwood Capital, we provide bridge loan advisory as part of our debt advisory services, within asset-based lending. We leverage our network and expertise to structure flexible, fast-execution financings, streamlining transactions.

    Structured Asset-Based Finance

    Structured asset-based finance is a form of asset-based lending secured by assets like accounts receivable, inventory, equipment, or real estate. It delivers working capital and liquidity without requiring asset sales or equity dilution. As a full-cycle M&A and capital advisory firm, we facilitate structured asset-based finance through our network of over 4,000 institutional investors, enabling companies to unlock capital while preserving ownership.

    Special Situations ABL

    Beyond standard asset-based lending, we also advise on special situations that demand tailored debt solutions:

    • Turnaround and distressed scenarios where collateral is impaired or operations are restructuring
    • Cross-border structures involving multiple jurisdictions and currency considerations
    • Growth-stage transactions where companies hold unconventional asset bases such as intellectual property or receivables
    • Time-sensitive acquisition or bridge financing needs

    These mandates reflect our Full-Cycle M&A and capital advisory approach.

    Asset-Based Lending Options at a Glance

    To help you compare options at a glance, we’ve summarized key asset-based lending tools:

    Comparison of Asset-Based Lending Tools
    Asset TypeAdvance RateBest ForTypical Term
    Accounts Receivable, InventoryUp to 85% on AR, 50-65% on InventoryWorking capital needsRevolving
    Inventory50-65%Seasonal inventory buildup6-12 months
    Accounts ReceivableUp to 85%Cash flow accelerationRevolving
    Equipment70-80% of appraised valueCapital equipment purchases3-7 years
    Multiple asset classesVariesLarger, more complex facilities2-5 years
    Purchase ordersUp to 100% of PO valueFulfilling large ordersShort-term
    Residential mortgage loansVariesMortgage lendersShort-term
    Real estate, receivables, other assetsVariesBridge financing gaps6-24 months
    Diverse asset poolsCustomComplex capital structures1-5 years
    Distressed or unique assetsNegotiatedRestructuring or special situationsShort-to-medium term

    Please note that the advance rates shown are typical market ranges; actual terms depend on the specific lender, your financial profile, and asset quality. At Zaidwood Capital, we work with you to structure the right facility, using our experience with over 300 deals and a network of 4,000+ investors. The following sections provide a detailed look at each asset-based lending option.

    Grid of 10 minimalist icons representing asset-based lending options including revolving credit, inventory financing, and equipment financing, each with a short label, on a blue and gray background.

    At-a-glance overview of asset-based lending options across 10 financing types.

    Unlocking Growth with Asset-Based Lending

    Asset-based lending (ABL) allows companies to secure financing using hard assets — receivables, inventory, or equipment — as collateral. Unlike conventional unsecured loans, ABL focuses on the tangible value of the assets rather than solely on credit history. By unlocking embedded balance-sheet value, ABL can provide faster access to capital than traditional underwriting processes.

    Typical use cases encompass working capital smoothing, growth financing, refinancing, and acquisition support. Eligible collateral often includes accounts receivable, inventory, machinery, and real estate. This structure benefits companies with solid asset bases even when cash flow metrics do not meet conventional bank standards. This flexibility makes ABL an attractive option for companies in transition or experiencing rapid expansion.

    At Zaidwood Capital, we design custom ABL facilities as part of our debt advisory offering. Drawing on a network of over 4,000 investors and $15 billion in available capital, we aim to secure competitive, tailored terms for each engagement. Our full-cycle M&A and capital advisory platform ensures that asset-based lending serves as a strategic growth lever, and we can help you explore how ABL complements equity, mezzanine, or other debt instruments in your capital stack.

    Resources

  • Commercial Lending: Complete Guide for 2026

    Commercial Lending: Complete Guide for 2026

    Table of Contents

    Understanding Commercial Lending Options for Business Growth

    Building on our full-cycle M&A and capital advisory capabilities, commercial lending through our debt advisory practice connects businesses with tailored financing solutions. We offer a comprehensive suite of debt financing options, including mezzanine debt, venture debt, equipment financing, and asset-based lending, each designed to support distinct growth objectives. As part of our global lending services, we leverage proprietary data access through our Sovereign Data Nexus and the Velocity Matrix to match clients with the right institutional capital from a network exceeding 4,000 investors with over $15 billion in deployable capital.

    Our debt advisory team structures each business lending solution to fit specific use cases: mezzanine debt for growth capital and acquisitions, venture debt for startups seeking non-dilutive runway, equipment financing for asset purchases without large upfront costs, and asset-based lending for working capital secured by receivables or inventory. We do not lend directly; rather, we serve as a debt advisor, facilitating access to customized capital access strategies through our Precision Catalyst approach. Beyond debt, our equity advisory services offer additional growth pathways for companies exploring minority or majority investment structures.

    Traditional Banks vs Private Commercial Lenders

    Businesses exploring financing quickly encounter two distinct paths: traditional banks and private commercial lenders. While both provide capital, their processes and priorities differ significantly. Banks rely heavily on personal credit scores, debt-service coverage ratios, and a multi-year operating history. Their underwriting is methodical, often taking months to close, and personal guarantees are typically required.

    In contrast, private commercial lenders prioritize the value of your assets and the strength of your cash flow over rigid credit metrics. This allows them to structure asset-based lending and cash-flow financing with greater speed—often delivering capital in weeks rather than months. Terms can be tailored with flexible features like interest-only periods or balloon payments, and covenants are aligned with business performance rather than static ratios. Through our institutional network, we connect companies to lenders offering global lending services that span multiple industries and jurisdictions, typically requiring fewer personal guarantees.

    For growing businesses, private lending offers a viable alternative when traditional bank criteria feel restrictive. Rather than a one-size-fits-all approach, we match firms with institutional investors who understand their unique story. In the next section, we’ll walk through the straightforward application process to access this network.

    Comparing Lending Features: Banks, Private Lenders, and Advisory Firms

    The world of commercial lending offers businesses more choices than many realize, extending well beyond the traditional bank loan. While banks remain a cornerstone for many, private lenders and boutique advisory firms have carved out distinct roles that accommodate diverse funding needs and timelines. Our internal research at Zaidwood Capital LLC provides a clear framework for understanding these differences.

    The following table offers a side-by-side comparison of key features that matter most when evaluating a lending partner.

    Commercial Lending Channel Comparison

    Commercial Lending Channel Comparison
    FeatureTraditional BanksPrivate LendersBoutique Advisory Firm (Zaidwood Capital)
    Eligibility CriteriaStrict credit history, collateral, cash flowMore flexible, emphasis on asset qualityAdvisory-based; connects to suitable institutional lenders
    Speed of FundingWeeks to monthsDays to weeksExpedited through network of 4,000+ investors
    Documentation RequiredExtensive financial statements, tax returns, business plansModerate documentation, focus on asset valuationAdvisor guides documentation preparation
    Collateral RequirementsTypically secured; unsecured options limitedOften asset-backed; flexible structuresHelps identify optimal collateral structure
    CustomizationStandardized loan productsCustomizable termsTailored advisory for each engagement
    Access to CapitalLimited to bank’s balance sheetFund size depends on investor poolAccess to $15B+ deployable capital network

    Eligibility Criteria diverges sharply across these channels. Banks enforce rigid standards around credit scores, cash flow history, and asset coverage, which can often exclude even profitable companies in growth phases. Private lenders pivot the focus toward asset quality, creating a pathway for Asset-Based Lending that uses your company’s own holdings as the primary qualifier. As a boutique firm, Zaidwood Capital advisory bridges these worlds by connecting businesses with institutional lenders whose criteria align with the client’s specific profile, rather than forcing a square peg into a round hole.

    Speed of Funding is often the deciding factor in choosing a commercial loans provider. A traditional bank’s timeline, stretching from weeks to months, can cause companies to miss strategic windows. Private lenders compress this to a matter of days by streamlining their evaluation. We expedite this further by leveraging our network of over 4,000 investors, targeting a closing in under 60 days for mid-market transactions. This velocity can be a competitive advantage in time-sensitive scenarios.

    Three-column comparison infographic showing six lending features across Traditional Banks, Private Lenders, and Boutique Advisory Firms, using blue, green, and orange icon-cards.

    Comparison of lending features across bank, private, and advisory lending options.

    The Documentation Required scales dramatically depending on the source. Banks require a deep dive into comprehensive financial statements, tax returns, and detailed business plans. Private lenders reduce the burden, zeroing in primarily on asset valuation and condition. Our role in the advisory process shifts this burden from the borrower to us: we guide the preparation and assembly of all necessary documentation, ensuring it meets the exacting standards of institutional finance and facilitating a smoother due diligence cycle.

    Key differentiators in the business lending landscape can be summed up in three points: the speed of execution, the flexibility of the structure, and the depth of the capital pool. We provide advisory solutions that are fully tailored, helping to construct an optimal collateral package rather than presenting a one-size-fits-all mandate. With access to over $15 billion in deployable capital, our clients are not limited to a single balance sheet. In the next section, we’ll explore how to determine which of these channels best fits your company’s specific strategic and financial goals.

    This content is for informational purposes only and is not an offer, solicitation, or investment advice. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC.

    Pricing Structures in Commercial Lending

    Pricing in commercial lending is highly structured and reflects a combination of market benchmarks, credit risk, and transaction complexity. We at Zaidwood Capital approach every engagement with a custom-quote philosophy, recognizing that no two capital structures are identical. The core components include an interest rate basis, which may be fixed-rate for the full term or floating-rate tied to a benchmark like SOFR, plus a margin spread that compensates the lender for the specific risk profile of the borrower.

    Beyond the interest component, business lending arrangements typically carry a schedule of fees. These can include upfront arrangement or commitment fees, legal and due diligence costs, and ongoing service or agency charges. The overall debt pricing structure is influenced by the quality of collateral, loan tenor, and prevailing market conditions. Senior secured facilities generally command the tightest margins, while mezzanine and venture debt tranches incorporate higher spreads to reflect their subordinated or cash-flow-dependent nature.

    Our process ensures that commercial loan pricing parameters are calibrated to your specific situation. According to the firm’s FAQ, we require audited financials, multi-year projections, and a detailed business plan to begin a pricing discussion. This thorough due diligence lets us model appropriate capital structures before delivering a tailored quote. All engagements start with a confidential consultation where we outline preliminary pricing frameworks and the path forward.

    This is for informational purposes only and does not constitute an offer or commitment to lend. Consult your advisors.

    Choosing the Right Commercial Lending Path for Your Business

    Choosing the right commercial lending path can determine the success of your growth plans. The main structures — term loans, lines of credit, equipment financing, and asset-based lending — each serve distinct purposes.

    A term loan provides a fixed amount with scheduled repayments, while a line of credit offers flexible working capital. Equipment financing ties repayment to the asset’s life, and asset-based lending uses receivables or inventory as security. Each option balances liquidity, predictability, and asset utilization.

    Your decision should hinge on your business stage, cash flow stability, available collateral, and growth outlook. Early-stage firms may explore venture debt; mature companies often use term loans or credit lines.

    We help you navigate these choices through debt advisory services, including mezzanine, venture debt, equipment financing, and asset-based lending. With access to 4,000+ investors and $15B+ in capital, we provide objective guidance — but we never guarantee specific outcomes or rates. Our team evaluates your capital needs, repayment capacity, and collateral profile to recommend structures that suit operational realities.

    Book a call to discuss your commercial lending strategy with our team.

    Taking the Next Step in Your Commercial Lending Journey

    In commercial lending, the right advisory partner makes all the difference. Zaidwood Capital’s full‑cycle M&A and capital advisory services provide a clear path through complex financing landscapes. Our team leverages a network of 4,000+ institutional investors and an aggregate transaction volume of $24.4B+ to connect businesses with optimal lending solutions.

    We work closely with clients to navigate debt and equity options, backed by comprehensive due diligence and strategic documentation. Whether you’re exploring commercial financing or need to raise capital, we provide the clarity and execution speed you need. With over 80 years of collective experience, our team brings deep market insight to every engagement.

    Ready to move forward? Book A Call today to discuss your unique goals and discover how our advisory services can support your business growth.

    Resources

  • Venture Debt Comparison: Top Providers and Term Sheets

    Table of Contents

    Evaluating Venture Debt for Your Startup

    Once you understand the types of venture debt, the next step is evaluating which option fits your startup. We guide founders through a structured assessment of venture debt providers, focusing on their track record with companies at your stage and in your sector.

    A detailed review of the venture debt term sheet is essential. We help you compare interest rate structures, repayment schedules, and any equity components like warrants. Our team also evaluates loan covenants, prepayment flexibility, and the added value a lender brings, such as investor introductions or the ability to support future equity rounds. We also help tailor terms to your business model.

    Engaging experienced venture capital consultants provides the analytical rigor needed to navigate these complex decisions. After evaluating your options, preparing a strong application is critical to securing the right partner.

    Essential Preparations Before Raising Venture Debt

    Before engaging with lenders, we recommend ensuring your company is fully prepared to raise venture debt. This form of financing requires careful financial and legal groundwork to instill confidence in potential partners.

    We advise our clients to assemble the following key items before initiating discussions:

    • Audited Financial Statements: Prepare audited P&L, balance sheet, and cash flow statements for the past 2–3 years, plus the current interim period.
    • Debt Service Capacity: Calculate a clear Debt Service Coverage Ratio (DSCR) to demonstrate your ability to comfortably cover interest payments.
    • Internal Data Room: Compile a secure repository of legal documents, including your charter, bylaws, cap table, and IP assignments.
    • Governance Review: Examine potential personal guarantees and confirm the board approval process required for new debt.
    • Term Education: Understand that a venture debt term sheet will differ from equity; it avoids dilution but often includes warrants and financial covenants.
    • Strategic Plan: Finalize your existing debt schedule, a detailed use-of-funds plan, and growth projections with sensitivity analysis.

    Rushing into the process with incomplete records or an unclear plan for the capital significantly reduces lender confidence. Engaging experienced venture capital consultants can help streamline this preparation, ensuring your narrative and numbers are aligned before you approach venture debt providers.

    Step 1: Assess Your Startup’s Readiness for Venture Debt

    Determining whether your company qualifies for venture debt is a critical first step. As a capital solution, venture debt can extend your runway without further dilution, but lenders apply rigorous qualification standards. We focus on actionable, objective criteria to ensure you approach the process from a position of strength.

    Primary readiness factors include reaching a minimum annual recurring revenue, typically $1M+ ARR, supported by positive gross margins and a clear use of proceeds. Strong year-over-year growth, often 30% or higher, and backing from an established institutional investor base are key indicators lenders evaluate. You should also review existing debt obligations to confirm there are no restrictive covenants that could conflict with new financing, and develop a detailed cash flow forecast demonstrating your ability to service the debt.

    Once you have assessed your fundamental readiness, the next step is to evaluate potential venture debt providers and their term sheets. For a thorough, data-driven readiness analysis, consider engaging Zaidwood Capital’s debt advisory services.

    Step 2: Understand Venture Debt Fundamentals

    Once you have assessed your capital needs, the next step is to understand the fundamentals of venture debt. Venture debt is a form of debt financing provided to venture-backed companies by specialized lenders, often structured with warrants or interest-only periods. We advise clients that it is most suitable for high-growth startups needing non-dilutive capital for working capital, equipment, or bridging to an equity round without significantly diluting shareholders.

    Unlike traditional bank loans, venture debt providers underwrite based on investor quality and growth trajectory rather than current cash flow or collateral. A typical venture debt term sheet we see includes a 3–4 year maturity, 5–20% warrant coverage, and covenants like minimum cash balances. Providers include banks and specialty finance companies. For regulatory guidance, refer to the SEC small business capital raising resources. Understanding these fundamentals prepares you to evaluate specific venture debt offers and proceed with structuring your debt package.

    Step 3: Compare Venture Debt and Equity Financing

    With a clear understanding of venture debt, the next step is to compare it against equity financing. In venture debt financing, founders retain full ownership but take on fixed repayment obligations, whereas equity financing dilutes founder stakes in exchange for permanent growth capital without mandatory repayment. For many growth-stage companies, the decision hinges on a trade-off between long-term cost and near-term flexibility.

    Equity investors typically require board seats and governance rights that can reshape strategic decisions. Venture debt providers, in contrast, rarely seek board representation, leaving founders with greater operational autonomy. The cost of equity can become substantial over time through carried interest and dilution, while venture debt carries interest and fees but preserves equity upside for existing shareholders.

    The chief risk of venture debt lies in fixed payment schedules that may strain cash flow if revenue projections miss their targets. Equity financing avoids repayment pressure but permanently reduces founders’ share of future returns. Companies often use venture debt to extend runway between equity rounds or to finance specific assets, while equity is sought for foundational, long-term growth. We advise clients to review the venture debt term sheet carefully for repayment terms and covenants before committing.

    For additional resources on comparing financing options, consult the SEC small business capital formation advocate. Once you determine the right fit, proceed to evaluate the venture debt term sheet and negotiate terms that align with your capital strategy.

    This content is for informational purposes and does not constitute investment advice.

    Step 4: Research Venture Debt Providers in the US

    With your venture debt strategy in place, the next critical step is identifying the right provider. When evaluating venture debt providers in the US, we recommend using a focused checklist to narrow your search:

    • Track record: Does the lender have experience with startups at your stage, particularly if you are pre-revenue?
    • Industry focus: Is there a specialization in your sector or business model?
    • Loan size and flexibility: Do their typical facilities match your capital needs, and what is their reputation for supporting portfolio companies during downturns?
    • Terms review: Always request a sample venture debt term sheet from each shortlisted firm and scrutinize the key economic and legal provisions.

    For a deeper look into how financial firms are regulated, explore the FINRA investor resources and insights page. This helps you independently verify the background of any registered entity you are considering, though Zaidwood Capital is not a registered broker-dealer.

    At Zaidwood Capital, we can assist with introductions to our network of venture debt providers and support the review of term sheets, but we do not lend directly or act as a broker-dealer. Once you have shortlisted and received term sheets from two to three aligned providers, you are ready to negotiate key terms.

    Step 5: Structure the Venture Debt Term Sheet

    Once you have identified potential venture debt providers, the next step is to structure the venture debt term sheet with precision. A well-organized term sheet signals sophistication to lenders and accelerates the path to closing. At Zaidwood Capital, we focus on clarity around every core component to ensure your company enters negotiations from a position of strength. The key elements we always emphasize in a venture debt term sheet include:

    • Interest rate (floating or fixed), typically based on a margin over a reference benchmark
    • Maturity period of 3 to 4 years, aligned with your cash flow projections
    • Amortization schedule that may include an interest-only period for early-stage flexibility
    • Prepayment flexibility, with penalties structured only for very early exits
    • Warrant coverage capped as a percentage of the loan amount to minimize equity dilution
    • Financial covenants such as liquidity tests rather than restrictive EBITDA minimums
    • Change-of-control provisions that protect both parties in a future sale or merger

    We advise clients to tailor these terms to their growth stage. Early-stage startups benefit most when we push for lower warrants and longer interest-only periods, preserving runway. Growth-stage companies, on the other hand, often prioritize generous covenant headroom and prepayment options that support refinancing flexibility. For all borrowers, we negotiate dilution-minimizing features like milestone-based tranches that match capital deployment to actual needs, and we frequently include a most-favored-nation clause to adjust terms if your risk profile improves. Using a clean, LSTA-style format reduces ambiguity and speeds up legal drafting. With a well-structured term sheet in hand, you are ready to engage in final negotiations.

    Step 6: Negotiate Covenants and Key Terms

    Once the optimal lender and structure are identified, the final step is negotiating the covenants and key terms. For companies exploring venture debt, this phase determines whether a term sheet becomes a strategic asset or a constraint that limits financial maneuverability.

    We work to secure terms that align with the client’s long-term financial strategy and operational flexibility. The negotiation focuses on financial covenants such as debt service coverage and loan-to-value ratios, along with reporting requirements that are common in venture debt term sheets. Lenders routinely request affirmative, negative, and financial covenants, but overly restrictive clauses can impede growth initiatives or future M&A activity.

    As the client’s advisor, Zaidwood Capital drafts markups, models the impact of each covenant under various operating scenarios, and negotiates directly with venture debt providers on the client’s behalf. Our role is to protect the business from conditions that could constrain liquidity or investment capacity while preserving a competitive cost of capital.

    Step 7: Close the Venture Debt Transaction

    Closing a venture debt transaction marks the culmination of our structured advisory process. Once all conditions are met, the transaction moves to closing where we coordinate venture debt providers, legal counsel, and your team to execute final documents and disburse funds efficiently.

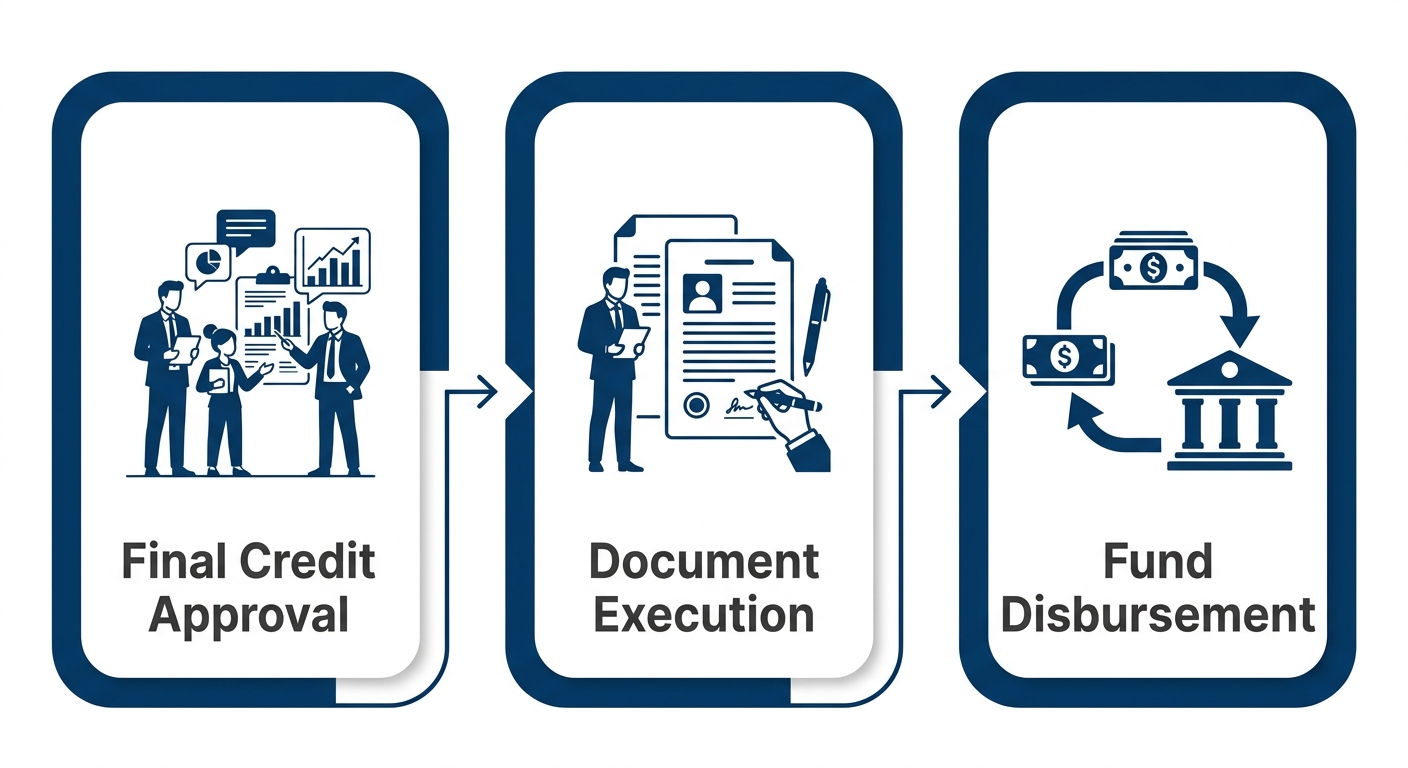
    Final credit approval from the lender committee triggers the closing sequence. The venture debt term sheet becomes the binding commitment document at signing, followed by satisfaction of conditions precedent—including board resolutions, a legal opinion letter, collateral perfection filings, and insurance certificates. Borrower’s legal counsel reviews all documentation prepared by the lender’s outside counsel. At closing, origination fees, legal fees, and third-party costs are settled as negotiated in the engagement letter, and funds transfer via wire to your account according to the agreed draw schedule.

    Securities transactions are executed through Finalis Securities LLC, a registered broker-dealer. Post-closing, we ensure delivery of executed promissory notes, security agreements, and closing certificates.

    Three-stage horizontal process flow diagram for venture debt closing: Final Credit Approval to Document Execution to Fund Disbursement, with professional icons and blue color scheme.
    Horizontal flow visualizing the venture debt closing process.

    To explore how our debt advisory team can streamline your financing, Book A Call with Zaidwood Capital today.

    Troubleshooting Common Venture Debt Challenges

    While venture debt can be a strategic tool for growth-stage companies, it introduces operational complexities that demand disciplined oversight and proactive management. Drawing on our advisory work at Zaidwood Capital, we outline common pitfalls and practical solutions to help companies maintain covenant compliance and lender alignment.

    Covenant monitoring is essential. Typical venture debt agreements may include minimum cash balances, financial reporting requirements, or EBITDA targets. We recommend establishing a monthly review cycle to track these metrics against your loan covenants, using dashboards that pull real-time data from your accounting system. Early detection of a potential breach allows time to renegotiate terms or secure a waiver before default occurs.

    Cash-flow timing remains a persistent challenge—debt service often begins before new revenue materializes. Solutions such as interest-only periods, payment deferrals, or sculpted repayment schedules can bridge this gap if negotiated upfront. Review your venture debt term sheet carefully for prepayment penalties and amortization triggers, as these can limit your flexibility. The U.S. Securities and Exchange Commission provides guidance on structuring debt instruments that we find useful for understanding regulatory boundaries.

    Lender alignment is often overlooked. Not all venture debt providers offer the same degree of sector expertise or willingness to accommodate covenant adjustments. FINRA emphasizes illiquidity and leverage risks in its investor insights, reinforcing the importance of vetting lenders for experience with your industry and growth trajectory.

    A final caution: guard against over-leveraging and dilution-creep. Warrants embedded in venture debt can subtly erode founder equity, especially if multiple rounds of debt are layered. We help companies model the long-term capital-structure impact of warrants and principal obligations.

    This content is for informational purposes only and does not constitute financial or legal advice. Consult your advisors for your specific situation.

    Making Strategic Capital Decisions with Venture Debt

    Venture debt can serve as a powerful complement to equity financing for growth-stage companies that already have venture capital backing or strong revenue trajectories. Unlike traditional bank loans, venture debt financing offers a non-dilutive way to extend cash runway and bridge to critical milestones—allowing founders to preserve ownership while accelerating growth.

    When evaluating a venture debt term sheet, our team helps clients assess core variables such as interest rate, warrant coverage, maturity period, prepayment penalties, and financial covenants. We also bring access to a curated network of venture debt providers—including more than 4,000 institutional and private investors—to help structure, negotiate, and place the right venture debt solution for each client’s unique situation. However, venture debt is typically used alongside equity, not as a replacement, and all investments involve risk.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. Past performance does not guarantee future results.

    Resources

  • Supply Chain Financing Explained: Essential Guide for 2026

    Supply Chain Financing Explained: Essential Guide for 2026

    Table of Contents

    The Foundations of Supply Chain Financing

    Supply chain financing encompasses a set of technology-driven solutions that allow buyers and suppliers to improve working capital without relying on traditional trade finance instruments such as letters of credit. According to Zaidwood Capital’s resource library, SCF is a vital component of global lending alternatives, helping businesses stabilize cash flows while deepening trading relationships.

    Reverse factoring is one of the most widely adopted structures. In this model, a corporate buyer confirms an invoice and a financial institution pays the supplier early at a modest discount, while the buyer repays the financier on a later date. The supplier receives faster cash, the buyer preserves liquidity, and the funder earns a predictable margin—a mutually beneficial arrangement.

    Dynamic discounting offers an alternative mechanism: the buyer uses its own cash to pay invoices ahead of term in exchange for a sliding-scale discount. This gives suppliers near-immediate access to funds at a cost that adjusts with the speed of payment. Inventory finance rounds out the toolkit by providing dedicated funding against stock held in the supply chain, reducing carrying costs and freeing capital for growth.

    Many businesses also layer in equipment financing to complement these solutions, funding the tangible assets that keep supply chains moving. Together these instruments provide greater cash-flow predictability, reduce supplier concentration risk, and strengthen the resilience of the entire supply network.

    Understanding Supply Chain Financing Benefits and Distinctions

    Supply chain financing has emerged as a key buyer-led solution that enables companies to optimize working capital while strengthening supplier relationships. Unlike traditional factoring, which is initiated when a supplier sells its receivables, SCF is initiated by the buyer, leveraging its own credit rating to secure attractive financing terms for its suppliers. This fundamental shift creates a more collaborative and cost-effective financing environment. In this section, we explore the core benefits and six critical distinctions that set supply chain financing apart from traditional factoring.

    The table below compares these financing methods across six critical aspects:

    Supply Chain Financing vs Traditional Factoring
    AspectSupply Chain FinancingTraditional Factoring
    InitiationInitiated by the buyer, leveraging its credit ratingInitiated by the supplier selling its receivables
    Credit AssessmentBased on buyer’s creditworthiness, not supplier’sBased on supplier’s customer credit and invoice quality
    Cost of CapitalLower cost, typically buyer’s cost of funds plus a small marginHigher fees, discount plus service charges
    Working Capital ImpactExtends buyer’s payables without straining supplier, optimizes cash conversion cycleAccelerates supplier cash flow but may not benefit buyer’s DPO directly
    Supplier RelationshipStrengthens buyer-supplier relationship through collaborative liquidityCan be perceived as supplier distress; may damage relationship
    Risk ExposureCounterparty risk primarily on the buyer; operational and legal risksRisk of non-payment by debtor; recourse arrangements common

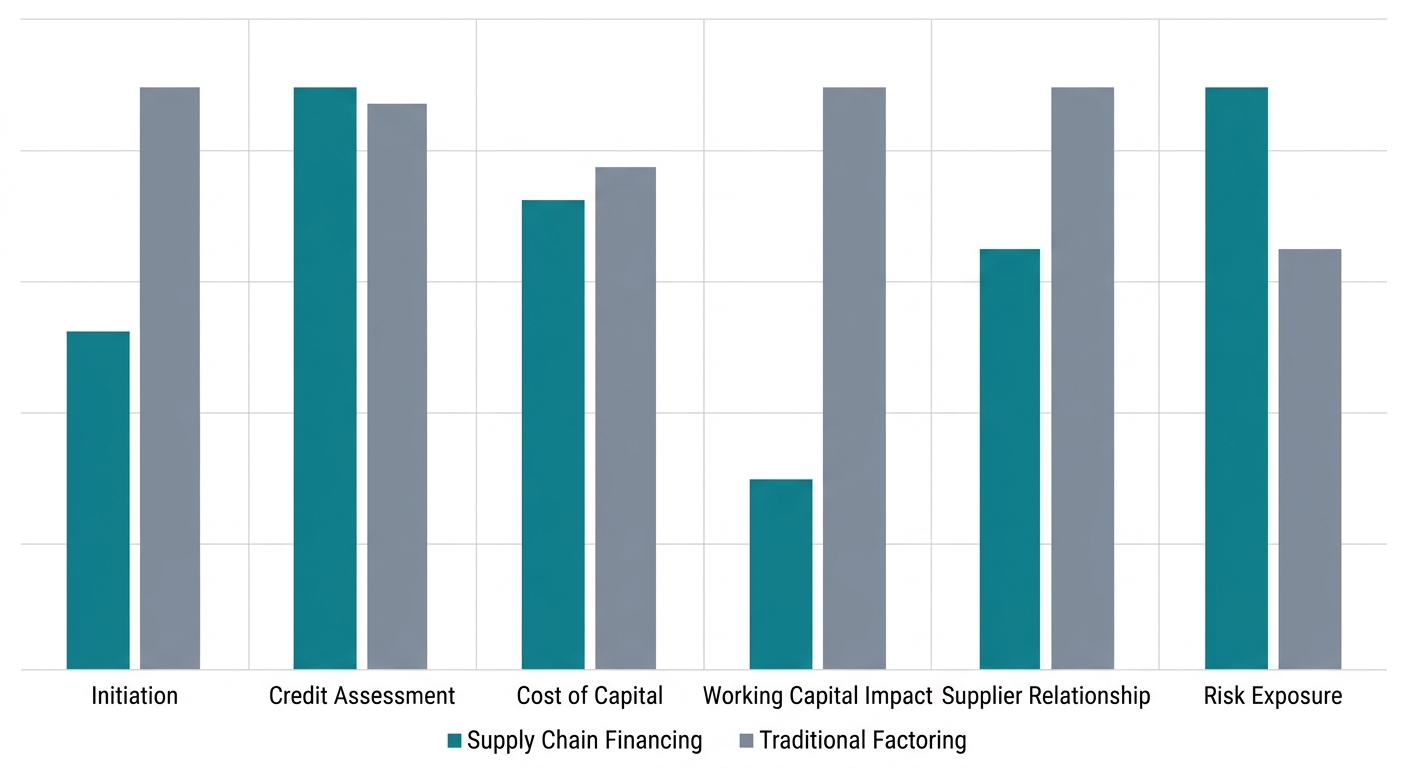
    From a strategic standpoint, supply chain financing delivers a decisive edge by lowering the cost of capital—leveraging the buyer’s credit rather than relying on supplier-level assessments—while simultaneously extending payment terms without squeezing supplier liquidity. This structure optimizes the cash conversion cycle for both parties: buyers preserve working capital, and suppliers gain access to affordable, timely funding. Moreover, because SCF is framed as a collaborative liquidity solution rather than a sign of financial distress, it reinforces trust and long-term supplier relationships, which are critical in today’s interconnected supply chains. The risk profile also shifts favorably; counterparty risk concentrates on the financially stronger buyer rather than on diverse, often smaller, suppliers. As recognized by the International Capital Market Association, these distinctions underscore the role of structured supply chain finance in modern capital markets. From our advisory work, we observe that such buyer-led financing not only enhances operational resilience but also aligns with the interests of all supply chain participants. The chart below visualizes how SCF outperforms traditional factoring across these performance dimensions, reinforcing why it has become a preferred strategy for resilient supply chains.

    Bar chart comparing supply chain financing and traditional factoring across six key performance aspects using teal and gray bars

    Supply chain financing versus traditional factoring comparison across six key business aspects

    Key Mechanisms and Structures in Supply Chain Finance

    Modern supply chain financing (SCF) helps businesses optimize working capital through a variety of structured instruments, each designed to align the liquidity needs of buyers and suppliers. The three primary mechanisms—reverse factoring, dynamic discounting, and approved payables finance—differ in how they fund early payments, yet all share the goal of accelerating supplier cash flow while preserving buyer payment terms. Understanding their inner workings and when to apply each is essential for corporate treasurers seeking to build resilient, financially stable supply networks.

    How Reverse Factoring Unlocks Liquidity

    Reverse factoring, often called approved payables finance, follows a disciplined sequence that centers on the buyer’s credit strength. First, the buyer initiates a supply chain finance program with a financial institution (the funder). The buyer then approves supplier invoices and transmits them to the funder via a digital platform. Upon receiving approved invoices, the funder pays the supplier early—generally after applying a small discount—while the original invoice due date remains unchanged. The buyer ultimately repays the funder at the agreed-upon extended term, thereby preserving its own cash on hand. This structure enables suppliers to access lower-cost capital than traditional factoring because the funding cost is benchmarked against the buyer’s superior credit rating, not the supplier’s.

    For buyers, the arrangement stretches payment terms without squeezing the financial health of their supply chain partners, reducing the risk of supplier insolvency. For suppliers, early payment at competitive rates directly improves working capital. Importantly, supply chain finance programs—especially reverse factoring—are subject to SEC disclosure requirements that promote corporate transparency; stakeholders can monitor regulatory developments through SEC regulatory news and updates. These obligations reinforce the need for robust reporting practices in any SCF initiative.

    Dynamic Discounting vs Approved Payables Finance

    Dynamic discounting takes a different approach: it is a buyer-funded mechanism where the buyer voluntarily offers early payment to suppliers in exchange for a discount that increases the earlier payment is made. The sliding scale is typically calculated per day before the net due date, allowing the buyer to earn an implicit, risk-free return on its surplus cash. Because no external funder is involved, dynamic discounting is most attractive to corporate treasuries that hold ample liquidity and seek to optimize cash returns without introducing third-party credit risk.

    By contrast, approved payables finance (including reverse factoring and multi-bank platforms) relies on an external funder that purchases approved receivables against the buyer’s credit. This model is preferred when the buyer wants to inject liquidity into its supply chain without deploying its own cash, or when it lacks the excess balances needed for dynamic discounting. The following table summarises the key instruments available:

    Types of Supply Chain Finance Instruments
    InstrumentDescriptionTypical UsersBenefitsLimitations
    Reverse FactoringBuyer-initiated program where a funder pays supplier invoices early against the buyer’s credit ratingLarge buyers with strong credit, multiple SME suppliersLower financing cost, stable supply chainRequires buyer commitment; supplier onboarding complexity
    Dynamic DiscountingBuyer offers early payment to suppliers in exchange for a sliding-scale discount based on how early payment is madeBuyers with excess cash; suppliers needing liquidityNo third-party funder; buyer earns better return on cashOnly works if buyer has surplus cash; discount negotiation can be complex
    Approved Payables FinanceSimilar to reverse factoring but often includes multiple buyers and suppliers on a multi-bank platformMultinational corporates, banks, and large supplier networksScalable, automated, integrated with ERP systemsHigh setup costs; requires robust technology integration

    Selecting the right instrument depends on a corporation’s treasury priorities. Reverse factoring shines when the goal is to fortify the supply chain without significant cash outlay, leveraging the buyer’s credit for the benefit of the entire supplier base. Dynamic discounting offers the best fit when the buyer holds surplus cash and can capture a safe, immediate return. For large multinationals managing sprawling supplier networks, approved payables finance delivered through multi-bank platforms delivers the scalability and automation needed to process thousands of invoices efficiently while maintaining compliance with evolving disclosure standards.

    Integrating Technology Platforms into Supply Chain Finance

    Technology platforms are the connective tissue that makes modern supply chain finance practical at scale. Through ERP-integrated portals and, increasingly, blockchain-based ledgers, these systems automate invoice verification, trigger early-payment offers, and execute fund transfers with minimal manual intervention. As soon as a buyer approves an invoice, the platform can instantly notify the supplier and, if the program rules are met, initiate payment to a designated account. Real-time dashboards then allow all parties—buyers, suppliers, and funders—to track invoice status, discount terms, and cash positions, reducing both operational friction and the opportunity for fraud.

    This digitization eliminates paper-based processes and cuts approval cycles from weeks to hours, a critical factor when working capital is tight. Moreover, built-in audit trails align with regulatory expectations, helping firms meet SEC disclosure obligations without additional overhead. As supply chain financing continues to evolve, the seamless integration of these platforms will remain a cornerstone for driving efficiency, transparency, and resilience across global trade ecosystems.

    Implementing Supply Chain Finance for Working Capital Optimization

    Having established the strategic value of supply chain financing for working capital optimization, this section moves from theory to execution. For mid-market CFOs and treasurers, capturing the liquidity benefits demands a structured, three-phase approach: internal readiness assessment, partner selection, and a controlled pilot-to-rollout journey. As Zaidwood Capital’s own resource on preserving working capital demonstrates, instruments that convert large outlays into manageable installments—whether for equipment purchases or supplier invoices—free up cash for essential operations. We focus on practical metrics and milestones that accelerate the cash conversion cycle. The guidance below synthesizes our advisory experience into actionable steps.

    Assessing Your Company’s Readiness for Supply Chain Finance

    Before approaching funders, we recommend a thorough internal review. Several key indicators signal that a company will benefit from receivables financing and can attract competitive terms.

    • Cash Conversion Cycle Metrics: A high days sales outstanding (DSO) or a meaningful opportunity to extend days payable outstanding (DPO) relative to days inventory outstanding (DIO) indicates trapped working capital. If your DPO is well below industry peers, a supply chain finance program can generate immediate liquidity.
    • Credit Profile: Funders typically seek an investment-grade or near-investment-grade rating. Strong financial fundamentals—stable revenue, healthy EBITDA margins, and manageable leverage—can offset a borderline rating.
    • Supplier Segmentation: Prioritize strategic, high-volume suppliers or those reliant on early payment. A segmentation framework identifies the top 10–20 suppliers whose early-payment discount appetite will maximize working-capital lift and simplify onboarding.
    • Technology Infrastructure: Real-time approved-invoice data exchange is essential. Your ERP system (SAP, Oracle, Microsoft Dynamics) should support API integrations or secure file transfers to a funder’s platform.
    • Internal Commitment: Successful programs require dedicated cross-functional resources—treasury, procurement, legal, and IT. Our team provides a readiness checklist to ensure all stakeholders are aligned before launch.

    Selecting the Right Supply Chain Finance Partner

    Choosing the right SCF partner is critical. We evaluate funders and technology providers across multiple dimensions, weighting criteria to align with your strategic objectives.

    • Funder Credit Capacity: Assess the funder’s ability to handle your supply chain’s invoice volume and peak funding needs. Look for a track record of stability and diverse capital sources.
    • Platform Scalability: The technology platform must integrate with your ERP and support rapid supplier onboarding. Examine API capabilities, security protocols, and dashboard analytics.
    • Legal and Structuring Expertise: The partner should possess deep experience with receivables purchase agreements, true-sale opinions, and cross-border trade finance if relevant. Our team can review legal terms to mitigate counterparty risk.
    • Supplier-Onboarding Support: A partner offering dedicated enrollment resources accelerates adoption and reduces internal strain.
    • Pricing Transparency: Evaluate the discount margin relative to your weighted average cost of capital (WACC) and confirm all fees are clearly disclosed.

    We run a structured RFP with weighted scoring. Early preparation of documents—financials, tax returns, credit application—mirrors the requirements Zaidwood Capital’s equipment financing resource outlines.

    Steps to Launch and Manage a Program

    With readiness confirmed and a partner selected, execution follows a phased roadmap. We guide clients through:

    1. Pilot Design: Select 5–10 friendly suppliers and run a controlled invoice-discounting cycle. Measure the impact on DPO and supplier satisfaction, then refine workflows.
    2. Legal Documentation: Finalize master receivables purchase agreements and supplier participation agreements. The onboarding documentation process mirrors the requirements for equipment financing—Zaidwood Capital can help you prepare the necessary financial information.
    3. Supplier Onboarding: Communicate program benefits, provide training, and assist with platform enrollment to drive adoption.
    4. Full Rollout: Expand to the broader supplier base, integrating governance and KPI monitoring.

    The table below outlines the full implementation roadmap, mapping each phase to key activities, timelines, and responsible parties.

    Supply Chain Finance Implementation Roadmap
    PhaseKey ActivitiesTypical TimelineResponsible Party
    Internal Readiness AssessmentAnalyze cash conversion cycle, supplier segmentation, credit rating4–6 weeksCFO / Treasury
    Partner SelectionRFP to funders and tech platforms; legal due diligence6–12 weeksProcurement & Legal
    Pilot ProgramOnboard top 10 suppliers, test workflows, validate savings8–12 weeksCross-functional team
    Full Rollout & GovernanceExpanding to full supplier base, establishing KPIs, ongoing risk monitoring6–12 monthsTreasury & Operations

    Ongoing governance tracks KPIs like DPO improvement, supplier adoption rate, and cost-of-funds versus WACC, with periodic risk reviews. This content is educational, not investment advice. To discuss your implementation, we invite you to Book A Call.

    Mitigating Risks and Ensuring Success in Supply Chain Finance Programs

    As companies expand their supply chain financing initiatives, the complexity of managing counterparties, operations, and regulatory landscapes introduces a range of risks that can undermine program stability. We understand that a structured approach to identifying and mitigating these risks is essential for building lasting SCF resilience. The following table outlines the primary risk categories, along with their concrete manifestations and proven mitigation strategies.

    Risk Category Description Examples Mitigation Strategy
    Counterparty Risk Buyer payment default or credit downgrade Default, rating decline Credit analysis, diversification, credit insurance
    Operational Risk Process failures, IT disruptions, invoice errors Platform outage, data errors Dual-approval workflows, disaster recovery testing
    Legal & Regulatory Risk Non-compliance with securities/tax laws Misclassification, tax challenges Legal counsel, SEC monitoring, ICMA guidelines
    Technology & Cybersecurity Risk Data breaches, hacking, integration gaps Ransomware, data leak Cybersecurity audits, encryption, vendor assessments

    While these targeted measures address distinct vulnerabilities, truly robust supply chain financing programs require an integrated risk management framework. Counterparty due diligence must be paired with operational resilience so that a single buyer default does not cascade through the entire supply network. Similarly, legal compliance—guided by standards from the International Capital Market Association (ICMA)—should be embedded alongside aggressive cybersecurity protocols. Implementing regular audits and engaging specialized cyber security consulting services can help fortify the SCF platform against evolving digital threats.

    Continuous monitoring and adaptive governance are what keep risk controls effective over time. We recommend stress testing exposure under adverse scenarios, conducting periodic independent audits of processes and technology, and updating governance structures to reflect new threats. By embedding proactive oversight into the program’s DNA, companies can move from reactive firefighting to sustained resilience. This forward-looking posture not only safeguards capital flows but also strengthens the confidence of suppliers and investors alike, setting the stage for scalable growth.

    Common Questions About Supply Chain Financing

    With foundational concepts in place, we turn to the questions businesses most often ask about supply chain financing.

    What exactly is supply chain financing?

    Supply chain financing—also called reverse factoring—is a buyer-led program. The buyer’s stronger credit standing lets suppliers collect early payment at a lower cost than traditional borrowing.

    How does the process work step by step?

    First the buyer approves invoices. Then a financial institution pays the supplier early, deducting a small fee. Finally the buyer remits the full invoice amount to the institution on the original due date.

    How does supply chain funding differ from factoring?

    Factoring is initiated by the supplier and can be more expensive. Reverse factoring, in contrast, relies on the buyer’s credit quality and happens only with the buyer’s direct participation.

    Who qualifies for these supply chain funding programs?

    Suppliers need approved invoices from a participating buyer. They also must complete the financing platform’s know-your-customer verification before accessing the early-payment facility.

    Having addressed the most frequent questions, the next stage is understanding how to put this knowledge into action.

    Strategic Considerations for Corporate Finance Leaders

    Corporate finance leaders should view M&A as a strategic growth lever, not just a transaction. Supply chain financing unlocks working capital and strengthens liquidity without adding traditional debt. The right mix of mezzanine, venture debt, and equity aligns capital structure with company stage and goals. Comprehensive due diligence—financial, legal, operational, human capital—flags risks and value drivers before any deal. Tailored advisory matches financial strategy to corporate objectives, and our network of 4,000+ investors and $15B+ capital accelerates deal flow and improves terms. Once strategic direction is clear, execution becomes the priority.

    This article was researched and written with the assistance of AI tools.

    Resources

  • Best Equipment Financing for Small Business in 2026

    Best Equipment Financing for Small Business in 2026

    Table of Contents

    Equipment Financing Fundamentals for Business Growth

    Beyond equity and working capital, equipment financing offers a targeted way to fund physical assets. This type of loan is secured by the equipment itself, allowing businesses to purchase manufacturing machinery, medical devices, or fleet vehicles without draining cash reserves. Typical loan terms run from three to seven years with fixed interest rates, and the lender retains a lien until the final payment—at which point the borrower owns the asset outright, distinguishing it from a lease where ownership does not transfer.

    Choosing equipment financing over an outright cash purchase preserves working capital and enables firms to upgrade technology faster. A manufacturer can modernize production lines, a healthcare practice can add advanced diagnostic tools, and a logistics company can refresh its delivery fleet while smoothing cash flow. According to the U.S. Small Business Administration, weighing the lease-versus-buy decision carefully helps protect liquidity and supports smarter growth investments.

    We guide clients through these decisions through our debt advisory practice. We evaluate lender terms, compare fixed-rate offerings, and structure equipment capital solutions that align with a company’s broader financial goals. Where appropriate, we design asset-based lending for equipment or blended packages to maximize flexibility without sacrificing long-term health.

    When conventional bank loans fall short, we connect clients to global lending services that open access to a wider institutional capital network, providing a bridge to the next stage of capital formation.

    Distinguishing Equipment Financing from Leasing and Other Capital Solutions

    Not all capital solutions are equal. Equipment financing, leasing, cash purchases, and term loans each affect ownership, working capital, and tax treatment differently.

    Equipment Financing vs. Equipment Lease: Structural Differences

    Equipment financing involves a loan secured by the equipment itself, leading to ownership after the final payment. Conversely, an equipment lease grants usage rights for a fixed term; the lessor keeps ownership, and you either return the gear or buy it at term end. Financing uses an interest rate (APR), while leasing uses a lease factor—making it critical to understand equipment leasing vs financing for accurate cost comparisons. Under GAAP, a financed purchase is classified as a capital lease (asset plus liability on the balance sheet); operating leases, previously off-balance-sheet, now fall under ASC 842 for leases longer than 12 months, requiring recognition. Typical terms for financing range from 2 to 7 years, whereas operating leases often last 1 to 5 years.

    Equipment Financing vs. Cash Purchase vs. Term Loan

    Beyond leasing, businesses frequently compare equipment financing with cash purchases and term loans. The primary differentiator is working capital: financing spreads cost over time, while cash purchases drain liquidity immediately, and term loans may dilute general borrowing capacity.

    CriterionEquipment FinancingEquipment LeaseCash PurchaseTerm Loan
    Ownership at End of TermYesNo (or buyout option)YesYes
    Working Capital ImpactLow (monthly payment)Low (monthly payment)High (full cost upfront)Low (monthly payment)
    Tax TreatmentDepreciation + Sec. 179Lease payments deductibleDepreciation + Sec. 179Depreciation + interest
    Typical Term2–7 years1–5 yearsN/A1–10 years
    Best ForLong-lived, high-cost equipmentRapid-tech-change gearLow-cost, disposable itemsBundled equipment + working capital

    As the table illustrates, both equipment financing and term loans preserve working capital through monthly payments, but financing is purpose-built for asset acquisition. By contrast, term loans can bundle equipment with other needs, and cash purchases eliminate ongoing obligations but tie up capital. Tax advantages also differ significantly—consult a tax professional to maximize benefits. Annual equipment financing volume exceeds $1 trillion in the U.S. market.

    When Each Option Makes Strategic Sense

    We recommend equipment financing for long-lived, high-cost assets like manufacturing machinery where ownership and depreciation benefits are key. Leasing suits rapid-tech-change equipment, such as IT servers or medical diagnostic devices, where obsolescence risk is high. Cash purchases are ideal for low-cost, disposable items that don’t justify financing overhead. A term loan makes strategic sense when you need to bundle equipment acquisitions with working capital or other operational expenses, giving you a single, flexible facility. Understanding these distinctions helps you choose the right capital structure—now let’s explore how Zaidwood Capital can streamline your equipment financing.

    Working Capital Preservation, Documentation Requirements, and Seasonal Structuring

    How Equipment Financing Preserves Working Capital

    Rather than tying up substantial cash reserves in a large capital expenditure, we help businesses explore equipment financing as a way to retain liquidity for core operations. By keeping cash on hand, firms can respond to market opportunities without delay and maintain the financial flexibility to invest in growth.

    Documents Typically Required to Qualify

    • Equipment invoice or quote shows the asset, cost, and specifications.
    • Business financial statements covering the last two to three years—income statements and balance sheets.
    • Tax returns, usually two to three years of both business and personal filings.
    • Business plan or use-of-funds statement explains how the equipment will drive revenue.
    • Personal guarantee details are commonly required for closely held or newer enterprises.
    • Proof of insurance confirms the collateral is protected against loss or damage.

    Seasonal and Deferred Payment Structures

    For businesses with pronounced seasonal sales cycles, standard monthly payments can strain cash flow during slow periods. Many lenders structuring equipment financing accommodate cyclical revenue by allowing higher installments in peak months and reduced or skipped payments in off-peak months, or by offering a deferred first payment.

    Debt Advisory Support from Zaidwood Capital

    Our debt advisory team works closely with companies to design equipment financing solutions that match their unique cash flow cycles. Leveraging a network of over 4,000 institutional investors, we identify lenders who can offer seasonal, deferred, or flexible payment structures.

    Tax Benefits and Accelerated Depreciation Advantages in Equipment Financing

    Section 179 Deduction Fundamentals

    Under Section 179 of the Internal Revenue Code, businesses may elect to deduct the full purchase price of qualifying equipment in the year it is placed in service. This applies whether you purchase equipment outright or finance it, provided the asset is used more than 50% for business.

    Bonus Depreciation and MACRS

    Bonus depreciation provides immediate tax shields, while MACRS allows for systematic recovery of costs over time. Equipment financed through loans qualifies for both, meaning tax advantages begin while the asset is being paid off.

    Interest Deductibility on Financed Equipment

    The interest component of equipment loan payments is generally deductible as ordinary business interest, subject to the limitations of Section 163(j).

    Integration with Full-Cycle Due Diligence from Zaidwood Capital

    Our full-cycle due diligence evaluates the tax implications of equipment financing as part of broader capital advisory engagements, modeling the interplay between Section 179, bonus depreciation, and interest deductibility.

    Advanced Structuring: Mezzanine Debt, Venture Debt, and Asset-Based Lending for Equipment

    Tax FeatureEquipment FinancingLeasingCash Purchase
    Section 179 EligibilityYes (if financed)NoYes
    Bonus DepreciationYes (2024: 60%)N/AYes (2024: 60%)
    Interest DeductionYesN/ANo

    Mezzanine Debt for Large Equipment Acquisitions

    Mezzanine debt fills the gap when senior lenders reach their limits, typically for deals over $5 million. It is a subordinated instrument with higher interest rates and occasional equity kickers.

    Venture Debt for Technology and Growth-Stage Equipment Needs

    Venture debt provides growth-stage companies with non-dilutive capital for specialized equipment like lab apparatus and server clusters, usually structured as a loan with warrants.

    Asset-Based Lending Against the Equipment Pool

    Asset-based lending (ABL) allows companies to use owned machinery as collateral for a revolving credit facility, typically lending 50–75% of the orderly liquidation value of the asset pool.

    Frequently Asked Questions About Equipment Financing

    Equipment financing vs. leasing?

    Equipment financing is a loan to purchase equipment you later own, while a lease requires returning the asset.

    Preserving working capital?

    It spreads costs over monthly payments, preserving working capital instead of making a large upfront purchase.

    Required documents?

    We generally require business financial statements, tax returns, bank statements, and equipment details.

    Seasonal payments?

    We can structure seasonal or deferred payment plans that align with your cash flow during low-revenue periods.

    Tax benefits?

    Financing may provide tax advantages such as Section 179 or interest deductions.

    Your Next Steps with Equipment Financing

    For equipment financing that aligns with your business objectives, our Debt Advisory team provides the expertise to structure a solution tailored to your needs. Every engagement begins with a conversation.

    Resources

  • Global Lending Services Alternatives: Key Options for Borrowers

    Global Lending Services Alternatives: Key Options for Borrowers

    The provided HTML content has been validated. The structure adheres to the required order (TOC, Content, Resources, Style Block), all Gutenberg blocks are properly closed, anchor IDs are consistent with the TOC, and no markdown residue remains. “`html

    Table of Contents

    Global Lending Services for Corporate Growth

    Beyond M&A, our global lending services empower corporations to fund growth initiatives without diluting equity. With access to 4,000+ institutional investors and over $15 billion in deployable capital, we connect clients to tailored financing. Our advisory has supported over $24.4 billion in aggregate transaction volume, demonstrating our ability to structure complex debt solutions.

    • Mezzanine financing to bridge capital gaps during expansion
    • Venture debt for high-growth companies seeking non-dilutive capital
    • Equipment financing and asset-based lending to unlock liquidity from tangible assets

    We streamline transactions by leveraging deep institutional relationships and proprietary technology to accelerate funding timelines. Our lending solutions complement our mergers and acquisitions advisory to structure acquisition financing, working capital lines, and growth capital, while also supporting recapitalizations and special situations.

    Each engagement is custom-quoted to your specific growth needs. Our Full-Cycle M&A and capital advisory approach ensures a cohesive financing strategy. We invite you to Book A Call to discuss how our lending solutions can accelerate your international expansion. For equity-side solutions, see the following section on capital raising.

    Securities are offered through Finalis Securities LLC. Zaidwood Capital is not a registered broker-dealer. This is for informational purposes only.

    Understanding Global Lending Services

    What Are Global Lending Services?

    Global lending services encompass a broad range of cross-border financing solutions that enable corporations to fund growth, execute acquisitions, and manage working capital. These services include mezzanine debt, venture debt, asset-based lending, and cash-flow financing, each tailored to different corporate needs and risk profiles. Unlike traditional domestic bank loans, global lending services connect borrowers with institutional investors and specialty lenders across international markets, offering flexible structures and tailored terms that may not be available locally. According to Federal Reserve economic research, U.S. real GDP grew at an annualized rate of 3.8% in the second quarter of 2025, reflecting strong corporate demand for expansion capital that these international lending solutions help satisfy. As companies navigate complex global markets, they increasingly turn to these instruments to fuel strategic initiatives without diluting equity unnecessarily. The Federal Trade Commission’s business guidance emphasizes compliance and disclosure standards governing global lending, underscoring the need for rigorous advisory support. Navigating these instruments effectively often requires the support of a boutique M&A advisory firm.

    Role of Boutique M&A Advisory in Global Lending

    At Zaidwood Capital, we act as a Full-Cycle M&A and capital advisory partner, connecting corporate clients with the global lending services that match their strategic needs. Our institutional network encompasses more than 4,000 global investors and over $15 billion in deployable capital, and we have advised on over 300 transactions totaling $24.4 billion in aggregate volume. We differentiate ourselves through full-cycle due diligence that covers financial, legal, operational, commercial, IT, and human capital assessments, ensuring every lending structure is robust and compliant. Our process evaluates regulatory requirements—including FDIC banking oversight—to verify that cross-border financing adheres to applicable banking regulations. Access to proprietary data resources like our Deal Vault and Sovereign Data Nexus enhances our ability to identify the most appropriate lending partners. This holistic approach equips us to guide clients through the full spectrum of debt instruments.

    Types of Debt Financing Available

    Global lending encompasses a spectrum of debt instruments, each designed to address specific corporate objectives and risk profiles.

    • Mezzanine debt – Subordinated, often convertible financing that bridges the gap between senior debt and equity, commonly used in acquisitions and buyouts.
    • Venture debt – Non-dilutive capital tailored for high-growth, venture-backed companies to extend runway and fund expansion without surrendering equity.
    • Equipment financing – Asset-backed loans or leases that allow companies to acquire machinery, vehicles, or technology with the purchased asset serving as collateral.
    • Asset-based lending – Revolving credit lines secured by a company’s balance-sheet assets such as accounts receivable, inventory, or real estate, providing flexible working capital.

    Each type serves a distinct purpose within a company’s capital structure, and our advisory team helps determine the most appropriate combination based on the client’s operational profile, growth stage, and market conditions. Understanding these financing options is the first step in designing a capital strategy—our next section explores how we evaluate and approve these instruments in practice.

    Key Benefits of Global Lending Services through Boutique Advisory

    Our global lending services deliver three distinct advantages that empower companies to access diverse capital sources, optimize financial structures, and close transactions efficiently.

    Access to a Broad Investor Network

    Through our global lending services, clients gain immediate access to a curated network of over 4,000 institutional and private investors, representing more than $15 billion in deployable capital. This extensive Rolodex, combined with our $24.4 billion in aggregate transaction volume, ensures we can source financing across asset classes and geographies. By leveraging proprietary data systems like the Sovereign Data Nexus, we match borrowers with lenders that understand specific industry dynamics and growth stages — opening doors that traditional bank relationships often cannot. Moreover, our deep relationships with family offices, sovereign wealth funds, and endowments enable tailor-made international lending solutions for cross-border capital needs. Every mandate benefits from a quantitative and qualitative investor matching process that considers not only cost but strategic alignment, shortening the path to committed capital. This broad network is a cornerstone of our full-cycle M&A and capital advisory model, delivering a tangible advantage in securing capital for growth and complex transactions.

    Tailored Capital Structure Optimization

    Our debt advisory team builds financing structures that align precisely with a company’s cash flow cycles, growth objectives, and risk tolerance. In global debt advisory, we evaluate mezzanine, venture debt, equipment financing, and asset-based lending to craft a capital stack that preserves equity while maintaining liquidity for strategic initiatives. By integrating forward-looking financial models and sensitivity analysis, we help clients avoid over-leverage and maintain healthy covenants. Crucially, we help you navigate capital market regulatory policy to structure debt that meets your risk and compliance needs — an essential component for cross-border transactions where regulatory frameworks differ markedly. Our full-cycle due diligence ensures each capital layer works in concert, reducing cost and financial strain. The result is a tailored solution that optimizes capital efficiency and supports sustainable growth.

    Faster Execution and Personalized Service

    Unlike bulge-bracket banks where deal processes can be slowed by competing internal interests and multiple layers of approval, our boutique structure ensures a streamlined, hands-on approach. Each engagement is led by senior bankers with decades of experience who remain directly involved from initial analysis through closing, reducing friction and miscommunication. Our proprietary Velocity Matrix integrates digital marketing and capital markets expertise to accelerate deal timelines — often achieving close in under 60 days for mid-market transactions. By coordinating strategic documentation, due diligence, and investor introductions under one roof, we eliminate the handoff delays that plague larger institutions. This personalized model adapts quickly to market shifts, delivering a relationship-driven experience that prioritizes your objectives over institutional process. For business owners and fund managers, this translates into lower transaction fatigue and a higher probability of reaching the finish line on acceptable terms.

    How Global Lending Services Work with Zaidwood Capital

    With a team that includes former specialists from bulge-bracket institutions such as Goldman Sachs, JPMorgan, and Morgan Stanley, Zaidwood Capital’s global lending services follow a structured, multi-stage process designed to match businesses with the right institutional lenders from our network of more than 4,000 global investors.

    Engagement and Information Gathering

    Our engagement begins with a comprehensive consultation during which clients submit key documentation including financial statements, a business plan, and detailed funding objectives. Our team of experienced venture capital consultants works closely with clients to gather the required documentation and define clear funding objectives. This information-gathering phase allows us to understand the client’s industry, growth stage, and the precise capital structure needed.

    Qualification and Matching with Investors

    Once we have a thorough understanding of the client’s financial position and objectives, we move to qualification. Using our proprietary Deal Vault and an extensive investor rolodex, we assess the client’s profile against criteria for various debt products. We match each client with institutional lenders whose investment mandates align with their industry, deal size, and risk appetite.

    Due Diligence and Transaction Execution

    During due diligence—a core phase of our global lending services—we conduct a full-cycle review covering financial, legal, operational, commercial, IT, and human capital aspects. We coordinate with legal counsel and auditors to identify and mitigate any risks. After resolving potential issues, we assist in negotiating term sheets and finalizing transaction documents. It is important to clarify that Zaidwood Capital does not extend loans directly; we advise and facilitate introductions to institutional lenders. All securities transactions are conducted through Finalis Securities LLC, a separate entity and FINRA member.

    Best Practices for Securing Global Lending

    Preparing a Comprehensive Information Package

    • Audited financial statements covering the last three fiscal years.
    • Cash flow projections spanning three to five years.
    • A detailed rationale for the intended use of funds.
    • A comprehensive business plan.

    Understanding Regulatory and Compliance Requirements

    For companies pursuing global lending services, understanding and meeting regulatory requirements is non-negotiable. Cross-border transactions must comply with SEC, FINRA, and ICMA standards. For authoritative guidance on fair lending and disclosure practices, we direct clients to the FTC business guidance.

    Partnering with an Experienced Advisory Firm

    When seeking global lending services, partnering with an experienced advisory firm can mean the difference between a stalled process and a successful closing. At Zaidwood Capital, we offer a boutique M&A and capital advisory platform designed to streamline the funding journey.

    Capitalize on Global Lending Opportunities with Zaidwood Capital

    Global lending markets remain highly fragmented, but through our global lending services advisory we help clients identify and structure cross-border financing opportunities. Backed by a network of over 4,000 institutional investors and family offices, Zaidwood Capital provides integrated debt and equity advisory that spans jurisdictions.

    Resources

    “`
  • Best International Wealth Management Firms for 2026

    Best International Wealth Management Firms for 2026

    Table of Contents

    Understanding International Wealth Management Firms for Global Capital Solutions

    In the international wealth management space, international wealth management firms typically focus on asset allocation and portfolio construction, but businesses pursuing cross-border growth often require a more transactional, capital-intensive partner. Global capital solutions encompass capital raising, strategic M&A, and debt and equity structuring\u2014far more than passive portfolio oversight, requiring deep execution capability.

    Unlike passive money management international services, international wealth management firms often emphasize capital preservation, whereas Zaidwood Capital delivers full-cycle M&A and capital advisory capabilities. While the wealth management outlook 2025 emphasizes return on managed assets, our approach emphasizes execution. Our institutional network of 4,000+ global investors and $15B+ in available capital enables us to structure and close complex cross-border transactions. This capital flows directly into venture capital, private equity, credit, and alternative investments, enabling clients to scale AUM and pursue transformative acquisitions. At the intersection of capital markets and digital execution, our Velocity Matrix accelerates timelines and unlocks opportunities that traditional global wealth managers often overlook, delivering the speed and precision that modern cross-border deals demand, all while maintaining the rigorous diligence that institutional counterparties expect.

    This active, transaction-oriented approach distinguishes us from conventional global asset management, which makes our approach particularly effective for the capital formation challenges discussed next. We invite you to speak with our team to explore how Zaidwood Capital can transform your cross-border strategy.

    Core Services and Structures of International Wealth Management Firms

    International wealth management firms operate through several distinct service models, each tailored to different client profiles and cross-border needs. From private banks and independent wealth managers to multi-family offices and boutique capital advisors, understanding these structures is essential for high-net-worth individuals, families, and institutions engaged in money management international and global asset management.

    Comparison of International Wealth Management Service Models
    Service ModelMinimum Client AssetsCore ServicesCross-Border CapabilitiesFee StructureTypical Client Base
    Private Bank$1M\u2013$5MWealth planning, lending, investment management, estate planningThrough global offices, often limited to advisory only in certain jurisdictionsAsset\u2011based fees + transaction commissionsHigh\u2011net\u2011worth individuals, family offices
    Independent Wealth Manager$500K\u2013$2MDiscretionary asset management, financial planning, tax optimizationVaries by firm; often partner with custodians for multi-currency exposureFee-only (AUM % or flat retainer)Affluent professionals, small family offices
    Multi-Family Office$10M\u2013$50MComprehensive wealth management, concierge services, governance, philanthropyDeep expertise in multiple jurisdictions, often with dedicated international teamsRetainer + performance-based feesUltra-high-net-worth families with complex global structures
    Boutique Capital AdvisorNo fixed minimum; project-basedM&A advisory, capital raising, due diligence, strategic documentationExtensive network of 4,000+ institutional investors; $15B+ deployable capitalSuccess-based retainer or retainer + success feePrivate equity, family offices, sovereign wealth funds, VC firms

    Cross-Border Investment Strategies and Regional Allocation

    Regional Allocation Models Across North America, Europe, and Asia

    Cross-Border Investment Strategies by Region
    RegionTypical Asset AllocationRegulatory ComplexityCommon VehiclesFirm Expertise RequiredRisk Level
    North AmericaEquities 50%, Fixed Income 30%, Alternatives 20%Moderate (SEC, FINRA)ETFs, mutual funds, SMAsFull serviceModerate
    EuropeEquities 40%, Fixed Income 35%, Alternatives 25%High (MiFID II, AIFMD)UCITS, AIFsLocal regulatory knowledgeModerate to high
    Asia-PacificEquities 55%, Fixed Income 20%, Alternatives 25%High (MAS, HKMA)QDLP, QFII, ETFsJoint venturesHigh

    Regulatory Considerations Across Jurisdictions

    Money management international operations must navigate a complex web of securities laws and tax treaties. Compliance with FATCA and CRS is mandatory for institutional excellence.

    Capital Access in Emerging Markets

    Selecting the Right International Wealth Management Firm: Criteria and Process

    Key Evaluation Metrics: Track Record, Global Reach, and Specialization

    Due Diligence Steps for High-Net-Worth Clients

    Leveraging Capital Networks: The Zaidwood Advantage

    Advanced Capital Strategies for Ultra-High-Net-Worth Clients

    Frequently Asked Questions About International Wealth Management Firms

    Your Next Steps in Global Capital Advisory

    Focus on institutional execution to drive cross-border value.

    Resources

  • Best Manufacturing Consulting for 2026 Growth

    Best Manufacturing Consulting for 2026 Growth

    Table of Contents

    Mastering Manufacturing Consulting Essentials

    Mastering manufacturing consulting begins with our integrated Full-Cycle M&A and capital advisory services. We connect manufacturing firms to over 4,000 global investors, addressing industry challenges with streamlined growth strategies, as per Zaidwood Capital’s proprietary internal guidance.

    Key essentials include Streamlining Transactions via proprietary data access and full-cycle due diligence—financial, operational, and commercial. Our capital introductions facilitate equity and debt advisory, drawing on $24.4B+ aggregate transaction volume from Zaidwood Capital’s internal examples of precision in manufacturing deals.

    We enable clients to integrate smart manufacturing trends through capital raising and strategic corporate finance consulting, powered by our Velocity Matrix and Precision Catalyst approaches, per internal best practices.

    Book A Call for custom advisory tailored to your needs. Investments involve risk; past performance does not guarantee future results.

    1. Lead Digital Transformation

    As pioneers in Financial Services 3.0, we lead digital transformation through our Velocity Matrix for manufacturing consulting clients. Positioned as a Precision Catalyst, Zaidwood Capital LLC guides manufacturers toward smart technologies and operational excellence.

    Our alignment with initiatives like the NIST MEP CESMII partnership accelerates client adoption. As per an authoritative announcement from the National Institute of Standards and Technology (NIST), this government-industry collaboration advances smart manufacturing technologies, technology transfer, training via CESMII’s platforms, and funding for small and medium-sized manufacturers.

    NIST MEP‘s client impact, underscored by GenEdge industry analysis of the Client Impact Survey, demonstrates gains in sales growth, cost savings, job creation, and innovation. We connect these advancements to our full-cycle M&A advisory and capital formation services.

    Leverage our institutional network for Sovereign Data Nexus-enabled transformations. Book A Call with our team today to start. This foundation enables seamless capital formation—explore next.

    2. Explore Top Firms Directory

    Building on these insights into manufacturing opportunities, we guide you to top firms via the official directory. MEP centers are federally funded organizations that deliver manufacturing consulting to small and medium-sized manufacturers, as explained by ConnSTEP, an active MEP center participant. These centers offer tailored advisory on process improvements, workforce training, and technology adoption to drive competitiveness.

    The National Institute of Standards and Technology (NIST) maintains the authoritative listing of all 51 MEP centers across U.S. states and territories, complete with addresses, contacts, and service descriptions. Users can search by state or service type, such as supply chain optimization or cybersecurity for manufacturers, to identify local experts in consulting support for manufacturers. We recommend leveraging this directory to pinpoint partners accelerating manufacturing growth via targeted manufacturing advisory. Visit the MEP centers directory to discover NIST-backed expertise in operational enhancements.

    Explore the MEP centers directory now to connect with top firms. After identifying partners, contact us for capital advisory support using our Velocity Matrix.

    3. Adopt Smart Technologies

    Building on optimized processes, smart technologies provide the digital edge in manufacturing consulting. According to proprietary internal FAQ guidance from Zaidwood Capital, these innovations drive efficiency gains despite barriers like high costs, skills gaps, and legacy systems.

    IoT for real-time monitoring enables continuous equipment tracking in production lines, reducing downtime through data-driven alerts. AI for predictive analytics forecasts maintenance needs, optimizing workflows via pattern recognition in manufacturing operations consulting. Automation for process optimization streamlines repetitive tasks, as expert internal advisory content from Zaidwood Capital notes, boosting throughput with robotic integration.

    We recommend this four-step adoption roadmap from Zaidwood Capital FAQs:

    • Audit current systems to identify gaps.
    • Select scalable solutions like IoT and AI.
    • Integrate with existing operations via expert partners.
    • Monitor ROI metrics through pilot projects and training.
    Vertical process flow diagram illustrating four-step roadmap for smart technology adoption in manufacturing: audit systems, select solutions, integrate operations, monitor performance.
    Four-step roadmap for adopting smart technologies in manufacturing

    These steps align smart tech with our Full-Cycle M&A and capital advisory for funding upgrades. Leverage Zaidwood’s Velocity Matrix for accelerated implementation. Not investment advice—consult advisors; investments involve risk. Secure capital for these innovations through our Full-Cycle M&A advisory—Book A Call to start.

    4. Assess Reputation Reviews

    Beyond financial checks, reputation reveals execution reliability in manufacturing consulting. We advise evaluating providers through verified client feedback and independent benchmarks to ensure partners deliver on promises for capital advisory mandates.

    Follow this three-step process:

    1. Gather client testimonials from verified sources like Google or Clutch.
    2. Cross-reference with independent surveys, such as the NIST MEP client impact survey, conducted by third parties to measure outcomes like sales growth and cost savings, as explained by GenEdge.
    3. Analyze patterns for themes like on-time delivery and efficiency gains.

    Prioritize surveys from bodies like NIST MEP that track sales growth, cost reduction, and ROI for manufacturing firms. Avoid sole reliance on self-reported reviews; objective data predicts transaction success in consulting for manufacturing sectors.

    With reputation confirmed via surveys, evaluate strategic fit next. Use these tools before engaging our Full-Cycle M&A and capital advisory services—Book A Call today.

    5. Scale with Capital Access

    Once operations are optimized, secure capital to accelerate growth. We provide seamless capital access to fuel your growth, particularly for businesses seeking manufacturing consulting services. Our Capital Formation / Capital Raising connects clients to institutional LPs and over $15 billion in deployable capital, as detailed in Zaidwood Capital’s official FAQ guidance on capital solutions.

    We offer comprehensive Debt Advisory, including mezzanine, venture debt, equipment financing, and asset-based lending. Equity Advisory provides growth equity and liquidity solutions. Through Capital Introductions and Institutional LP Placement, clients access our Deal Vault and Investor Rolodex with 4,000+ global investors and $24.4 billion in aggregate transaction volume. Our Velocity Matrix delivers full-cycle support for faster execution.

    Book A Call to discuss custom capital solutions tailored to your manufacturing scale-up needs. With capital in place, prepare for optimal exits. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    6. Optimize Debt Structures

    Complementing equity with optimized debt, we at Zaidwood Capital streamline capital structures to reduce costs and align with growth goals. For clients seeking manufacturing consulting, our debt advisory services enhance efficiency through tailored non-dilutive financing and operational efficiency improvements for manufacturers.

    We offer key debt options:

    • Mezzanine debt: Subordinated financing blending debt and equity features for flexible capital without full equity dilution.
    • Venture debt: Non-dilutive funding for high-growth companies post-equity rounds, with repayment tied to revenue milestones.
    • Equipment financing: Leverages machinery as collateral for asset-heavy manufacturing sector consulting clients.
    • Asset-based lending: Utilizes receivables or inventory to unlock liquidity.

    Through our institutional network, we secure competitive terms, as outlined in Zaidwood Capital’s proprietary FAQ knowledge base. This pairs with equity advisory for a full capital stack.

    Book A Call for a custom debt optimization assessment. Not investment advice — consult advisors.

    7. Tap Investor Network

    Building on our full-cycle capabilities, we empower you through the Tap Investor Network. Tap into our exclusive Investor Network of 4,000+ global institutions with $15B+ deployable capital, perfect for manufacturing consulting firms pursuing capital raises or M&A.

    Our proprietary platform, detailed in Zaidwood Capital’s raise portal, delivers instant capital introductions via the Deal Vault and Investor Rolodex. This accelerates Velocity Matrix execution for services like Capital Formation and Institutional LP Placement. Businesses in the manufacturing sector consulting space benefit from rapid access to growth equity and strategic opportunities, backed by our $24.4B+ aggregate transaction volume.

    Activate personalized access by Book A Call today. Ideal for sectors like consulting in manufacturing seeking efficient deal execution.

    Contact us to tap the network today for a custom quote. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. This network kickstarts your transaction—discover the full process next.

    8. Execute Due Diligence

    Following agreement on key terms, we execute comprehensive due diligence using our proprietary Velocity Matrix for accelerated insights in Full-Cycle M&A and capital advisory, including manufacturing consulting deals seeking capital or M&A.

    Per Zaidwood Capital’s official internal guidance on full-cycle due diligence procedures, our process covers six key categories:

    • Financial: Balance sheet audits and cash flow projections to validate fiscal health.
    • Legal: Contract reviews and compliance checks to mitigate regulatory risks.
    • Operational: Supply chain efficiency and process optimizations, such as in smart manufacturing transactions and manufacturing consulting firms’ operational scalability.
    • Commercial: Market positioning and customer validations for growth potential.
    • IT: Cybersecurity audits and data integrity assessments.
    • Human Capital: Talent assessments and culture fit evaluations.

    Integrating our 4,000+ investor network and $24.4B+ transaction experience via Precision Catalyst methodologies mitigates risks, maximizes value, and advances to seamless transaction closing. Book A Call to discuss tailored execution. Not investment advice — consult your legal, tax, and financial advisors before making decisions.

    Partner for Manufacturing Success

    In manufacturing, success demands a trusted partner—we deliver manufacturing consulting expertise. We partner with manufacturing leaders for success using our Precision Catalyst approach to accelerate growth via targeted capital and M&A strategies.

    Our Full-Cycle M&A and capital advisory covers buy-side and sell-side mandates for plant expansions or divestitures. We raise capital from our 4,000+ global investor network and provide debt advisory for equipment financing. Zaidwood Capital’s internal resources confirm our $24.4B+ transaction volume in industrial sectors.

    We integrate smart manufacturing capabilities for operational scaling, leveraging AI predictive maintenance and digital twins to minimize downtime and boost efficiency by 20-30%, per Zaidwood Capital expertise. Our manufacturing consulting extends to specialized debt and equity solutions.

    Book A Call to explore how our Velocity Matrix streamlines your manufacturing journey. Not investment advice—consult your advisors.

    This article was researched and written with the assistance of AI tools.

    Resources