Zaidwood Capital

Tag: Corporate Finance

  • M&A Due Diligence Services: Complete Guide for 2026

    M&A Due Diligence Services: Complete Guide for 2026

    Table of Contents

    Essential Guide to M&A Due Diligence Services

    Building on the role of investment banks in M&A, a critical component of any transaction is the comprehensive evaluation delivered by M&A due diligence services. Due diligence is the detailed examination of a target company’s financials, operations, legal standing, and strategic fit to identify potential risks and validate the transaction thesis.

    The process encompasses four main pillars: financial due diligence, which scrutinizes historical and projected financial performance; legal due diligence, which reviews contracts, intellectual property, and regulatory compliance; operational due diligence, which assesses internal processes and scalability; and strategic/commercial due diligence, which evaluates market positioning and synergy potential. While thorough, due diligence is a risk mitigation tool, not a guarantee of success.

    Zaidwood Capital, a Boutique M&A and Capital Advisory Firm, streamlines transactions—particularly the due diligence phase—by offering the Sovereign Data Nexus secure data room that enables controlled document exchange. As investment banks, we coordinate due diligence across financial, legal, and operational workstreams, acting as gatekeepers and advisors. Understanding what is an investment bank helps clarify how we structure and oversee each step of this rigorous process.

    By converting raw data into actionable insights, thorough due diligence empowers decision-makers to negotiate from a position of clarity. The following sections break down each type of due diligence and how boutique firms streamline them.

    Core Components of M&A Due Diligence

    The cornerstone of a successful transaction is a thorough due diligence process. When clients engage us for M&A due diligence services, we structure the review around five interconnected areas: Financial, Legal, Operational, Commercial, and Strategic. Each area addresses distinct risks and opportunities that collectively shape the investment thesis.

    Comparison Table: Key Diligence Areas at a Glance
    Diligence AreaFocusKey Questions Answered
    FinancialHistorical and projected financial statements, working capital, debt structureAre revenue and margin trends sustainable? Are there hidden liabilities?
    LegalContracts, litigation history, IP ownership, regulatory complianceAre there pending lawsuits or IP encumbrances? Do contracts contain change-of-control clauses?
    OperationalSupply chain, IT systems, workforce, facilitiesHow resilient is the supply chain? Are key person dependencies manageable?
    CommercialCustomer concentration, market competitiveness, sales pipelineAre top customers locked in or at risk? Is the revenue base diversified?
    StrategicFit with acquirer’s long-term plan, cultural alignment, synergy potentialWill the target accelerate or dilute the acquirer’s strategic objectives?

    Financial diligence scrutinizes historical and projected income statements, balance sheets, and cash flows to validate performance trends. We assess working capital adequacy, debt structure, and off-balance-sheet exposures that could mask hidden liabilities. The goal is to confirm that reported earnings translate into sustainable cash generation and to quantify any adjustments needed to normalize the target’s financial position.

    Legal diligence examines the target’s contract portfolio, litigation history, intellectual property ownership, and regulatory compliance. We pay special attention to change-of-control provisions that could trigger termination or consent rights. All legal and financial reviews are conducted in alignment with CFA Institute professional standards for objectivity and thoroughness, ensuring no material legal risk is overlooked.

    Operational diligence probes the resilience of the supply chain, the robustness of IT systems, and the composition of the workforce. We evaluate key person dependencies and facility redundancies that could disrupt post-close operations. Understanding these operational levers allows us to quantify integration risks and identify quick wins that enhance value from day one.

    Commercial diligence assesses customer concentration, the health of the sales pipeline, market competitiveness, and revenue diversification. By analyzing contract renewals and switching costs, we determine whether top customers are locked in or at risk of churn. A diversified revenue base reduces post-transaction volatility and strengthens the platform’s long-term growth trajectory.

    Strategic diligence evaluates how well the target aligns with the acquirer’s long-term plan, cultural values, and synergy potential. We map revenue and cost synergies to concrete integration milestones, ensuring that the deal advances the acquirer’s strategic objectives rather than diluting them. A systematic review across all five areas uncovers both hidden risks and value-creation opportunities.

    Each component warrants a deeper dive; in the following pages we examine the specific methodologies and best practices for each diligence area. Our approach, refined through extensive technology M&A experience as captured in our guide to tech transaction steps, ensures that no dimension of risk escapes scrutiny.

    In-Depth Process Walkthrough of M&A Due Diligence

    Now we examine the three phases that make up a comprehensive due diligence process. A walkthrough of our M&A due diligence services reveals how scoping, review, and integration work together to mitigate risk.

    Phase 1: Scoping and Data Room Preparation

    Comparison Table: Financial vs. Operational Due Diligence
    DimensionFinancial DiligenceOperational Diligence
    Primary goalValidate historical accuracy and future earnings capacityAssess the sustainability of operations and efficiency of processes
    Key documentsAudited P&L, balance sheet, cash flow, tax returnsSOPs, org chart, IT architecture, supplier contracts
    Typical teamCPAs, valuation analysts, FP&A specialistsOperations consultants, supply chain experts, HR specialists
    OutputQuality of earnings report, debt capacity analysisOperational risk matrix, integration readiness score

    Phase 1 begins with scoping sessions where our deal team and the buyer’s leadership jointly identify the value drivers and critical risk areas—such as customer concentration, key-person dependency, or regulatory exposure—that will shape the diligence agenda. From those discussions, we build a detailed data request list that typically includes multiple years of audited financial statements (P&L, balance sheet, cash flow), material customer and vendor contracts, IP registrations, employment agreements, and corporate governance documents. A secure virtual data room—our deal vault—is then deployed on our Sovereign Data Nexus platform. The environment is structured with a folder hierarchy that mirrors the diligence workstreams: financial, legal, commercial, and operations. We configure tiered access controls so that legal reviewers, for example, can only access contract folders, while financial analysts see only the finance section. We also align the workstream teams on review timelines, assign responsibilities, and confirm that all requested materials have been uploaded. This disciplined preparation is the foundation that makes the subsequent document review efficient and secure.

    Phase 2: Document Review and Issue Identification

    In Phase 2, our specialists simultaneously review financial statements, legal contracts, operational KPIs, and commercial agreements to surface risks and validate the target’s representations. Financial analysts verify historical earnings, working capital trends, and revenue quality by examining audited P&L, balance sheets, and tax returns, flagging any non-recurring items or accounting policy inconsistencies. Legal counsel scrutinizes customer and vendor contracts for change-of-control triggers, assignment restrictions, and indemnity provisions, and they review employment agreements for retention risks and non-compete enforceability. On the operational side, we assess KPIs such as revenue per employee, system uptime, and supply-chain resilience, comparing them against industry benchmarks to spot inefficiencies. Throughout the phase, we use the data room’s built-in Q&A module to submit targeted questions to the seller’s management; each response is logged and cross-referenced. This iterative process often brings hidden liabilities to the surface. The data room’s Q&A module tracks each query and response, and we cross-reference answers against the original documents to verify consistency. The issue log is shared with the buyer’s deal team in real time, enabling collaborative prioritization. As we illustrate in our complete guide on tech mergers and acquisitions, deep document review frequently uncovers unreported contingent liabilities or non-compliant IP assignments that can affect valuation. In regulated sectors, we also overlay compliance checks against FTC, CMS, and FCC standards, informed by our internal research on how regulatory shifts influence transaction risk. All identified issues are entered into a shared issue log, assigned severity ratings, and prioritized for the subsequent reporting phase.

    Phase 3: Reporting, Remediation, and Deal Integration

    In Phase 3, our team synthesizes all findings into a comprehensive diligence report, beginning with an executive summary that highlights the most critical risks and opportunities. The report segments findings by financial, legal, and operational dimensions, each with a severity rating. Red flags—such as excessive customer concentration, material litigation, or compliance exposures—are escalated immediately and can influence valuation adjustments or the inclusion of special indemnities in the purchase agreement. Our reporting delivers the core M&A due diligence services as actionable intelligence that shapes the client’s negotiation posture. We typically hold a findings review session with the buyer’s leadership to walk through every issue and agree on remediation priorities. To bridge the gap between diligence and post-close execution, we use our Velocity Matrix to translate key risks into a structured 100-day integration plan. Once the diligence report is finalized, the findings directly inform the negotiation of the purchase agreement and integration planning.
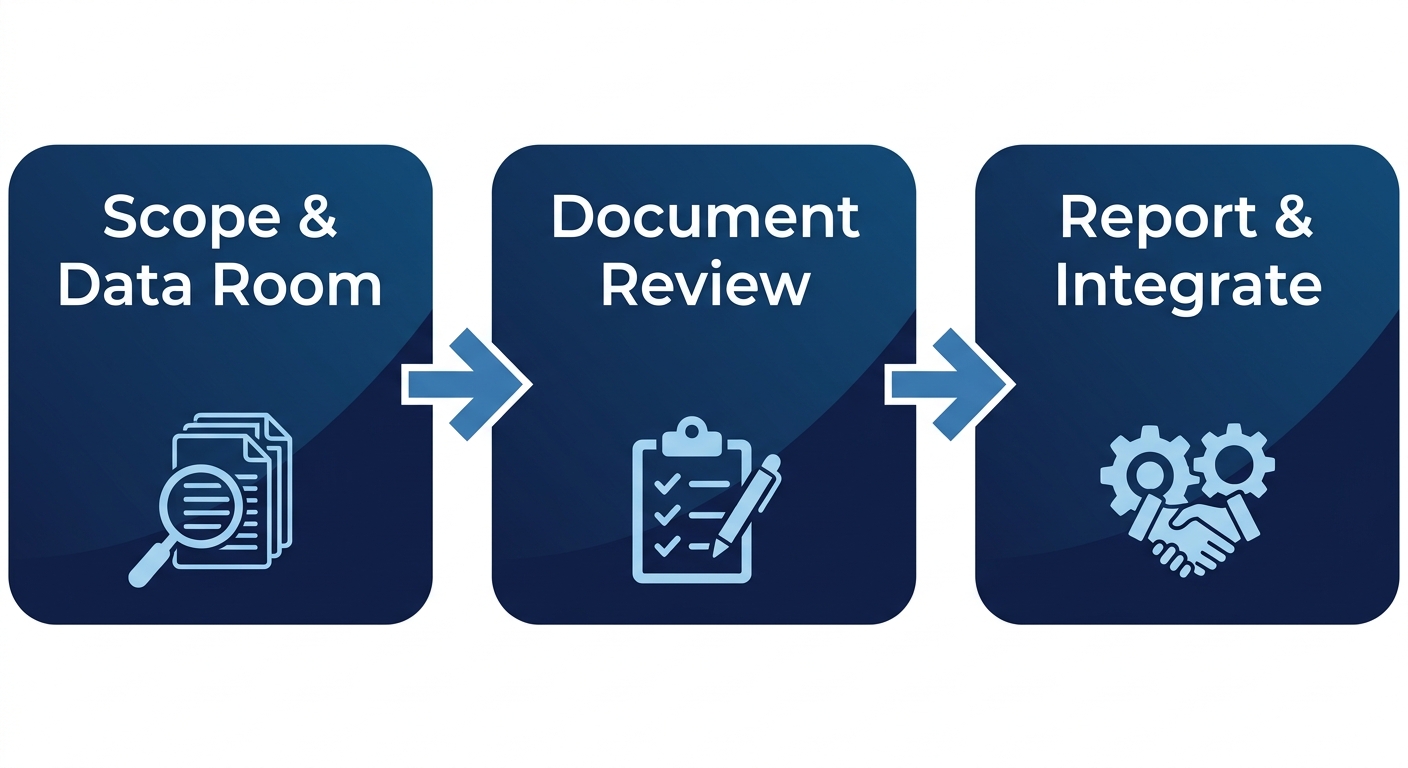
    M&A due diligence process flow diagram with three connected stages: scoping and data room preparation, document review and issue identification, and reporting with remediation and deal integration

    Due diligence process: Scoping, Review, Integration

    Practical Application of Due Diligence in M&A

    With the strategic importance of due diligence established, we now turn to its practical execution. When conducting due diligence in tech mergers and acquisitions, assembling the right team and timeline is critical. Our M&A due diligence services are anchored in a disciplined process that aligns financial, legal, and operational expertise to uncover risks and validate the deal thesis early.

    Assembling Your Diligence Team and Timeline

    A well-structured diligence engagement draws on three core roles: a financial advisor who leads the process—typically a boutique M&A firm like Zaidwood Capital—a legal counsel with deep M&A experience, and a technical or industry specialist who can assess operational and market realities. We converge these disciplines around a single checklist that maps every data request, interview, and verification step against a shared timeline.

    A sample 5-week timeline typically unfolds as follows:

    • Weeks 1-2 — Scoping and Information Request: Define the diligence scope, issue the initial document request list, and align client and target management on confidentiality protocols.
    • Weeks 3-4 — Intensive Review: Conduct document analysis, site visits, management interviews, and workstream-specific deep dives (financial, legal, operational, commercial).
    • Week 5 — Report Synthesis: Draft the due diligence report, isolate deal-breakers and conditions to closing, and present findings to the deal team.

    Pro Tip: Always verify key executives’ backgrounds before finalising the diligence timeline. Late-stage discoveries of litigation or misrepresentation can derail transactions, so we include these checks early.

    This collaborative staging keeps the entire team accountable and prevents last-minute surprises.

    Leveraging Data Rooms and Proprietary Tools

    A secure data room is a foundational piece of M&A diligence. Granular permissions, watermarking, and audit trails are non-negotiable. While basic cloud storage (Google Drive) works for small deals, most mid-market transactions demand virtual data room platforms like Intralinks or Ansarada with user-specific rights and detailed logs. For the highest-stakes cross-border scenarios, we rely on Zaidwood Capital’s Deal Vault, which leverages our Sovereign Data Nexus for air-gapped protection and end-to-end encryption.

    Comparison Table: Data Room Options for Due Diligence
    Provider TypeSecurity FeaturesIdeal For
    Basic cloud storage (e.g., Google Drive, Dropbox)Standard encryption, shared linksSmall, fast-moving deals where volume is low
    Virtual Data Room platforms (e.g., Intralinks, Ansarada)Granular permissions, audit trails, watermarkingMid-market M&A with multiple bidders
    Zaidwood Capital’s Deal Vault (private server)Air-gapped environment, Sovereign Data Nexus integrationComplex cross-border transactions demanding highest security

    Each tier matches deal complexity: basic for low-complexity asset sales, VDRs for multi-bidder auctions, and Deal Vault when sovereign-grade security is required.

    Beyond the data room, Precision Catalyst tracks investor engagement—document opens, time spent, repeat visits—flagging high-interest parties to accelerate follow-ups. This data-driven approach concentrates our M&A due diligence services on the most promising leads, shortening the overall diligence cycle.

    Synthesizing Findings into Actionable Reports

    Translating weeks of analysis into a decision-ready report requires discipline. We structure every due diligence report to be concise—typically 2–4 pages of core material plus supporting appendices—and to avoid absolute language. The standard sections include:

    • Executive Summary: A one-page synthesis of the target’s strategic fit, valuation range, and go/no-go recommendation.
    • Functional Findings: Separate subsections for financial, legal, operational, and commercial due diligence, each highlighting the top three risks and opportunities.
    • Deal-Breakers and Risk Matrix: A table that categorizes issues by severity and probability, clearly flagging items that could kill the deal.
    • Conditions to Closing: Concrete actions the target must complete before signing, such as resolving outstanding litigation, obtaining key customer consents, or cleaning up IP ownership.
    • Recommendations: Final guidance on whether to proceed, renegotiate terms, or walk away.

    This structure ensures every stakeholder—whether a CEO, private equity partner, or legal advisor—can grasp the essential picture in minutes and drill into the details as needed. The resulting report arms the deal team with clear conditions to closing, which we address in the next section on negotiation and deal structuring.

    Advanced M&A Due Diligence Strategies

    Building on the foundational due diligence framework, advanced strategies dive deeper into operational and sector-specific risks, especially in cross-border contexts. Our advanced M&A due diligence services in New York go beyond the financial basics, examining technology integration, regulatory exposure, and cultural alignment. This comprehensive approach is critical for deal success.

    For cross-border transactions, the data room requirements multiply significantly. We manage virtual data rooms that comply with diverse data residency laws and incorporate translation services, ensuring that parties in different countries can review documents securely and without legal friction. This operational infrastructure is a core part of our due diligence services, streamlining what is often a logistical bottleneck in international deals.

    Assessing cultural and operational fit is another vital layer of advanced M&A due diligence practices. In cross-border deals, we evaluate not only language barriers and business norms but also time-zone management and workforce integration. A typical domestic merger can stabilize in three to nine months, but international combinations often require six to eighteen months due to the need for deeper integration planning and trust-building. This extended timeline reinforces the need for patient capital and thorough vetting.

    Sector-specific expertise tailors these cross-border due diligence strategies further. For technology companies, advanced diligence includes IP ownership verification, a rigorous software code audit, a cybersecurity posture review, and subscription revenue validation. In healthcare M&A, our due diligence services cover HIPAA compliance, FDA regulatory pathways, clinical trial data integrity, and reimbursement dependencies. These strategies set the stage for executing a rigorous due diligence plan, which we cover next.

    Frequently Asked Questions About M&A Due Diligence

    Building on the steps above, we address some frequently asked questions about M&A due diligence.

    What is M&A due diligence and why is it important?
    Our M&A due diligence services provide a comprehensive evaluation of financial, legal, operational, and strategic factors to identify risks and support informed decisions.

    What key areas are assessed during M&A due diligence?
    We review financial statements, legal contracts, operational workflows, and strategic positioning, leveraging our Sovereign Data Nexus for data-driven insights.

    How does Zaidwood Capital support clients during M&A due diligence?
    Our M&A due diligence services combine Precision Catalyst for investor engagement and Velocity Matrix for rapid execution, ensuring efficient and thorough due diligence.

    This information is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to buy or sell any security.

    Close Your Deals with Confidence

    With preparation complete, execution is where confidence is built. As a Boutique M&A and Capital Advisory Firm, we rely on rigorous M&A due diligence services tailored to each deal’s unique risks and opportunities, reducing uncertainty at every stage. The Sovereign Data Nexus provides proprietary real-time data that validates assumptions, flags hidden risks, and delivers actionable intelligence. Backed by a global network and capital markets experience, the Velocity Matrix accelerates closing timelines, giving clients the transparency to close with confidence, and carrying that assurance into the post-close relationship.
    Resources

  • What Is an Investment Bank? Key Services Explained

    What Is an Investment Bank? Key Services Explained

    Table of Contents

    The Role of Investment Banks in Modern Finance

    Understanding what is an investment bank is essential to grasping modern financial markets, as these institutions serve as vital intermediaries between companies seeking capital and the investors who provide it. According to the CFA Institute, the global standard-setter for the investment industry, investment banks facilitate capital formation, mergers and acquisitions, and market making, driving economic growth globally today.

    Investment banks perform three primary functions: capital raising, mergers and acquisitions advisory, and market making. In capital raising, we offer capital raising solutions that leverage our extensive investor network to secure equity and debt financing. In mergers and acquisitions, we advise on deal structuring, valuation, and negotiation, ensuring strategic alignment. Market making provides liquidity and price discovery, but boutique firms typically focus on advisory, delivering personalized, high-touch service enhanced by tools like our Sovereign Data Nexus and Velocity Matrix. These functions collectively channel capital to productive enterprises, fueling innovation and economic expansion.

    At Zaidwood Capital, we are redefining Financial Services 3.0 as a Boutique M&A and Capital Advisory Firm, combining proprietary data access via our Sovereign Data Nexus with precision execution through our Velocity Matrix to accelerate deals. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Investment Banking Services: From Advisory to Capital Markets

    When clients ask what is an investment bank, we answer with a clear definition: A financial institution that provides strategic advisory and capital-markets services to corporations, governments, and institutions. Unlike commercial banks that focus on deposit-taking and lending, investment banks operate on a fee-based model, guiding complex transactions like mergers and acquisitions and large-scale capital raising.

    Investment Bank vs. Commercial Bank
    Feature Investment Bank Commercial Bank
    Primary Focus Advisory & Capital Markets Deposits & Lending
    Revenue Model Fee-based Interest-based

    This distinction is foundational. While commercial banks serve everyday financial needs, investment banks unlock growth through corporate finance advisory, deal orchestration, and access to deep capital pools.

    Our firm’s advisory practice spans the full continuum of mergers and acquisitions—from target identification and valuation to negotiation and close—while our capital-markets capabilities help clients structure and secure equity, debt, and structured solutions. For a growing enterprise seeking capital raising, we craft strategic materials like pitch decks, business plans, and pro forma financials, then leverage our global network of over 4,000 institutional and private investors to create institutional introductions.

    Mergers and Acquisitions: How Investment Banks Drive Deal Execution

    To fully appreciate what an investment bank does in the context of mergers and acquisitions, it helps to examine the entire deal lifecycle. Investment banks serve as strategic partners that bring financial expertise, proprietary data tools, and a global investor network to the table. We follow a three-phase framework that covers deal sourcing and initial pitch, rigorous due diligence and financial modeling, and finally negotiation, structuring, and closing.

    Deal Sourcing and Initial Pitch

    We proactively identify acquisition targets or divestiture opportunities through our proprietary Sovereign Data Nexus and long-standing industry relationships. By continuously monitoring market signals and capital flows, we surface potential transactions that align with a client’s strategic objectives. Once a promising opportunity is identified, we craft a tailored pitch book that outlines a compelling investment thesis, preliminary valuation ranges, and a roadmap for value creation.

    Due Diligence and Financial Modeling

    Once a letter of intent is signed, we lead a comprehensive due diligence process that examines financial statements, operational metrics, legal risks, and market conditions. Following the best practices outlined by the CFA Institute, our team validates the target’s earnings quality, working capital dynamics, and growth assumptions. We build a suite of valuation models—discounted cash flow, precedent transaction, and leveraged buyout analyses—to triangulate intrinsic value and stress-test deal economics.

    Negotiation, Structuring, and Closing

    With due diligence findings in hand, we advise on deal structure—whether a stock or asset purchase, and how earn-outs, seller financing, or contingent consideration can bridge valuation gaps. We take the lead in negotiations, coordinating closely with legal and tax advisors to translate commercial terms into binding documents. Throughout this phase, our secure deal vaults serve as central hubs for all transaction materials, accelerating the exchange of sensitive information.

    Capital Raising Strategies: Equity and Debt Financing Pathways

    A core function of an investment bank is helping companies raise capital to fuel growth, execute strategic initiatives, or navigate complex transactions. At Zaidwood Capital, we specialize in capital raising as part of our Full-Cycle M&A and Capital Advisory services, connecting businesses with the right mix of equity and debt financing.

    Equity Financing: Private Placements and Growth Equity

    Equity financing allows businesses to raise capital by selling ownership stakes. Investment banks facilitate private placements, offering shares to accredited investors and institutional investors rather than public markets, which can be faster and more flexible. At Zaidwood Capital, we leverage a network of more than 4,000 investors to connect companies with the right capital providers.

    Debt Financing and Structured Solutions

    Debt financing allows companies to borrow capital without diluting ownership, preserving control for existing shareholders. Investment banks structure a range of instruments: senior debt is secured by company assets, carries a lower interest rate, and ranks first in repayment priority; mezzanine financing is subordinated, carries higher cost, and often includes equity warrants.

    Equity vs. Debt Financing
    Dimension Equity Debt
    Ownership Diluted Preserved
    Repayment None Regular Payments

    Preparing Your Business for a Capital Raise

    Thorough preparation significantly increases the likelihood of a successful capital raise. Start by compiling audited or reviewed financial statements that demonstrate historical performance and projections. A credible business valuation sets realistic expectations for deal terms. Develop a compelling investor pitch deck that clearly articulates the company’s value proposition, growth strategy, and use of funds.

    Boutique Investment Banking: The Zaidwood Capital Advantage

    If the searcher’s question is what is an investment bank, the clearest answer begins with the distinct categories of the industry. Investment banks facilitate the flow of capital, but they operate across a spectrum from boutique advisory firms to global full-service institutions and the largest bulge-bracket banks. At one end, boutique firms like Zaidwood Capital deliver high-touch, specialized guidance for mid-market and growth companies.

    Boutique vs. Full-Service vs. Bulge-Bracket
    Type Focus Advantage
    Boutique Advisory Senior Attention
    Bulge-Bracket Global Markets Balance Sheet
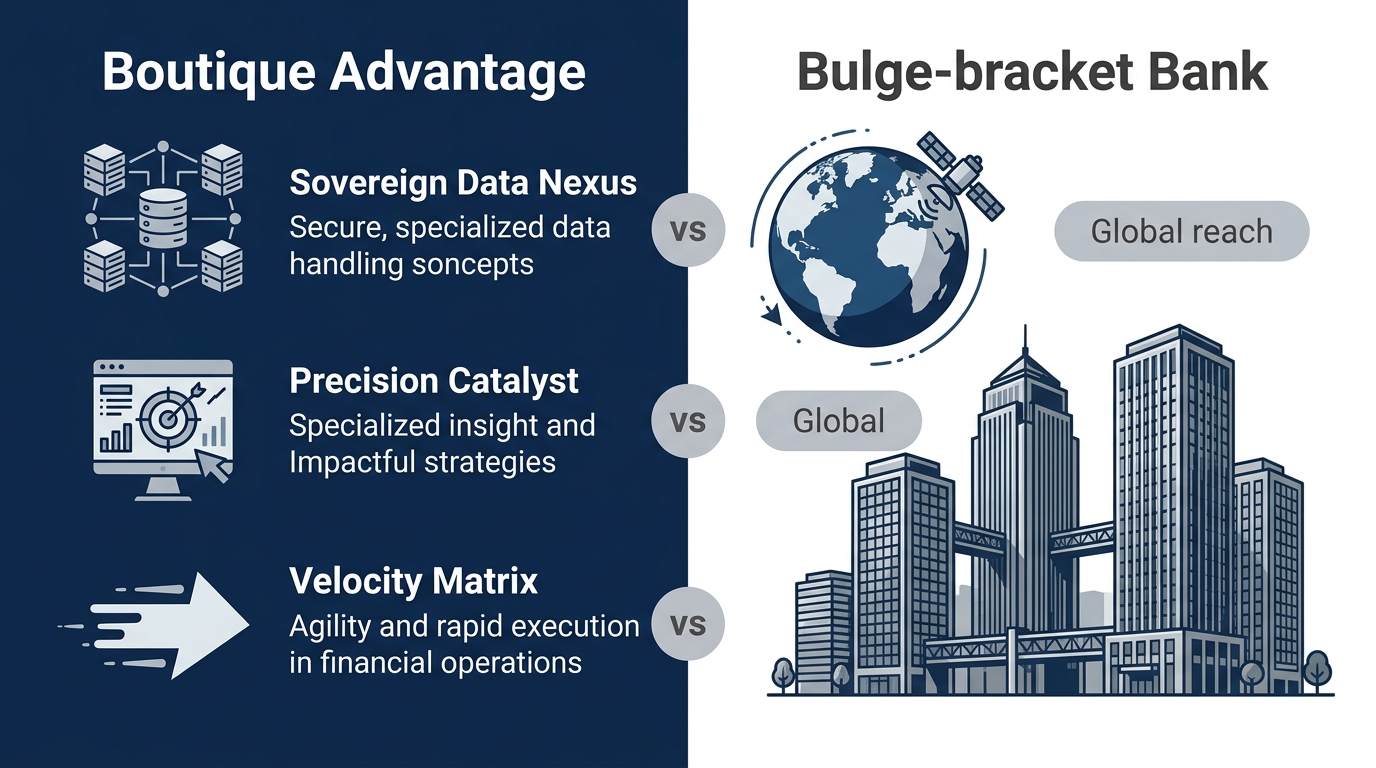
    Side-by-side infographic comparing boutique investment bank advantages with data, marketing, and speed icons versus traditional bulge-bracket bank with globe and buildings

    Comparison infographic showing boutique versus traditional banking advantages

    Common Questions About Investment Banking

    What is an investment bank?
    An investment bank is a financial intermediary that helps companies raise capital and execute mergers and acquisitions. They range from large bulge-bracket institutions to specialized boutique firms like ours, which provide senior-led, personalized advice and sector expertise.

    Unlike traditional investment banks, our boutique advisory provides end-to-end support throughout your transaction lifecycle. Our team brings expertise in mergers and acquisitions and capital raising, leveraging proprietary tools like the Sovereign Data Nexus for data-driven insights and the Velocity Matrix to accelerate execution. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC.

    Resources

  • Tree Care Industry Trends 2026: What You Must Know

    Tree Care Industry Trends 2026: What You Must Know

    Table of Contents

    As we examine tree care industry trends 2026, it’s clear that technology and capital are driving a fundamental transformation. The adoption of AI-powered tree risk assessment technology allows arborists and municipalities to make data-driven decisions, improving safety and operational efficiency across urban canopies.

    At the same time, climate-resilient urban canopy management is moving from a niche concern to a mainstream priority. As extreme weather events intensify, cities are recognizing the critical role of trees in cooling, carbon sequestration, and stormwater management. In our view, the shift from reactive tree removal to proactive care enabled by technology and climate policy is a long-term structural change that will fuel demand for advanced services.

    Capital is following these structural tailwinds. We are observing growing M&A activity in the tree care sector, mirroring patterns identified in Zaidwood Capital’s overview of emerging markets M&A. Consolidation is enabling companies to scale and attract institutional investors seeking stable, infrastructure-linked returns. The influx of capital into tech-enabled tree care companies further signals market confidence in the sector’s growth.

    For investors, these converging trends create a favorable landscape for participating in the environmental infrastructure space. We believe that understanding these drivers can help position portfolios for the maturation of green infrastructure, though past performance does not guarantee future results. Ultimately, this article is for informational purposes and does not constitute an offer, solicitation, or investment advice.

    Understanding the Tree Care Industry’s Structural Shift

    The tree care industry trends 2026 point to a fundamental structural shift reshaping arboricultural services and their investment landscape. Three primary drivers are fueling this transformation:

    • Adoption of AI-powered tree risk assessment technology
    • Mandates for climate-resilient urban canopy management
    • Accelerating M&A consolidation across historically fragmented markets

    Technology is the first seismic force. Innovative firms are deploying AI-powered tree risk assessment technology to evaluate health, stability, and failure probability with precision never before possible. These platforms analyze multispectral imagery, weather patterns, and soil data to forecast liabilities at scale, capturing the attention of private equity and growth-focused investors.

    Climate imperatives are the second driver. Municipalities worldwide are mandating climate-resilient urban canopy management to combat heat islands and stormwater surges. The resulting fragmentation and unmet compliance demand create natural roll-up opportunities. Regional platforms that can consolidate services while meeting sustainability metrics are becoming prime targets for strategic acquirers and institutional funds seeking ESG-aligned exposure.

    Finally, M&A consolidation is accelerating across the tree care sector. Zaidwood Capital’s deep dive into emerging markets M&A reveals a 15 percent annual surge in transaction volumes across developing economies—a dynamic mirrored in North American specialty services. This structural momentum positions the tree care industry for increased emerging markets M&A activity, drawing interest from sovereign wealth funds and cross-border alliances.

    Technology and Climate Adaptation: Drones, AI, and Resilient Canopies

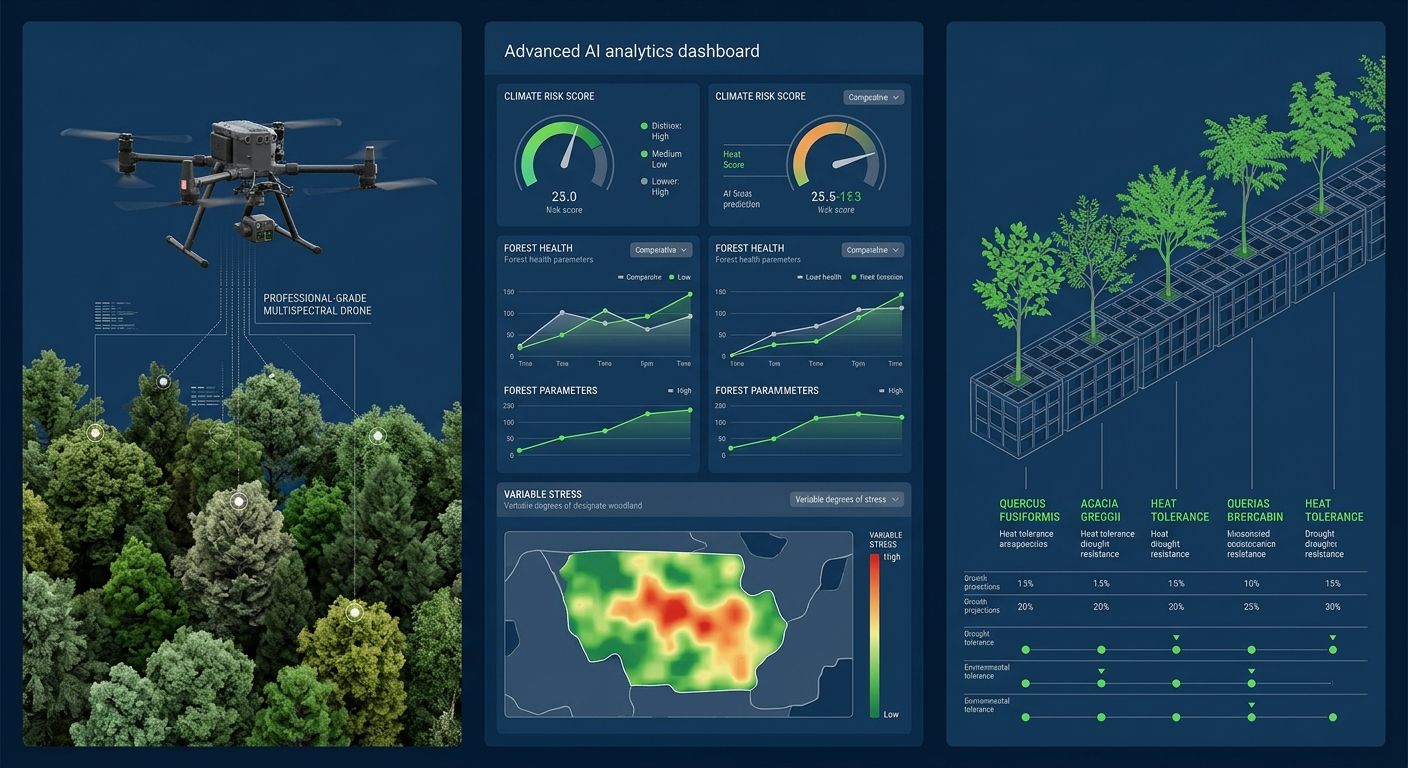
    Among the most impactful tree care industry trends 2026 are the rapid adoption of drone-based health assessments, AI-powered risk prediction, and climate-adaptive species selection.

    Horizontal infographic with three columns showing drone with multispectral camera over tree canopy, AI risk dashboard, and heat-tolerant tree species

    Technology and climate adaptation with drones, AI, and resilient canopies

    Drone-Based Arborist Health Assessments

    Drone-based arborist health assessments are revolutionizing the field. Equipped with multispectral and LiDAR sensors, drones capture high-resolution imagery and 3D data that reveal early signs of disease long before symptoms are visible to the naked eye. This approach improves safety and cuts inspection costs by up to 50% compared to traditional methods.

    AI-Powered Tree Risk Assessment Technology

    The next frontier in arboriculture is AI-powered tree risk assessment technology. By feeding data from IoT soil moisture probes and historical weather patterns into machine learning models, these systems can predict the probability of limb failure with remarkable accuracy. This allows arborists to schedule preventive maintenance proactively.

    Climate-Adaptive Tree Care Practices

    Professionals are rethinking species selection to create climate-resilient urban canopy management strategies. Heat- and drought-tolerant species gaining prominence include Quercus macrocarpa (Bur Oak), Ulmus ‘Morton Glossy’ (Triumph™ Elm), and Gleditsia triacanthos var. inermis (Thornless Honeylocust). These proactive steps ensure that urban forests continue to deliver ecosystem services as conditions shift.

    Residential Service Growth and the Labor Crisis: Practical Implications for 2026

    Outlook for Residential Tree Service Growth

    Three primary catalysts drive demand for residential tree services: home improvement activity, severe weather events, and accelerating urbanization. Homeowners are increasingly aware of the value mature trees bring to property valuations. According to the urban tree care framework, increased urban sprawl and aging tree stocks require professional risk mitigation well into 2026.

    How Labor Shortage Shapes Pricing and Operations

    Despite strong demand, a shortage of certified arborists is reshaping the sector. In acute markets, residential prices have risen 15–20% as firms bid up wages. Adoption of AI-powered tree risk assessment technology allows crews to prioritize inspections using drone imagery, mitigating the shortage by improving efficiency for existing staff.

    Investment Valuation and Capital Formation in the Tree Care Sector

    Understanding tree care industry trends 2026 is essential for business owners. Valuation typically revolves around adjusted EBITDA multiples in the 3-5x range. Beyond traditional metrics, companies demonstrating AI-powered tree risk assessment technology implementation and climate-resilient urban canopy management command premium pricing from institutional investors.

    How is AI transforming tree risk assessment in 2026?
    AI-powered tree risk assessment technology uses predictive analytics to detect hazards early, reducing emergency costs and improving safety.

    What is climate-resilient urban canopy management?
    It focuses on selecting diverse, drought-tolerant species and strategic planting to help urban forests weather climate shifts.

    Why choose a veteran-owned tree service?
    Consider a veteran owned tree service like Climbing Grunt for discipline and commitment to safety.

    Resources

  • Institutional Capital Sources: Ultimate Guide to Private Credit

    Institutional Capital Sources: Ultimate Guide to Private Credit

    Table of Contents

    Understanding Institutional Capital Sources

    Institutional capital sources represent large pools of investment funds managed by organizations such as pension funds, insurance companies, sovereign wealth funds, and private credit funds. These entities provide substantial financing for corporate growth, acquisitions, and real estate ventures.

    Private credit lenders operate in the direct lending space, offering customized financing solutions through asset-based lending and cash flow financing structures. Through our global lending services, companies can access these tailored institutional funding options. These lenders typically seek long-term partnerships with growing businesses, providing larger capital amounts with more flexible terms than traditional bank financing.

    Sovereign wealth funds, such as those in the Middle East and Asia, are government-owned investment vehicles that deploy capital into infrastructure, real estate, and strategic sectors globally. These government investment funds bring patient capital with extended investment horizons.

    Through our network of over 4,000 global investors, we connect clients with institutional investor capital sources suited to their transaction requirements. Securities offerings are facilitated through Finalis Securities LLC, a registered broker-dealer.

    Assess Your Readiness for Institutional Capital

    Institutional capital sources such as private credit lenders and sovereign wealth funds can provide transformative financing for growth-stage companies. At Zaidwood Capital, we encourage businesses to assess their readiness across several key dimensions before engaging these sophisticated capital partners.

    • Financial and asset readiness: Investors generally expect at least $5–$10 million in revenue and positive EBITDA. For asset-based lending, clear collateral coverage and strong asset quality are critical. And liquidity runway matters.
    • Management and governance: An experienced leadership team, a clean capitalization table, and transparent financial reporting demonstrate organizational maturity and reduce investor risk.
    • Market positioning: Defensible competitive advantages, a clear growth trajectory, and a large addressable market signal the ability to scale and capture value.
    • Compliance and due diligence readiness: Companies must be prepared to meet SEC regulations (including Regulation D) and have audited financials, legal documents, and a compelling pitch deck ready.

    Assessing these areas objectively is the first step. Engaging professional capital advisory services can help bridge any gaps, guiding you through due diligence and matching your profile with institutional investors who align with your growth objectives.

    Identify Target Institutional Investor Profiles

    Identifying the right institutional capital sources is the foundation of every transaction we advise on. Within the global capital ecosystem, we isolate institutional investor profiles that align precisely with each client’s industry, deal size, and financing structure—whether equity, debt, or hybrid capital.

    Our process draws on data published by the Federal Reserve Bank of New York to track institutional activity and capital flow trends, revealing which investor segments are most active for a given mandate. We then apply classification standards from the International Capital Market Association to map investors by risk appetite, asset class preference, and transaction size thresholds. This shapes a shortlist that can include private credit lenders, sovereign wealth funds, pension funds, endowments, and family offices.

    Through our mergers and acquisitions advisory, we connect each institutional profile to the appropriate transaction structure and capital strategy. With an aggregated network of over 4,000 institutional and private investors representing more than $15 billion of deployable capital, updated quarterly, we can surface the institutional capital pools most relevant to your objectives.

    This information is for informational purposes only and does not constitute an offer. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Prepare Investor Pitch Materials

    Based on the due diligence insights gathered earlier, we now assemble investor pitch materials designed to secure funding from institutional capital sources. This critical step translates analytical findings into compelling narratives that drive investment decisions. Our approach leverages Zaidwood Capital’s Full-Cycle M&A and capital advisory framework.

    • Value Proposition & Market Analysis: We craft a clear narrative that connects your opportunity to institutional capital sources, including a market analysis slide.
    • Targeted Messaging: Debt-oriented materials resonate among private credit lenders, while equity pitches are assessed by sovereign wealth funds.
    • Financial Projections: All pro formas carry the disclaimer: “These projections are for informational purposes and do not guarantee future results.”
    • Compliance & Regulatory Requirements: Every deck includes risk factors as required by the SEC. We are not a registered broker-dealer; securities are offered through Finalis Securities LLC. Always refer to the securities regulation authority for updated guidance on private placement rules.
    • Zaidwood Capital Advantage: Our Deal Vault and 4,000+ global investors provide a distribution edge without implying guaranteed outcomes.

    With completed materials, we move to presenting them through our institutional network of over 4,000 investors. Book a Call to finalize your materials and start engaging capital sources.

    Approach Sovereign Wealth Funds and Endowments

    We access diverse institutional capital sources by targeting sovereign wealth funds (SWFs) and endowments, each with distinct mandates. SWFs, such as stabilization funds in the Middle East, seek long-term value creation, while university endowments based in the US follow spending policies that balance growth and liquidity. Identifying these mandates is the critical first step in full-cycle M&A and capital advisory.

    Our engagement strategy leverages proprietary data, specifically the Sovereign Data Nexus, to pinpoint funds with aligned investment criteria. We then initiate contact through investor relations channels, presenting our capital introductions and due diligence capabilities. Communications are structured to comply with regulatory frameworks, including those established by the Financial Industry Regulatory Authority (FINRA), which governs promotional materials and accredited investor verification.

    We apply the Velocity Matrix to structure and accelerate deal flow, combined with Precision Catalyst for targeted matching between opportunities and institutional pools. We explicitly avoid promising specific outcomes or guaranteeing transactions. This website is for informational purposes only and is not an offer or solicitation. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. Beyond sovereign wealth funds and endowments, institutional capital sources include private credit lenders, which we address next.

    Engage Private Credit Lenders

    As we expand the discussion beyond traditional institutional capital sources, private credit lenders represent a distinct and increasingly vital segment of the financing landscape. These are institutional investors — from specialized debt funds to family offices and sovereign wealth funds — that provide non-bank financing directly to companies. At Zaidwood Capital, we connect our clients to a deep network of these alternative capital providers.

    Two of the most common structures offered by private credit lenders are asset-based lending, which is secured by a company’s tangible assets, and cash flow financing, which is underwritten against projected revenue streams. Our qualification framework, which mirrors the rigorous documentation standards benchmarked by the International Capital Market Association (ICMA), ensures a smooth due diligence process. The broader liquidity environment, shaped by Federal Reserve Bank services, continuously affects the terms and availability of capital from these lenders.

    We facilitate these engagements by aligning a client’s financial profile — supported by three years of audited financials and multi-year cash flow projections — with the specific mandates of institutional investors. Individual outcomes will vary, but this targeted approach helps streamline what is often a complex capital raise, setting the stage for us to explain how we actively enable these introductions.

    Before any deal closes, a thorough due diligence and legal review must be completed. We guide clients through this phase to identify risks, verify claims, and ensure regulatory compliance, a prerequisite for attracting institutional capital sources like private credit lenders and sovereign wealth funds.

    Adhering to SEC securities regulation ensures disclosure compliance and reduces legal risk. The U.S. Securities and Exchange Commission (SEC) sets the baseline for securities offerings and anti-fraud provisions. Meanwhile, FINRA oversees the broker-dealer firms that execute transactions, adding another layer of oversight that institutional investors demand.

    A typical review includes:

    • Regulatory compliance check (SEC rules)
    • Broker-dealer oversight (FINRA)
    • Legal document review (NDAs, term sheets, purchase agreements)
    • Client material preparation (deal memoranda, legal opinions)

    This rigorous process satisfies the due diligence standards of private credit lenders and sovereign wealth funds. Once regulatory compliance is confirmed, our Full-Cycle M&A and capital advisory team streamlines the transition to negotiation and closing. (This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to transact. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.)

    Negotiate Terms and Structure the Deal

    Once due diligence confirms the opportunity, the next phase is negotiating terms and structuring the deal to align with the expectations of institutional capital sources. Negotiating with institutional capital sources requires understanding their distinct priorities: private credit lenders typically focus on cash-flow coverage, collateral quality, and floating-rate benchmarks tied to effective Fed funds, while sovereign wealth funds often seek co-investment rights, board representation, and long-term alignment with investment horizons. Current monetary policy, as reflected in rate data from the Federal Reserve Bank of New York, directly influences structure choices—floating versus fixed rates, coupon floors, and covenant flexibility. At Zaidwood Capital, we leverage our full-cycle advisory and proprietary Sovereign Data Nexus to customize structures that balance these competing demands and institutional investor preferences. With terms negotiated and structure agreed, the transaction moves to documentation and closing.

    Close and Maintain Institutional Relationships

    We actively identify and cultivate long-term partnerships with institutional capital sources that align with our clients’ strategic objectives. Operating outside the scope of a registered broker-dealer — a distinction clarified by the Financial Industry Regulatory Authority (FINRA) — we serve as a capital introduction intermediary, facilitating connections rather than executing securities transactions.

    Our network spans sovereign wealth funds, private credit lenders, pension funds, endowments, foundations, and insurance companies. Through our proprietary Sovereign Data Nexus and Velocity Matrix platforms, we match clients to these institutional capital sources based on investment criteria, sector focus, and capital requirements. Beyond the initial introduction, we maintain these relationships through periodic updates, reporting, and facilitated meetings — ensuring sustained engagement without guaranteeing specific outcomes.

    With access to 4,000+ global investors and over $15 billion in deployable capital, we are positioned to support your capital formation goals. Book A Call to discuss your institutional strategy.

    Overcoming Common Barriers to Institutional Capital

    However, accessing these institutional capital sources is not automatic — companies must overcome several well-known hurdles. Many businesses find that institutional capital sources from sovereign wealth funds and other large investors remain out of reach due to gaps in documentation, governance, and financial transparency.

    A frequent barrier is insufficient or poorly organized asset documentation, which prevents companies from qualifying for asset-based lending. Our FAQ outlines that institutions require a clear, verifiable collateral base and detailed asset records. For asset-based lending or cash-flow financing, presenting a strong collateral package and a verifiable cash-flow history is essential. Companies that invest in structured asset tracking and formal appraisals greatly improve their eligibility and signal readiness to private credit lenders.

    Lack of audited financial statements and credible cash-flow projections is another top reason for rejection. Institutional investors typically require three years of audited financials and three- to five-year cash-flow forecasts. Our qualification framework shows that without these, even otherwise healthy businesses struggle to demonstrate their repayment capacity. By committing to regular audits and building realistic, multi-year projections, companies can close this critical gap.

    Inadequate governance structures and limited credit histories further complicate access. The International Capital Market Association (ICMA) emphasizes that institutional investors expect transparency, standardized reporting, and robust risk management. Adopting these standards reduces friction and builds the confidence of sovereign wealth funds and private credit market lenders. Additionally, preparing a detailed business plan with pro-forma financials, a clear use-of-funds explanation, and a credible repayment strategy demonstrates the kind of institutional readiness that professional investors expect.

    Proactive preparation and early engagement with a capital advisor can streamline the entire process. With proper documentation and governance alignment, these barriers can be systematically addressed — which is exactly where our Full-Cycle M&A and capital advisory services come into play.

    Your Pathway to Institutional Capital

    Accessing institutional capital sources—from private credit lenders in the US to sovereign wealth funds worldwide—requires a partner with deep investor relationships. Our network includes pension funds, family offices, and other institutional investors. Zaidwood Capital connects you to over 4,000 investors with more than $15B in deployable capital.

    Our proprietary tools—Sovereign Data Nexus, Precision Catalyst, and Velocity Matrix—streamline due diligence, investor outreach, and deal execution. With $24.4B+ in aggregate transaction volume and more than 300 deals completed, we deliver full-cycle M&A and capital advisory. Securities are offered through Finalis Securities LLC (member FINRA/SIPC) in compliance with regulatory requirements. Past performance does not guarantee future results.

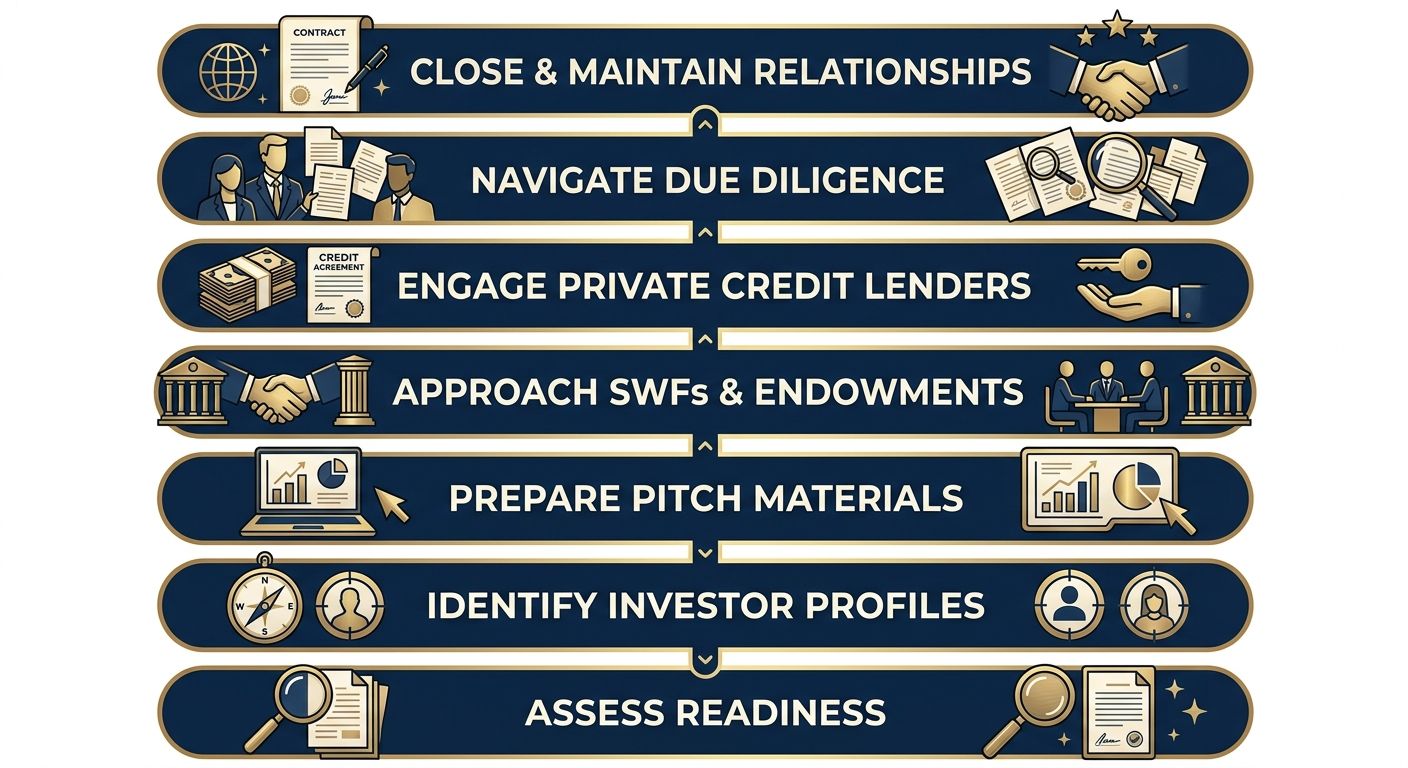
    Seven-step capital pathway infographic showing each advisory stage from readiness assessment to deal closing and relationship management.

    Your Pathway to Institutional Capital in seven clear steps

    This seven-step process brings clarity to every phase of capital raising, from readiness assessment to deal closing. Begin your pathway today. Book a call with our team to discuss your capital raising goals and discover how our investor network can work for you.

    Resources

  • Direct Lending Market Comparison: Top Private Capital Strategies

    Direct Lending Market Comparison: Top Private Capital Strategies

    Table of Contents

    Direct Lending Market: A Competitive Capital Source for Middle-Market Companies

    Middle-market firms facing rigid bank underwriting increasingly turn to the direct lending market for speed and flexibility. Unlike traditional bank loans, direct lending—provided by non-bank institutions—offers faster execution, covenant-light structures, and reduced regulatory hurdles. Our firm’s research confirms that borrowers value this private credit market for its ability to close deals swiftly.

    Current U.S. direct lending spreads remain competitive, attracting middle-market companies away from syndicated loans. Zaidwood Capital’s market intelligence shows direct lending integrates with broader private capital raising strategies, including GP-led secondary transactions that provide liquidity. Companies pursuing emerging markets M&A also benefit from direct lending’s speed and flexibility. In the following section, we outline how our team structures these customized solutions.

    1. Competitive Interest Rate Spreads

    In the U.S. direct lending market, borrowers seek competitive pricing amid tightening spreads. According to Zaidwood Capital’s market analysis, current all-in yields reflect the following typical ranges in basis points (bps):

    • Senior secured direct loans for mid-market transactions: SOFR + 400–600 bps.
    • Unitranche structures for high-quality sponsors: SOFR + 350–500 bps, while smaller or riskier borrowers may see spreads of +600–800 bps.
    • Second-lien or mezzanine tranches: SOFR + 800–1,200 bps.

    Spread compression over the past year has been driven by heightened competition among direct lenders, a trend we also observe in private capital raising strategies and GP-led secondary transactions. Deal size, credit quality, and leverage shape pricing, and our network enables us to secure competitive terms in the U.S. direct lending market. While spreads remain competitive, sponsors pursuing emerging markets M&A often face wider spreads due to higher perceived risk. These benchmarks directly influence the cost of capital across deal structures, a dynamic we navigate for every mandate.

    2. Flexible Financing Structures

    Beyond standard capital raising, we offer flexible financing structures that leverage the direct lending market to deliver faster execution and custom terms compared to traditional bank loans. As our internal FAQ on direct lending explains, this alternative to bank financing bridges gaps where conventional credit often falls short, especially for mid-market transactions.

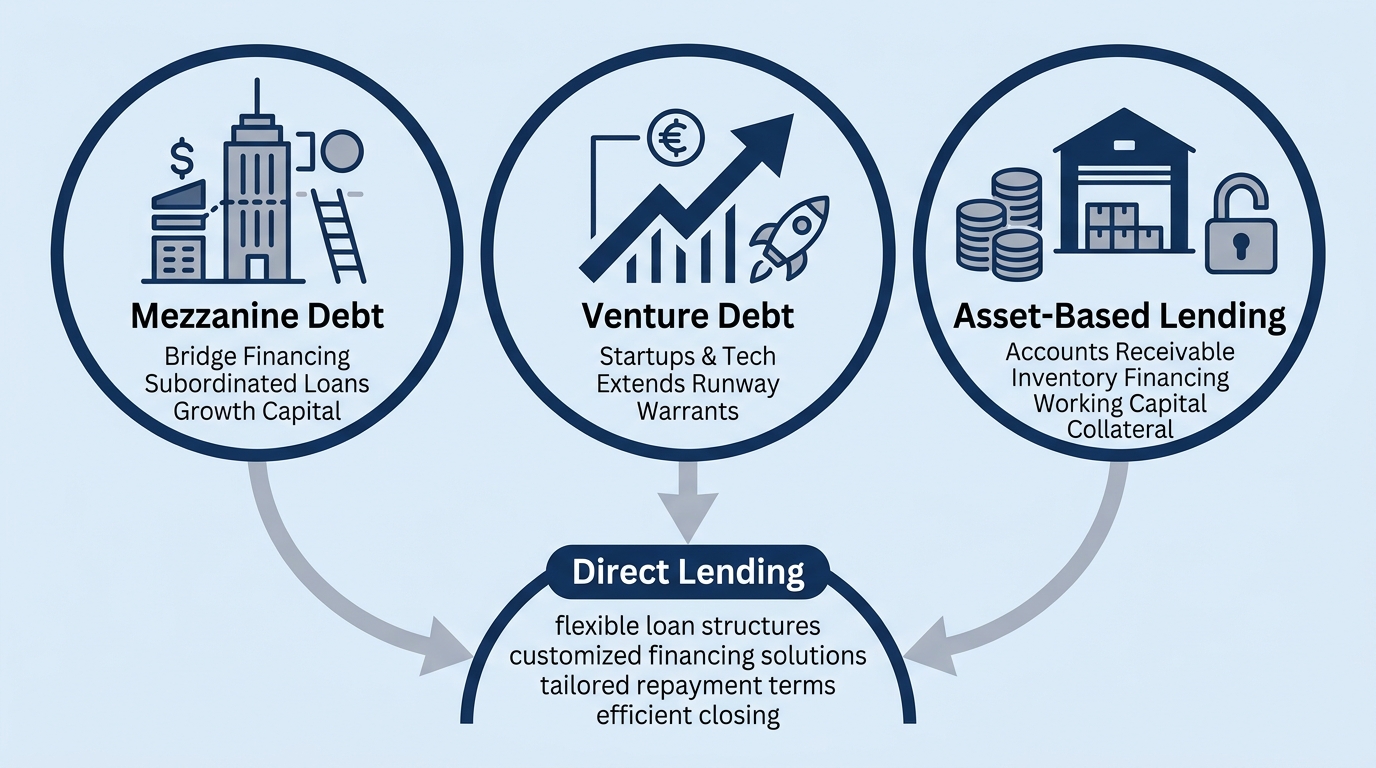
    Our tailored solutions encompass mezzanine debt, venture debt, equipment financing, and asset-based lending. Each instrument is custom-quoted to the client’s specific transaction, ensuring the right capital structure for growth, acquisitions, or liquidity. By operating in the direct lending market, we can craft flexible covenants and amortization schedules that align with your cash-flow profile. These structures support private capital raising strategies that go beyond one-size-fits-all bank terms.

    Infographic showing three flexible financing structures: mezzanine debt, venture debt, and asset-based lending connected to a direct lending hub.

    Flexible financing structures connected to direct lending.

    This flexible financing approach is designed to reinforce your buy-side M&A strategies with speed and precision, complementing our Full-Cycle M&A and capital advisory. To explore a custom-quote structure for your next transaction, Book A Call. This is not an offer or commitment; all financing is subject to due diligence and final documentation.

    3. Speed and Certainty of Execution

    In today’s direct lending market, speed and certainty of execution are decisive advantages for businesses evaluating private capital raising strategies.

    Traditional syndicated bank loans demand months of negotiation among multiple syndicate tiers and require extensive regulatory filings under SEC capital raising regulations; in stark contrast, direct lenders issue committed capital letters upfront and close in weeks, with fewer parties, less documentation, and a near-certain funding outcome.

    Zaidwood Capital’s proprietary market intelligence shows that current U.S. direct lending interest rate spreads remain favorable for borrowers, indicating that institutional lenders are actively seeking to deploy capital and can move swiftly when opportunities arise.

    Our approach to Streamlining Transactions shortens the search and negotiation cycle, and with a global network of over 4,000 investors, we accelerate execution for transactions ranging from corporate debt to GP-led secondary transactions, reducing opportunity cost and securing better terms.

    This speed and certainty, combined with Zaidwood Capital’s full-cycle advisory platform, streamlines access to substantial institutional capital for businesses pursuing growth.

    4. Middle-Market Capital Access

    Middle-market companies with revenues between $10 million and $1 billion frequently encounter a capital gap that traditional bank loans cannot fill, making access to capital in the direct lending market a vital alternative. As our FAQ notes, direct lending transactions close weeks faster than bank loans, with fewer covenants and flexible terms that adapt to a company’s cash flows rather than rigid formulas. Post-2008 regulatory changes constrained traditional bank lending, cementing the direct lending market as the core funding channel for mid-size firms. We help middle-market firms structure direct lending opportunities through our network of over 4,000 institutional investors and $15 billion in deployable capital, accelerating execution and reducing time-to-close. Beyond direct lending, our team deploys wider private capital raising strategies, including GP-led secondary transactions, to meet each company’s unique capital needs. Because direct lending operates under FINRA regulation direct lending, all participants must ensure strict compliance. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.

    5. Private Equity Buyout Support

    The direct lending market has become a cornerstone of private equity buyouts as firms seek speed and flexibility beyond traditional bank leverage loans. We at Zaidwood Capital see direct lender financing offering bespoke terms that align with the specific cash flow profiles of portfolio companies. This private credit approach sidesteps the rigid syndication processes of conventional banks, enabling faster closings and more creative capital structures. GP-led secondary transactions further illustrate how direct lending injects liquidity, allowing general partners to hold assets longer while offering LPs partial exits. Our private capital raising strategies incorporate direct lending solutions to support full-cycle buyout execution from acquisition through value creation. Direct lending also complements traditional bank financing by filling gaps where syndicated markets retreat, a dynamic we harness in our advisory work. As deal complexity grows, we view direct lending not as a niche instrument but as an enabling component driving the next phase of transaction structuring and capital deployment.

    6. Regulatory Landscape and Liquidity

    The direct lending market has experienced profound changes as regulatory oversight intensifies. Heightened scrutiny from the SEC and evolving risk-retention rules have dampened risk appetite among lenders, tightening liquidity dynamics across the sector. This shift is reshaping how capital flows into private credit.

    As bank-led lending retrenches, institutional capital increasingly pivots toward the direct lending sector. Stringent regulatory frameworks—including enhanced disclosure requirements and capital adequacy standards—drive allocators to reassess exposure. Our own analysis confirms that the regulatory environment compels investors to seek more resilient structures and transparency.

    These pressures have accelerated the adoption of private capital raising strategies and GP-led secondary transactions. By facilitating liquidity through secondary market solutions, managers can mitigate the constraints imposed by today’s regulatory landscape.

    Navigating this complexity demands deep market intelligence. Our firm leverages a network of over 4,000 institutional investors and $24.4B+ in aggregate transaction volume to help clients secure capital formation and liquidity in regulated markets. We help lenders and sponsors adapt their strategies, ensuring they remain positioned for success.

    7. Private Capital Raising Strategies

    For middle-market firms, private capital raising strategies offer an alternative to public markets, with the direct lending market serving as a vital source of flexible financing. These approaches enable capital formation for acquisitions, recapitalizations, and liquidity events while avoiding the regulatory complexities of an IPO.

    We help clients evaluate several private capital raising strategies:

    • Equity financing
    • Debt financing
    • Mezzanine debt
    • Direct lending
    • GP-led secondary transactions

    Direct lending, from non-bank institutional lenders, provides tailored capital complementing traditional bank loans. GP-led secondary transactions provide liquidity for limited partners while general partners can continue managing assets. At Zaidwood Capital, we design and execute these capital raises using our network of over 4,000 institutional investors and $15B+ in deployable capital, tailoring solutions to each firm’s profile. We integrate rigorous due diligence as part of our full-cycle M&A and capital advisory approach to ensure a seamless path from strategy to close.

    This site is for informational purposes only. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a broker-dealer.

    8. GP-Led Secondary Transactions

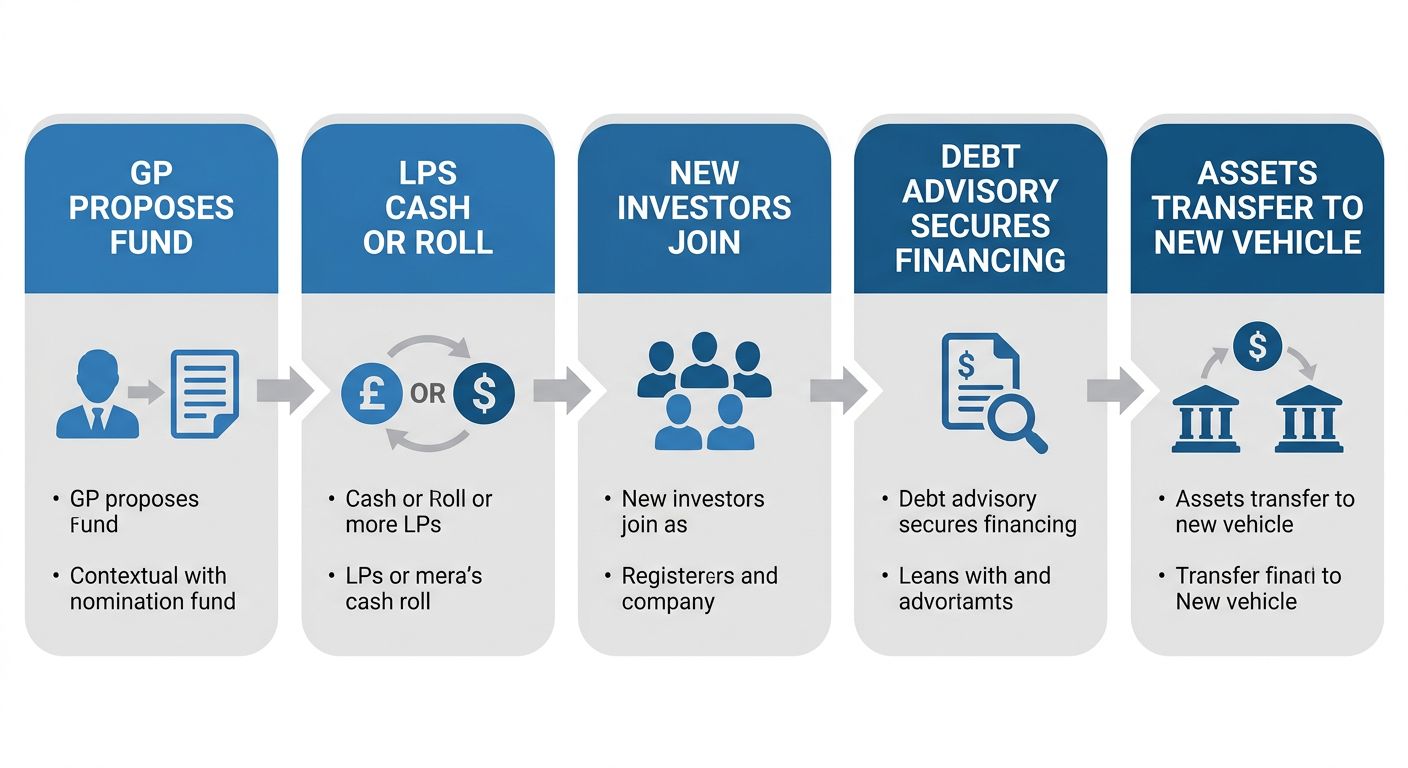
    In a GP-led secondary transaction, the general partner sells a portfolio company into a newly formed continuation fund backed by both existing and new limited partners. This approach, part of broader private capital raising strategies, provides early liquidity to LPs while allowing the GP to retain the asset and pursue additional value creation over a longer horizon. For careful LPs, these transactions offer a path to realize returns before a traditional exit; for GPs, they preserve management continuity and extend the runway for further growth.

    At Zaidwood Capital, we advise GPs on structuring these deals, securing institutional capital through our network of over 4,000 investors, and managing execution from start to finish. Our equity advisory and liquidity solutions practice ensures that each transaction is tailored to the fund’s objectives, streamlining transactions within our full-cycle M&A and capital advisory framework. Beyond GP-led secondaries, we support a spectrum of liquidity and capital formation strategies, including our broader equity advisory and debt advisory capabilities, positioned to serve mid-market funds across changing market cycles.

    Evaluating Direct Lending for Your Capital Strategy

    When evaluating the direct lending market, we recognize it as a private credit solution where institutional lenders provide capital directly to companies, bypassing traditional bank intermediaries.

    Direct lenders typically deliver faster execution, fewer covenants, and more flexible terms than banks—a key advantage when evaluating the direct lending market for companies with strong fundamentals seeking growth capital or acquisition financing without dilutive equity. Through direct lending, we streamline transactions, providing faster access to institutional capital. To determine fit, we assess the lender’s track record, deal flow, and alignment with your capital structure goals.

    As part of a broader set of private capital raising strategies, direct lending can complement other financing tools. GP-led secondary transactions frequently employ direct lending structures to facilitate liquidity or recapitalization.

    Resources

  • Best Quality of Earnings Report for Mid-Market Deals 2026

    Best Quality of Earnings Report for Mid-Market Deals 2026

    Table of Contents

    The Role of Quality of Earnings Reports in Mid-Market M&A

    Following a comprehensive due diligence review, buyers and lenders in mid-market M&A transactions focus on the Quality of Earnings (QoE) report, an independent assessment of a target company’s historical financial performance, adjusted for non-recurring items. This analysis goes far beyond audited financials by evaluating revenue sustainability, customer concentration, and the normalization of operating expenses and working capital. A well-prepared quality of earnings report provides a clearer view of recurring EBITDA, which serves as the foundation for valuation and debt sizing.

    Why QoE Matters in Mid-Market Deals

    The insights from an earnings quality analysis routinely reshape transaction terms. Buyers use the adjusted EBITDA to support purchase price adjustments, earnout structures, and net-working-capital targets. Lenders, in turn, demand a validated earnings baseline before committing acquisition debt. Moreover, the QoE often uncovers deferred-revenue patterns or concentration risks that, if ignored, can surface as costly post-close liabilities. In mid-market transactions where information gaps are common, a thorough QoE report reduces post-close surprises and gives the commissioning party a stronger negotiating position.

    Because mid-market companies frequently lack the internal resources to produce a GAAP-independent earnings analysis on their own, many engage specialized M&A advisors to manage the QoE process. At Zaidwood Capital, we integrate the QoE directly into our full-cycle due diligence offering, coordinating with independent accounting firms to deliver a report that buy-side and sell-side clients can rely on during negotiation and financing. We handle all financial data in accordance with rigorous confidentiality standards. For information on how we protect client information, please review Zaidwood Capital Privacy Policy.

    What Defines a Quality of Earnings Report

    A critical subset of due diligence, central to mid-market transaction diligence, is the Quality of Earnings Report, a financial analysis that evaluates the recurring, normalized earnings of a target company. At Zaidwood Capital, we define a QoE report as a rigorous assessment of earnings sustainability, designed to strip out non-recurring items and present a true picture of operating performance. This analysis is a cornerstone of our full-cycle due diligence process for mid-market M&A transactions.

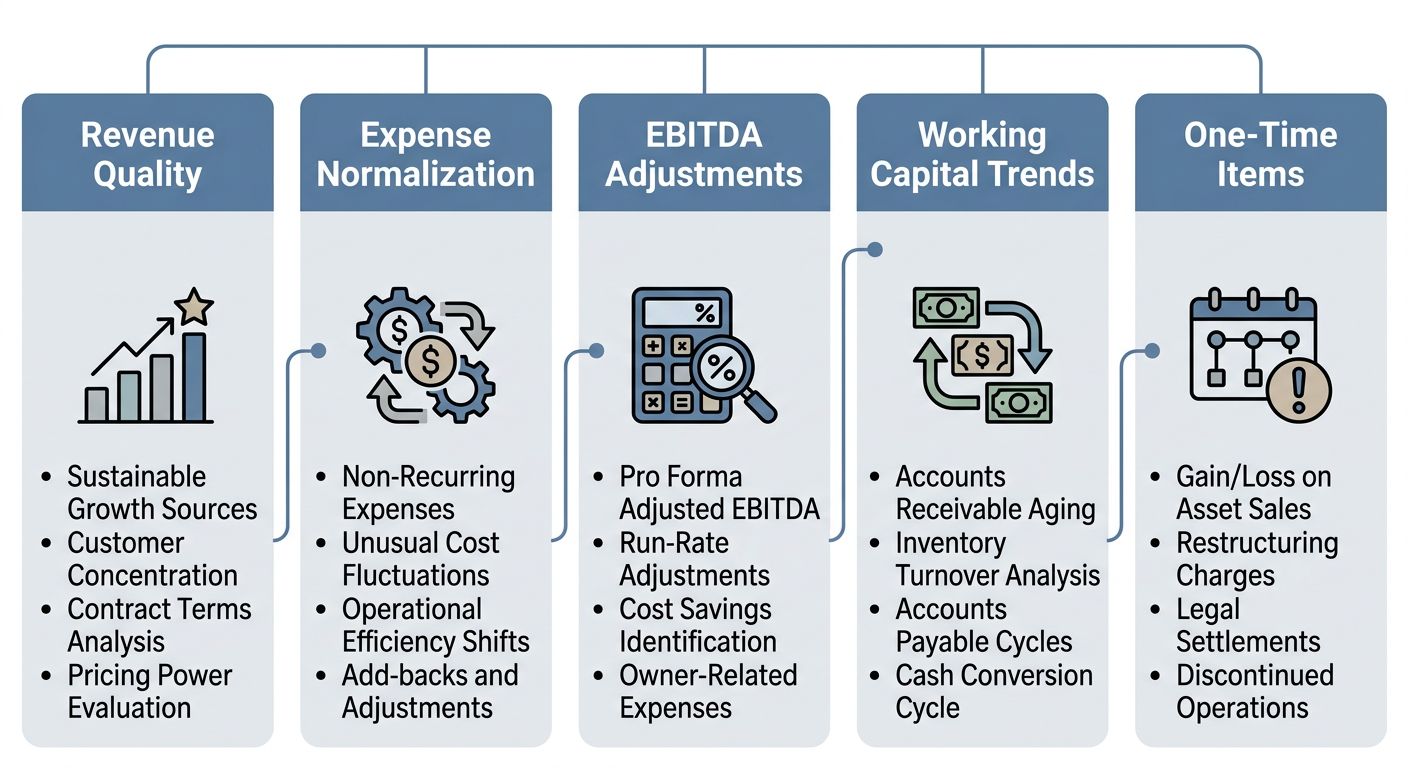
    A comprehensive earnings quality analysis examines several critical areas. Revenue quality scrutinizes the predictability and diversification of income streams. Expense normalization adjusts for one-time costs, owner’s compensation, or other out-of-ordinary expenses. EBITDA adjustments remove non-operating or non-cash items to reflect sustainable earnings. Working capital trends highlight operational liquidity needs and potential cash drags. One-time items, such as litigation settlements or asset sales, are excluded to reveal the underlying earning power. These dimensions collectively inform whether the company’s earnings are sustainable and repeatable for future periods.

    Infographic with five columns representing core areas of a quality of earnings analysis: Revenue Quality, Expense Normalization, EBITDA Adjustments, Working Capital Trends, and One-Time Items, each with icons and bullet lists on a muted blue and gray palette.

    Zaidwood Capital’s Quality of Earnings analysis framework visualized in five key areas.

    By producing a normalized earnings base, the QoE report helps both buyers and sellers reach consensus on valuation. For buy-side M&A professionals, this analysis highlights the true recurring profitability of a target, removing distortions that could inflate or deflate the purchase price. Sellers also benefit, as a well-documented QoE report can justify a premium and accelerate negotiation.

    As part of our Full-Cycle M&A and capital advisory services, we integrate QoE analysis into every engagement to provide clients with clear, defensible financial insights. The report is not an audit; it does not verify financial statement accuracy in compliance with accounting standards. Instead, it offers transaction-specific intelligence that traditional audits often miss. Zaidwood Capital utilizes QoE reports as a core component of its full-cycle due diligence, ensuring that both buy-side and sell-side mandates are grounded in reliable earnings data. By identifying true economic earnings, a QoE report streamlines negotiations and reduces the risk of post-close surprises.

    Next, we examine the core components that define a comprehensive QoE analysis.

    Securities are offered through Finalis Securities LLC, an independent entity from Zaidwood Capital. This content is for informational purposes and does not constitute investment advice.

    Core Components of a Quality of Earnings Analysis

    A quality of earnings report for mid-market deals goes beyond audited financials to uncover the true recurring cash flow a buyer can rely on. In this section, we break down the three pillars of a quality of earnings analysis: normalization adjustments, working capital scrutiny, and EBITDA sustainability. Drawing on Zaidwood Capital’s due diligence expertise, we show how each component strengthens deal-making for institutional and private investors.

    Normalization Adjustments and Add-Backs

    Normalization adjustments strip away non-operational or inflated expenses to present a clean EBITDA. These adjustments are critical because audited financials may include non-recurring gains or expenses that distort the company’s sustainable earning power. In our analyses, we identify above-market owner compensation, one-time legal fees, personal expenses run through the business, and related-party transactions at non-market terms.

    • Owner’s Compensation Adjustment: Aligning above-market owner salary and benefits to industry-standard compensation for a replacement manager
    • Non-Recurring Expenses: One-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition
    • Personal Expenses: Personal travel, entertainment, vehicles, or family members on payroll not related to business operations
    • Related-Party Transactions: Above-market rent, management fees, or service charges paid to entities owned by the seller or their family

    We substantiate each adjustment with corroborating evidence—payroll records, lease agreements, invoices—and provide a clear rationale in our reports. A quality of earnings analysis also flags off-balance-sheet liabilities like operating leases or contingent obligations that can alter deal value. For example, an owner drawing $600,000 when market rate is $200,000 inflates expenses by $400,000, a typical adjustment we see. By documenting every add-back, we give buyers confidence in the normalized earnings figure. Additionally, QoE reports look beyond the balance sheet to identify contingent payments or environmental indemnities that may not be booked but represent real future cash outflows.

    Working Capital Analysis and Debt-Like Items

    Working capital analysis determines the normalized net operating capital needed post-acquisition. We assess seasonal needs, payment cycles, and industry norms, then compare that to the target company’s actual levels. The gap—whether surplus or deficit—becomes an adjustment to the purchase price. For instance, if a business has excess working capital relative to its normalized requirement, the buyer may credit the seller for that amount at closing; conversely, a deficiency reduces the price. Our QoE reports present these adjustments with supporting schedules so that both buyers and sellers can negotiate from a common understanding.

    Debt-like items are obligations that function as debt but are not on the balance sheet as such. Examples include deferred revenue, underfunded pensions, or installment sale obligations. We identify these, quantify their impact, and deduct them from the equity value, just as we would formal debt. This analysis prevents the buyer from inheriting hidden financial burdens and ensures the enterprise value accurately reflects the business’s true financial position.

    EBITDA Quality and Sustainability Assessment

    EBITDA sustainability evaluation dissects the recurring nature of earnings. We examine revenue concentration risk—if a company depends on a single customer for more than 10% of revenue, that concentration creates vulnerability. Customer retention trends, contract renewal probabilities, and churn rates indicate how sticky the revenue base is. We also assess margin stability, checking whether gross and operating margins are sustainable or eroded by pricing pressure. In emerging markets M&A, we place extra focus on revenue concentration and retention because currency swings, regulatory shifts, and political instability can quickly reshape earnings. We evaluate supplier relationships to ensure margins are not artificially supported by short-term concessions, and we consider macroeconomic trends that could influence future earnings. Through our QoE reports, we help buyers distinguish durable cash flows from those that could evaporate post-acquisition, providing a forward-looking perspective essential for informed investment decisions.

    Selecting a Quality of Earnings Provider for Your Mid-Market Deal

    A quality of earnings report for mid-market deals is one of the most important tools for de-risking an acquisition, and choosing the right provider directly influences the credibility of your financial analysis. For companies in the $20M–$100M revenue range, the provider’s expertise, speed, and post-engagement support can make a material difference in how the QoE findings are received by lenders, underwriters, and counterparties.

    Evaluating Boutique Firm Expertise for QoE Analysis

    Boutique firms such as Zaidwood Capital specialize in delivering a highly tailored Quality of Earnings analysis that aligns with the specific dynamics of mid-market transactions. Their teams typically bring deep industry knowledge and direct senior partner involvement, ensuring that the engagement is led by an experienced professional who understands both the financial and strategic dimensions of the deal. In contrast, Big Four accounting firms offer a broad, generalist approach with standardized QoE templates that can miss the nuances of niche sectors. Mid-tier regional firms occupy a middle ground, providing moderate specialization but often with less senior oversight than a dedicated boutique.

    The critical differentiator is the level of partner engagement. At a boutique, the senior team leads the QoE analysis from start to finish, which shortens feedback loops and results in a more focused report. Big Four firms typically rely on junior staff for the bulk of the fieldwork, with partner review at the conclusion, while mid-tier firms show variability in senior involvement. This direct access to senior talent often translates into faster turnaround times and more actionable insights for the acquirer.

    The following comparison table summarizes key distinctions to inform your selection.

    Common Add-Backs and Adjustments in Quality of Earnings Reports
    Adjustment TypeDescriptionTypical EBITDA ImpactCommon Example
    Owner’s Compensation AdjustmentAligning above-market owner salary and benefits to industry-standard compensation for a replacement manager+$150,000 to $500,000 add-backOwner paying themselves $600,000 when market rate for a general manager is $200,000
    Non-Recurring ExpensesOne-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition+$50,000 to $300,000 add-back$200,000 in legal fees from a one-time litigation matter
    Personal ExpensesPersonal travel, entertainment, vehicles, or family members on payroll not related to business operations+$25,000 to $150,000 add-backCompany-leased luxury vehicle used primarily for personal use
    Related-Party TransactionsAbove-market rent, management fees, or service charges paid to entities owned by the seller or their family+$75,000 to $400,000 add-backPaying $30,000/month rent to a seller-owned LLC when market rate is $15,000

    Boutique firms consistently deliver deep specialization and hands-on partner involvement, often completing a QoE engagement in as little as 2–4 weeks—roughly half the time of a Big Four engagement. Moreover, firms like Zaidwood Capital adhere to established capital markets best practices, incorporating frameworks from ICMA capital markets to ensure the analysis meets rigorous industry standards. This commitment to both speed and quality makes boutique advisors a compelling choice for mid-market acquirers.

    Scope and Cost Expectations for Mid-Market Companies

    For a $20M–$100M-revenue company, the scope of a Quality of Earnings engagement should be calibrated to deal complexity and the acquirer’s specific concerns. A one-size-fits-all report rarely adds value; instead, the engagement scope must be defined collaboratively, focusing on revenue recognition policies, working capital trends, customer concentration risks, and any carve-out adjustments that could affect normalized EBITDA. At Zaidwood Capital, we work directly with buyers to design a custom scope that addresses the unique drivers of the target business, avoiding unnecessary line items that inflate cost without improving decision-making.

    Cost expectations reflect the level of customization. Boutique firms like Zaidwood Capital typically quote $25,000–$50,000 for a $20M-revenue company, while Big Four firms can range from $75,000 to over $150,000 for a similar-sized engagement. Mid-tier regional firms generally fall between $40,000 and $80,000. All figures are custom quotes and depend on data availability, the number of entities involved, and the speed required. We emphasize that our pricing is never a fixed fee; each engagement is priced based on the precise scope and timeline agreed upon, with full-cycle support extending from the initial QoE analysis through deal close.

    Integrating QoE Findings into Deal Structuring

    A Quality of Earnings report is not just a diligence artifact—it directly shapes the final deal terms. When normalized EBITDA adjustments reveal that reported earnings overstate true recurring cash flow, buyers can negotiate purchase price reductions or post-closing true-ups. Earnout structures become more defensible when the QoE identifies revenue volatility or concentration risks that warrant contingent payments. Similarly, representation and warranty insurance underwriters increasingly rely on QoE findings to set coverage limits and exclusions, making a thorough report a valuable risk-transfer tool.

    At Zaidwood Capital, our full-cycle advisory model ensures that QoE insights flow seamlessly into the negotiation and documentation phases. We translate EBITDA adjustments into specific purchase price adjustment mechanisms, design earnout milestones linked to verifiable financial metrics, and help acquirers present the QoE to insurers to secure favorable underwriting terms. This integrated approach reduces re-trading risk and accelerates the path to a signed purchase agreement. Once you have selected the right partner, the next step is implementing a disciplined QoE process that turns financial analysis into concrete deal terms. As with any investment, past performance does not guarantee future results, and we recommend consulting professional advisors to tailor the approach to your deal.

    How Quality of Earnings Reports Influence Purchase Price and Deal Terms

    A quality of earnings report for mid-market deals does more than flag accounting irregularities; it serves as the core negotiating lever for adjusting the purchase price and crafting protective deal provisions. At Zaidwood Capital, we treat the QoE report as the definitive source for reconciling reported financials with normalized economic reality. This alignment is essential before we engage in price discussions.

    In our experience, the most direct impact of the QoE report is a purchase price adjustment derived from normalized EBITDA. When the report strips out non-recurring revenue or one-time expenses, it recalibrates the basis on which the acquisition multiple is applied. A lower sustainable EBITDA can reduce the implied valuation, prompting the buyer to seek a price reduction. Conversely, a seller whose earnings prove clean and recurring can leverage the report to sustain or elevate the offer. Beyond EBITDA, the working capital peg—determined by historical QoE trend analysis—can shift the final cash consideration. If the report reveals that the target’s normalized net working capital is lower than originally represented, the buyer rightfully demands a dollar-for-dollar reduction at closing. Sellers with positive QoE results often use this as a shield against overly burdensome indemnification clauses, while buyers rely on the analysis to insert additional covenants or expand representations and warranties when risks are evident.

    Earnout structures are another area where QoE findings carry substantial weight. We typically link earnout payments to forward-looking financial metrics that have been validated by the quality of earnings (QoE) review. This ensures that post-closing milestones are both achievable and reflective of the business’s true earning power, reducing disputes later. Likewise, indemnification horizons and escrow amounts are calibrated to the specific risks flagged in the report. A revenue recognition issue might extend the survival period for related claims and increase the escrow holdback, while a clean report shortens those protections. Underpinning this rigor are regulatory standards that shape our financial analysis. FINRA securities regulation, administered by the Financial Industry Regulatory Authority, sets expectations for broker-dealer reporting that influence how we assess earnings quality in private transactions. Similarly, SEC securities regulation, enforced by the U.S. Securities and Exchange Commission, mandates GAAP compliance and reinforces the importance of accurate data in all valuations. In the following section, we demonstrate how these adjustments play out in a real mid-market transaction.

    Common Questions About Quality of Earnings Reports in Mid-Market Deals

    After establishing the importance of a quality of earnings report for mid-market deals, we address the most common questions buyers and sellers ask before engaging a QoE provider.

    What is a quality of earnings report, and why is it essential for mid-market deals? A QoE analysis examines earnings sustainability and quality, revealing adjustments needed in private-company financials and uncovering risks like customer concentration.

    How does a QoE differ from standard due diligence, and what adjustments does it uncover? Unlike standard due diligence, a QoE report serves as a complementary tool—used by advisors like Zaidwood Capital—to examine normalized EBITDA, margin trends, and working capital, separating recurring from one-time items and revenue mix.

    How does a QoE report impact valuation and deal structure? By surfacing these insights, a QoE can bridge valuation gaps and influence purchase price multiples, giving both sides clearer grounds for negotiation.

    Next, we’ll walk through the practical steps of commissioning a QoE report for your mid-market transaction.

    Leveraging Quality of Earnings Reports for Smarter M&A Decisions

    A Quality of Earnings report for mid-market deals dissects financials to expose sustainable earnings by stripping out one-offs. It flags risks like premature revenue booking, strengthening your negotiation position. Mid-market firms with less polished reporting especially benefit. At Zaidwood Capital, a quality of earnings report for mid-market deals anchors our full-cycle due diligence, alongside operational, commercial, and IT assessments, to deliver a complete picture. Compliance with SEC securities regulation ensures data reliability, and leveraging QoE minimizes post-close shocks. Deeper insight drives smarter M&A decisions.

    Resources

  • Get Venture Debt for Scaleups 2026: Fast Non-Dilutive Capital

    Get Venture Debt for Scaleups 2026: Fast Non-Dilutive Capital

    Table of Contents

    Venture Debt Opportunities for Scaleups in 2026

    Beyond general capital formation, a particularly compelling path for venture debt for scaleups in 2026 is the strategic use of non-dilutive growth capital. This form of debt capital allows companies to extend their cash runway and fund critical growth milestones without further eroding founder and investor ownership. By prioritizing growth metrics over traditional cash-flow underwriting, venture debt stands apart from conventional bank loans.

    Current market conditions make this window especially relevant. Reduced venture equity availability, coupled with favorable debt terms for well-performing companies, means debt financing serves as a powerful tool between equity rounds. In our debt advisory practice, we connect growth-stage companies with appropriate capital partners, leveraging our access to over 4,000 global investors and $15B+ in deployable capital. Understanding the opportunity is the first step; the next section outlines how we structure and execute these engagements.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. Book A Call for a custom venture debt consultation.

    Preparing for Your Venture Debt Strategy

    Now that you understand the advantages of venture debt, proper preparation is critical to securing favorable terms. For companies exploring in venture debt for scaleups 2026, readiness separates those who negotiate from a position of strength from those who accept whatever terms are offered. Thorough preparation signals to lenders that your business is a calculated risk, not a speculative one.

    We recommend our clients prepare the following key financial documents before approaching any lender:

    • Audited financials covering the last two fiscal years to demonstrate historical performance and accounting rigor
    • Twelve-month cash flow projections showing precisely how the debt will accelerate growth and when repayment capacity materializes
    • A clean, fully diluted cap table reflecting all equity rounds, option pools, and convertible instruments
    • A detailed use-of-funds memo tying every dollar to a specific growth milestone, whether a product launch or market expansion

    Lenders evaluate your application through specific metrics: annual recurring revenue (ARR), gross margin stability, monthly cash burn rate, and debt-service-coverage ratio (DSCR). According to Silicon Valley Bank services benchmarks, strong performance across these indicators often correlates with more flexible term structures. International Capital Market Association (ICMA) guidelines further emphasize the importance of transparent documentation in private debt placements.

    Venture debt functions as non-dilutive growth capital, allowing you to extend runway without surrendering equity. Unlike revenue-based financing, which ties repayments to top-line fluctuations, venture debt typically includes interest-only periods and may carry warrant coverage as standard structuring tools—not guarantees, but negotiable components.

    Vertical process flow diagram showing four steps for preparing a venture debt strategy: assess financial readiness, gather documentation, align strategy with milestones, and review lender criteria.

    Four-step venture debt preparation process flow

    Align your debt strategy with board-approved growth milestones and involve your CFO early. At Zaidwood Capital, our Debt Advisory team helps clients benchmark lender terms against current market standards, ensuring you approach conversations with the confidence that preparation provides. Once your strategy is fully prepared, the next step is approaching lenders with a compelling, data-backed narrative.

    Assess Your Capital Structure Needs

    Now that you understand the basics of capital structure, it’s time to assess your specific needs. How do you determine the right mix of debt and equity for your company? For scale-ups evaluating venture debt for scaleups in 2026, a structured self-assessment is the critical first step toward identifying the most suitable financing path.

    We guide founders through evaluating several key factors to build a coherent capital strategy:

    • Current debt-to-equity ratio: Understanding your existing leverage and its impact on future borrowing capacity
    • Projected cash flow: Assessing whether revenue streams can comfortably service debt obligations
    • Growth stage: Distinguishing between early-stage, scale-up, and mature company dynamics, each with distinct risk profiles and capital access
    • Purpose of capital: Clarifying whether funds are needed for working capital, an acquisition, or expansion initiatives

    Exploring non-dilutive growth capital options such as revenue-based financing can preserve ownership while funding growth. Engaging experienced venture capital consultants helps interpret these factors and design a structure aligned with your objectives.

    With your needs assessed, the next section explores the specific capital solutions that match your profile.

    Identify Leading Venture Debt Lenders

    To identify the right partner, scaleups should evaluate leading venture debt lenders based on their track record, industry expertise, and loan terms. For companies seeking venture debt for scaleups 2026, understanding the lender landscape is essential. Non-dilutive growth capital preserves equity while funding expansion, and revenue-based financing offers flexible repayment structures aligned with business performance.

    According to Zaidwood Capital, notable lenders include:

    • Silicon Valley Bank – Provides venture debt and banking services to technology and life sciences companies at all stages.
    • Hercules Capital – Specializes in growth-stage technology and life sciences companies with flexible financing solutions.
    • TriplePoint Capital – Offers debt financing and leasing to venture capital-backed companies across diverse sectors.
    • Western Technology Investment – Focuses on early to mid-stage technology and life sciences companies.
    • Oxford Finance – Provides senior secured loans to healthcare and life sciences firms.

    When evaluating lenders, scaleups should assess loan size range, interest rate benchmarks, warrant coverage, and repayment flexibility. At Zaidwood Capital, our network includes access to many of these lenders, and we can help match companies to the right partner. Once you have identified potential lenders, the next step is to prepare your approach.

    Prepare Your Financial Documentation

    Once you understand the types of capital available, preparing your financial documentation is essential when seeking venture debt for scaleups 2026. The following documents are critical:

    • Audited Financial Statements (last 3 fiscal years) demonstrate revenue stability and profitability trends.
    • Detailed Cash Flow Projections (12–24 months), especially for non-dilutive growth capital and revenue-based financing.
    • Corporate Tax Returns (last 2 years) validate financial health.
    • Current Debt Schedule (if applicable) lists existing loans or convertible notes.
    • Pro Forma Financials model the new venture debt’s impact on cash flow and leverage ratios.
    • Virtual Data Room with clear folder labels organizes all files for submission.

    For documentation standards, the International Capital Market Association provides a useful framework. Having these documents ready will streamline your capital raise. This information does not constitute investment advice. With your documents organized, you are ready to proceed with the application process.

    Structure the Deal Terms and Warrant Coverage

    Moving from an overview of venture debt, we now focus on the specific components that define a term sheet. When structuring venture debt for scaleups 2026, our team at Zaidwood Capital tailors each deal to the company’s stage and growth trajectory. A typical term sheet includes a maturity period of 3 to 5 years, an interest rate composed of a cash component plus payment-in-kind (PIK), and an upfront fee that covers due diligence and administrative costs.

    Warrant coverage — often ranging from 5% to 20% of the loan principal — provides the lender with equity participation without immediate founder dilution. We negotiate the strike price (typically set at the current preferred round price), the warrant term (commonly 5-7 years), and exercise rights to align incentives. This structure offers lenders upside while preserving non-dilutive growth capital for the company.

    Terms are calibrated to a company’s credit profile, revenue projections, and market stage; for instance, revenue-based financing considerations can influence the repayment schedule. Our full-cycle M&A and capital advisory approach ensures each element supports long-term scalability, which we will explore further in the next section covering the application process.

    Negotiate Covenants and Closing Conditions

    With your term sheet structured, the focus shifts to covenants and closing conditions — the final hurdles before funding. For a growth capital debt financing round, these terms define your operational boundaries and the prerequisites to access capital. In the 2026 landscape, venture debt for scaleups 2026 is an increasingly popular tool for companies seeking non-dilutive growth capital, but the protective mechanisms lenders require can significantly impact your financial flexibility.

    Covenants are contractual promises you make to the lender. They broadly fall into three categories:

    • Affirmative covenants: Actions you must take, like maintaining insurance or providing audited financials.
    • Negative covenants: Actions you cannot take without lender consent, such as incurring additional senior debt or selling key assets.
    • Financial covenants: Specific metrics you must meet, often a minimum cash balance or an EBITDA target.

    For a company using revenue-based financing, the financial covenants are typically tied to recurring revenue growth rather than static balance-sheet ratios. Zaidwood Capital’s advisory approach emphasizes aligning these tests with your realistic operating model. Closing conditions are the prerequisites you must satisfy before the initial draw. These can include a satisfactory legal due diligence review, board approval of the transaction, and delivery of a final legal opinion — standard steps that verify your company’s readiness for a full-cycle advisory engagement.

    We guide our clients to negotiate these terms with a pragmatic lens: insist on covenants that reflect your business’s actual trajectory, and build closing condition checklists with achievable timelines. Documenting all agreed terms in a commitment letter before moving to definitive documentation is a critical step. To discuss how we can help tailor these terms for your specific raise, we invite you to Book A Call with our team.

    Complete Full-Cycle Due Diligence

    As a prerequisite for securing non-dilutive growth capital such as venture debt for scaleups in 2026, we conduct full-cycle due diligence that serves as the intelligence backbone of every transaction. Our process is a comprehensive, integrated assessment spanning six core domains: financial, legal, operational, commercial, IT, and human capital.

    This approach identifies risks and uncovers hidden opportunities across the entire deal lifecycle. We tailor our methodology precisely to your transaction type—whether it is a buy-side M&A mandate, a sell-side divestiture, or a capital raise involving revenue-based financing. By leveraging our proprietary Sovereign Data Nexus, we enhance commercial and operational assessments with real-time market intelligence, positioning your company for stronger, more informed negotiations.

    Our full-cycle process is engineered to compress timelines and reduce transactional uncertainty, ensuring that every facet of the business is scrutinized before approaching our network of over 4,000 institutional investors. This diligence forms the foundation upon which we structure optimal deal terms, seamlessly connecting strategic insight with execution.

    Finalize Capital Deployment and Monitor

    Once capital is secured, the next critical phase is deploying those funds effectively. For clients utilizing venture debt for scaleups 2026, this means executing tailored agreements. We finalize the deployment process through precise document execution, coordinated fund transfers and direct alignment with the portfolio company’s treasury team. Whether the capital is structured as non-dilutive growth capital or revenue-based financing, our team manages the closing mechanics to ensure a seamless transition from commitment to working funds.

    Following deployment, our full-cycle mandate continues through a structured monitoring framework. We provide periodic performance reporting, access to our proprietary Deal Vault for real-time document review and regular strategic check-ins. Our oversight is powered by proprietary tools like the Sovereign Data Nexus—our integrated intelligence infrastructure—and the Velocity Matrix, which tracks transaction momentum. This commitment ensures we remain a long-term strategic partner, delivering tailored advisory long after the transaction closes. Our approach is a hallmark of our Full-Cycle M&A and capital advisory, streamlining transactions through Financial Services 3.0 efficiencies. Past performance does not guarantee future results.

    Overcoming Common Venture Debt Hurdles

    Securing venture debt for scaleups 2026 presents unique challenges, from stringent qualification requirements to complex term negotiations. We understand that navigating these obstacles can feel overwhelming, particularly when founders are focused on preserving equity and maintaining operational momentum.

    Qualification and Positioning

    A primary hurdle is demonstrating the revenue predictability and capital efficiency that lenders require. Many scaleups mistakenly apply before achieving the necessary financial milestones. To overcome this, companies must present clear growth metrics and a defensible business model. Accessing non-dilutive growth capital demands a narrative that aligns scalable unit economics with a realistic path to profitability, a positioning we help our clients refine.

    Term Negotiations and Structure

    Misunderstanding repayment structures is a common pitfall. We often see companies over-leverage by focusing solely on the headline amount rather than the amortization schedule and covenant package. This misalignment can strain cash flows at critical growth junctures. Revenue-based financing is one flexible alternative, but it requires careful modeling against projections to ensure it complements, rather than constrains, your growth trajectory. A successful strategy involves mapping debt service to specific, value-creating milestones to avoid triggering restrictive covenants.

    After securing growth capital, many firms look toward global expansion, pursuing emerging markets M&A as a subsequent step in their scaling journey.

    Our advisory approach at Zaidwood Capital, grounded in extensive institutional knowledge, directly mitigates these risks. We guide clients through due diligence, leveraging our network to secure terms that support rather than hinder growth. Unlike equity financing, venture debt is fundamentally a non-dilutive tool designed to extend your runway while preserving ownership. We invite you to Book A Call to discuss how we can structure a solution tailored to your specific growth milestones.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.

    Launch Your Venture Debt Journey with Confidence

    For scaleups evaluating venture debt for scaleups 2026, a new strategic path is emerging that protects your equity while fueling expansion. Venture debt is a form of non-dilutive growth capital designed to complement your existing equity rounds. Rather than trading away additional ownership, this approach offers revenue-based financing that aligns repayment with your company’s growth trajectory—giving you the resources to scale without surrendering control.

    At Zaidwood Capital, we structure this journey with precision. Through our Debt Advisory service and a global network of over 4,000 institutional investors, we help founders access the right capital for their stage. We tailor terms to each stage and leverage market insights from emerging markets and fintech trends strategically to align capital with your growth objectives. Book A Call to explore how venture debt can move your business forward.

    Resources

  • Global M&A Market Cap 2026: Key Trends and Forecasts

    Global M&A Market Cap 2026: Key Trends and Forecasts

    Table of Contents

    Global M&A Market Cap 2026: Projections and Outlook

    The outlook for the global M&A market cap 2026 suggests a year of renewed momentum as dealmakers adapt to a stabilized economic landscape. Industry consensus points toward a period of growth, fueled by the gradual normalization of interest rates, the deployment of significant private equity dry powder, and corporate confidence in strategic consolidation. These tailwinds are expected to elevate global M&A deal value forecasts 2026, positioning the coming year as one of recalibrated and purposeful transaction activity.

    In this environment, middle market M&A valuation multiples 2026 are projected to remain compelling. Our team at boutique M&A firm Zaidwood Capital believes this creates a unique equilibrium where sellers can achieve attractive exits while buyers gain access to high-quality assets at rational premiums. As a specialized advisory practice, we are built for precisely this dynamic, leveraging our $24.4B+ in aggregate transaction volume to guide clients through every phase of a deal.

    Our ability to connect opportunities with capital is reinforced by a global network of over 4,000 institutional and private investors, representing more than $15 billion in accessible capital. This scale of connectivity is a meaningful differentiator, particularly in a year where matching the right partners will define success. We anticipate that 2026 will reward firms that combine deep sector expertise with agile execution, and our full-cycle M&A and capital advisory capabilities are aligned to meet that demand.

    We look forward to helping our clients navigate this promising market. Please note that securities are offered through Finalis Securities LLC, a member of FINRA/SIPC, and Zaidwood Capital is not a registered broker-dealer. All investments involve risk, including the potential loss of principal. Past performance does not guarantee future results.

    The Fundamentals of Global M&A Market Capitalization in 2026

    Global M&A market capitalization represents the aggregate disclosed value of all merger and acquisition transactions completed within a calendar year, offering a vital barometer of worldwide corporate confidence and economic momentum. As we look toward 2026, global M&A market cap 2026 projections indicate a robust recovery and expansion across all major regions, driven by stabilizing interest rates and pent-up demand for strategic consolidation. Our team at Zaidwood Capital monitors these macro-level shifts closely, as they define the landscape in which we deliver Full-Cycle M&A and capital advisory services to our corporate clients and fund partners.

    We have synthesized data from authoritative industry reports to ground our analysis in verifiable projections. The following table presents a comparative view of estimated 2025 deal values and forecasted 2026 figures, drawing on insights from PwC advisory services and the Capstone Partners M&A Market Overview.

    Projected Global M&A Deal Value by Region (2025 vs 2026)
    Region2025 Estimated (USD T)2026 Projected (USD T)YoY Change
    North America$1.4T$1.6T+14%
    Europe$0.8T$0.9T+12%
    Asia-Pacific$0.7T$0.85T+21%
    Rest of World$0.25T$0.3T+20%

    A review of these figures underscores a broad-based expansion. North America is expected to remain the dominant market at an estimated $1.6T in 2026, sustaining a 14% growth trajectory that reflects ongoing corporate transformation and an active private equity community. Europe’s projected climb to $0.9T—a 12% increase—aligns with more supportive financing conditions and cross-border dealmaking. We observe that these global M&A deal value forecasts 2026 are not merely aspirational targets; they are grounded in observable pipelines and policy environments.

    Asia-Pacific stands out as the fastest-growing region by percentage, with a 21% surge projected to reach $0.85T in total disclosed value. This momentum is consistent with the region’s expanding digital economy, industrial consolidation, and government-led reforms that ease foreign capital participation. The Rest of World category, encompassing emerging and frontier markets, is also forecast to expand by 20% to $0.3T, reflecting heightened investor appetite for diversification and resource-linked assets.

    Bar chart comparing projected M&A deal values for 2025 and 2026 across North America, Europe, Asia-Pacific, and Rest of World
    Projected global M&A market capitalization by region for 2025 and 2026.

    Drilling deeper, we see that these regional patterns inform our advisory work, particularly when calibrating middle market M&A valuation multiples 2026 against broad market trends. While aggregate data from PwC’s 2026 report and Capstone Partners’ analysis provide a strategic overlay, we caution that these projections are estimates and not guarantees of individual transaction performance. Every deal requires tailored diligence and sector-specific benchmarking, a discipline at the core of our full-cycle methodology. Readers building on this regional foundation can next explore how sector dynamics and valuation frameworks shape middle market opportunities in the year ahead.

    Key Industry Drivers Shaping the 2026 M&A Landscape

    The global m&a market cap 2026 is expected to reflect a landscape profoundly reshaped by three powerful forces: the relentless advance of artificial intelligence, a resurgence in cross-border dealmaking, and the persistent reality of higher-for-longer interest rates. At Zaidwood Capital, our analysis of the ecosystem, supported by PwC’s latest forecasts, indicates that these drivers are not merely cyclical blips but structural shifts redefining how value is created, financed, and transacted. Understanding their interplay is critical for any stakeholder looking to deploy capital or execute a monetization event this year. We see these themes converging to create a period of both heightened opportunity and increased complexity, demanding a more strategic and data-driven approach to deal execution than ever before.

    AI Super-Cycle and Technology Sector Activity

    The artificial intelligence super-cycle is the single most significant catalyst in the technology M&A market, propelling a wave of consolidation that cuts across software, infrastructure, and platform businesses. According to PwC, the technology sector is poised for a 25-30% increase in expected deal value in 2026, a trajectory driven by incumbents racing to acquire generative AI capabilities and bolt-on machine learning assets. This isn’t a speculative bubble; it’s a mature strategic response. Large-cap tech firms are using their balance sheets to ingest innovative startups, while mid-market platform companies are rolling up niche players to create vertically integrated AI-powered suites. We see this drive particularly among our clients seeking Full-Cycle M&A and capital advisory services to navigate the complexities of these technology acquisitions, from due diligence on proprietary algorithms to valuation of recurring revenue models.

    The implications extend beyond headline-grabbing megadeals. The primary focus is on software consolidation, where established platforms acquire point solutions to embed AI into their existing software stacks. These strategic acquisitions are designed to capture data network effects and block competitors, making them highly contested. PwC’s data supports the view that platform roll-ups, rather than transformative megamergers, will define the bulk of 2026’s tech deal volume, with global m&a market cap 2026 benefiting from the premium valuations assigned to AI-enabled business models. The complexity of these deals, which often involve cross-border intellectual property transfers and novel regulatory scrutiny around AI, requires a new level of advisory rigor. Our approach, leveraging what we internally term our Sovereign Data Nexus, helps clients map asset quality and risk in these technology-driven acquisitions with a precision that is essential for post-close value realization.

    Beyond the technology sector, cross-border dynamics are fundamentally reshaping how and where deals are structured, as companies look past domestic borders for growth. According to IFLR’s in-depth coverage of M&A legal news, a recalibration of global supply chains and an evolving network of bilateral trade agreements are creating new, distinct transactional corridors. Our firm observes that this is not a uniform global rebound but a targeted reallocation of capital into markets offering regulatory clarity and strategic resource access. The energy transition, for example, is driving joint ventures between Western capital providers and critical mineral processors in emerging markets, a trend clearly highlighted in PwC’s 15-20% growth forecast for the energy and natural resources sector.

    Regulatory change acts as both a headwind and a tailwind in this environment. Stricter foreign investment review regimes in North America and Europe are lengthening deal timelines, yet at the same time, harmonizing accounting and legal frameworks in regions like the Middle East and Southeast Asia are lowering historic barriers. As reported in M&A legal news, the complexity of navigating these disparate regimes is one of the most significant challenges for dealmakers in 2026. This environment makes local expertise and institutional connectivity more valuable than ever. Leveraging our access to over 4,000 global investors, we facilitate capital introductions that help bridge the gap between domestic sell-side mandates and international buy-side appetite, ensuring that cross-border transactions are not just conceived but successfully closed.

    Interest Rate Impacts on Deal Structuring

    The sustained high-interest-rate environment has ceased to be a temporary shock and is now a permanent fixture of the deal structuring toolkit for 2026. The era of cheap, abundant leverage has given way to a more disciplined approach, directly impacting how transactions are capitalized and how risk is shared between buyers and sellers. We note that global m&a deal value forecasts 2026 are heavily contingent on this new normal, as the higher cost of senior debt compresses leverage multiples and reduces the equity returns that can be generated through pure financial engineering.

    This shift is profoundly altering the architecture of deals. To bridge often-significant valuation gaps between buyer and seller expectations in a high-rate world, we are seeing a significant rise in deferred consideration mechanisms. Earn-outs and seller financing notes have become standard negotiating tools rather than exotic compromises, allowing buyers to manage upfront cash outlay while sellers can achieve their target valuation upon hitting post-closing performance milestones. For instance, in the 10-15% growth projected by PwC for healthcare mid-market buyouts, middle market m&a valuation multiples 2026 are being sustained not by higher opening bids, but by structuring a greater portion of the enterprise value into these performance-linked instruments. Our advisory work is now deeply focused on modeling these structures, providing fairness opinions that deconstruct the probabilistic value of earn-outs to ensure our clients can make informed decisions under conditions of increased financial uncertainty.

    The sector-level impacts of these converging drivers are clear and measurable. The following table synthesizes PwC’s forecast data to illustrate how these forces are translating into specific deal activity and types across four pivotal industries.

    Sector-Level M&A Activity Drivers in 2026
    IndustryPrimary DriverExpected Deal Value GrowthTypical Deal Type
    TechnologyAI super-cycle and software consolidation25-30%Strategic acquisitions, platform roll-ups
    Energy & Natural ResourcesEnergy transition, decarbonization15-20%Asset acquisitions, joint ventures
    HealthcareDemographics, digital health innovation10-15%Mid-market buyouts, add-ons
    Financial ServicesRate normalization, fintech disruption8-12%Consolidation, divestitures

    What this table reveals is a divergence in deal rationale and structure based on macro-driver exposure. Technology’s AI-fueled 25-30% growth, the highest forecasted, is almost entirely a function of strategic imperative rather than financial optimization, leading to all-cash corporate acquisitions. By contrast, the more modest 10-15% growth in healthcare is being enabled by creative financial structuring—the mid-market buyout and add-on activity relies on the exact earn-out and seller-financing mechanisms necessitated by the interest rate environment. Across all sectors, the influence of global m&a market cap 2026 is evident, as even asset-heavy energy joint ventures require cross-border legal agility that sources like IFLR are tracking. Our role at Zaidwood Capital is to translate these macro-level drivers into a concrete transaction roadmap, ensuring that the strategy is matched by a robust, market-tested execution plan.

    Middle Market Valuation Multiples: What to Expect in 2026

    As we examine the landscape for deal-making in the year ahead, the trajectory of the global m&a market cap 2026 serves as a crucial backdrop for understanding where private transactions will price. Our analysis of current market data suggests that middle market valuation multiples are stabilizing, though significant dispersion exists across sectors. For business owners and investors navigating this environment, a clear understanding of these benchmarks is essential for setting realistic expectations before entering a process.

    Middle Market EBITDA Multiples in 2026

    Our review of current middle market m&a valuation multiples 2026 shows that EBITDA multiple ranges continue to reflect sector-specific growth profiles and risk assessments. According to M&A Science, a leading aggregator of transaction data, technology companies with recurring revenue models are commanding premiums, while asset-heavy industrials face more conservative pricing. A revenue multiple offers an alternative lens, particularly for high-growth businesses where profitability may be deferred in favor of market share expansion. The divergence between these two metrics often signals how buyers are weighing current cash flow against future potential.

    We are observing that platform acquisitions with scalable infrastructure and strong management teams consistently trade at the upper end of their respective ranges. The availability of detailed market intelligence from sources like M&A Science allows our team to benchmark client opportunities against thousands of completed transactions, ensuring that offer prices reflect both intrinsic value and prevailing market sentiment.

    The following table summarizes our estimated valuation ranges for 2026, drawing on data from M&A Science and Capstone Partners:

    Middle Market Valuation Multiples by Sector (2026 Estimate)
    SectorEBITDA Multiple RangeRevenue Multiple RangeTrend vs 2025
    Technology12x – 18x3x – 6xStable to slightly up
    Healthcare10x – 15x2x – 4xStable
    Industrials7x – 10x1x – 2xSlight compression
    Consumer8x – 12x1.5x – 3xMixed

    Technology continues to lead all sectors, driven by strong demand for AI and machine learning capabilities that generate predictable, high-margin revenue streams. Healthcare remains resilient, supported by demographic tailwinds and consolidation among provider groups. Industrials have experienced slight multiple compression as manufacturing slowdowns and supply chain uncertainties weigh on buyer confidence. Consumer sector multiples are mixed, with premium brands holding value while discretionary categories face headwinds from shifting spending patterns. Capstone Partners’ sector-level research confirms these diverging trends, with technology and healthcare expected to maintain or expand their valuation premiums through year-end.

    For acquirers evaluating opportunities, understanding these benchmarks is a foundational element of effective transaction planning. Reviewing these multiples is a key component of buy side M&A education, as it equips diligence teams to calibrate their financial models against real-world market evidence. Without this context, even sophisticated investors risk overpaying in competitive auctions or missing value in overlooked sectors.

    Global m&a deal value forecasts 2026 suggest that total transaction volume will remain robust, though deal count may moderate as buyers become more selective. This selectivity places a premium on quality assets, reinforcing the need for sellers to present clean financials, defensible market positions, and transparent growth narratives. Our advisory work increasingly focuses on helping clients articulate these value drivers well before going to market.

    Downward Pressure Factors on Multiples

    Despite generally healthy valuation levels, several headwinds are compressing multiples in certain segments. The Bonadio Group’s deal advisory insights highlight rising interest rates as the primary constraint, increasing the cost of acquisition financing and reducing the net present value of future cash flows. Regulatory uncertainty, particularly around cross-border transactions and sector-specific oversight, introduces additional risk that buyers are pricing into their offers. We also note that broader economic slowing has made revenue forecasting more difficult, prompting cautious assumptions in quality-of-earnings analyses.

    These pressures are most acute in capital-intensive industries where leverage is essential to achieving target returns. For companies in these categories, we are advising clients to consider alternative deal structures such as earn-outs or seller notes that bridge valuation gaps while aligning incentives post-closing.

    These valuation benchmarks directly influence how we advise clients on pricing and timing. By tracking where multiples are trending and understanding the macro forces at work, we help buyers and sellers position themselves for successful outcomes in a dynamic market. The next consideration, which we explore in the following section, is how to translate these valuation insights into concrete deal structuring and negotiation strategies that protect interests on both sides of the table.

    Past performance does not guarantee future results. All valuation multiples are market estimates and should not be construed as investment advice.

    Advanced Considerations: Structuring Deals in the 2026 M&A Environment

    As the global M&A market cap 2026 reflects cautious optimism, structuring agility has become a decisive advantage. Global M&A deal value forecasts 2026 indicate a modest recovery, while middle market M&A valuation multiples 2026 remain under pressure, prompting both buyers and sellers to seek innovative alignment mechanisms.

    The following table compares three common deal structures that our firm often deploys to address these market realities.

    Deal Structuring Approaches for 2026 Market Conditions
    StructureBest ForAdvantagesDisadvantages
    Earn-OutBridging valuation gapsAligns incentives, deferred riskComplex measurement and disputes
    Rollover EquityManagement retentionRetains expertise, aligns long-termDilution for buyer
    Mezzanine FinancingLeveraged buyoutsLower equity commitment requiredHigher cost of capital

    Each structure carries distinct trade-offs that must be weighed against specific transaction goals. Our deal advisory frameworks analyze these variables through rigorous financial modeling, ensuring that the chosen path optimizes both risk allocation and return potential across the capital stack.

    Earn-Out provisions help bridge valuation gaps by tying consideration to future performance. This aligns incentives and defers buyer risk, but disputes can arise if measurement criteria are ambiguous. Our advisory teams work closely with clients to define clear metrics and incorporate third-party validation, reducing potential for post-close conflict.

    Rollover Equity retains management and aligns long-term interests. Sellers gain continued upside while buyers benefit from expertise, though buyer dilution is a trade-off. Structuring rollover with vesting schedules tied to performance milestones further reinforces commitment and ensures a smooth transition.

    Mezzanine Financing offers a middle ground between senior debt and equity, lowering upfront equity commitments at a higher cost of capital. In the context of emerging markets M&A, such hybrid structures are vital for navigating currency and regulatory complexity. Our firm has facilitated over 800 million USD in mezzanine and venture debt, executing deals in under 60 days through a network of more than 4,000 institutional investors, delivering speed and certainty.

    These structures are informed by Zaidwood Capital’s proprietary strategic documentation, which underpins our full-cycle M&A and capital advisory, enabling a rigorous, data-driven approach to deal design.

    These structuring decisions set the stage for comprehensive due diligence and execution planning, where our focus shifts to validating assumptions and mitigating residual risks. By thoughtfully calibrating these elements, we position our clients to realize greater value and confidently navigate the complexities of the 2026 deal landscape.

    Frequently Asked Questions About Global M&A Market Cap 2026

    Following the market overview, we address your most pressing questions about deal activity in 2026.

    What shapes the global M&A market cap 2026? Global M&A deal value forecasts 2026 point to robust activity fueled by rate stabilization, regulatory shifts, and AI-led due diligence; middle market M&A valuation multiples 2026 remain resilient.

    Which firms are the top M&A advisors in 2026? For large-cap mandates, leading institutions include Goldman Sachs, JPMorgan, and Morgan Stanley; our full list of top M&A advisors details the firms shaping the landscape.

    To gain direct exposure, explore our Deal Vault with access to 4,000+ investors and $15B+ in deployable capital. While we streamline transactions, remember that all investments involve risk and Zaidwood Capital is not a registered broker-dealer. Book a call to start.

    The global M&A market cap 2026 is projected to rebound sharply as interest rates stabilize and corporate balance sheets unlock record levels of dry powder. Industry data points to global M&A deal value forecasts 2026 surpassing the $4 trillion threshold for the first time since 2021, driven by transformative consolidation in technology, healthcare, and energy transition sectors. Within this resurgence, middle market M&A valuation multiples 2026 are expected to remain robust—typically ranging between 7.5x and 9.0x EBITDA for premium assets—though widening dispersion between high-quality platforms and undifferentiated businesses demands rigorous due diligence. Market volatility and valuation complexity make strategic advisory essential: Zaidwood Capital combines proprietary data networks, access to over 4,000 institutional and private investors, and more than $24.4 billion in aggregate transaction volume to help clients navigate uncertainty with precision. Partnering with an experienced strategic advisor can turn these trends into tangible results.

    Resources

  • Choosing the Right Mezzanine Debt Structures: Key Considerations

    Choosing the Right Mezzanine Debt Structures: Key Considerations

    Table of Contents

    Understanding Mezzanine Debt Structures

    Mezzanine debt structures are hybrid financing instruments that sit between senior secured debt and common equity in a company’s capital stack. Often viewed as junior capital, mezzanine debt fills the gap when conventional senior loans reach their capacity. This content is for informational purposes only and is not an offer, solicitation, or investment advice. Zaidwood Capital LLC is not a registered broker-dealer.

    Mezzanine debt is a form of subordinated debt financing that typically does not require hard collateral. Instead, lenders are compensated with a higher interest rate and an equity kicker—often warrants or conversion rights—which provides upside participation in the borrower’s success. This combination of debt and equity features makes it a flexible tool for companies needing capital beyond what senior lenders will provide. By taking a junior position, mezzanine lenders assume greater risk but also capture more of the company’s value creation.

    Mezzanine debt structures commonly bridge funding gaps in leveraged buyouts, acquisitions, and growth capital transactions where senior debt limits are reached but equity dilution is undesirable. Unlike unitranche debt, which combines senior and mezzanine layers into a single facility, traditional mezzanine structures remain clearly subordinated and offer lenders deeper equity participation.

    Engaging a debt advisor can simplify the sourcing and negotiation of mezzanine terms. At Zaidwood Capital we connect clients to a network of over 4,000 institutional and private investors with more than $15 billion of deployable capital, streamlining the process. Zaidwood Capital’s global lending services provide access to institutional investors and specialized debt funds that may not be reachable through conventional banking channels. This access is critical for firms that lack existing relationships with mezzanine providers.

    Of course, every transaction depends on the company’s specific situation, and no outcome is guaranteed. Our role is to present options, not promise particular results.

    Mezzanine Debt in the Capital Stack: Position, Pricing, and Purpose

    Within this layered structure, mezzanine debt occupies a distinctive position as the bridge between senior secured loans and pure equity. We view mezzanine debt structures as a flexible layer that is structurally subordinated to senior lenders but holds priority over equity holders in repayment and asset claims. This middle placement means mezzanine investors take on a moderate-to-high risk profile, reflecting the fact that they are repaid only after senior obligations are satisfied, yet before any residual value flows to equity.

    The following comparison table highlights how mezzanine fits within the capital stack alongside senior debt and equity:

    Mezzanine vs Senior Debt vs Equity in the Capital Stack
    AttributeSenior DebtMezzanine DebtEquity
    Position in StackFirst claim on assets and cash flowSubordinated to senior, senior to equityLowest priority, residual claim
    Risk LevelLowModerate to highHighest
    Typical ReturnLIBOR + 200-400 bps10-20% blendedVariable, target IRR 20%+
    Control RightsCovenants onlyMay include warrants or conversionVoting rights and board seats

    Senior debt holds the first claim on cash and assets; equity sits at the bottom targeting 20%+ IRRs and holding voting control. Mezzanine debt sits between them, subordinated to senior but senior to equity, typically offering a 10–20% blended return through interest, PIK, and equity-linked features such as warrants or conversion rights. Its control rights can include board observation or conversion triggers, providing a middle path.

    The 10–20% blended return commonly seen in mezzanine debt structures arises from a mix of contractual interest payments, payment-in-kind (PIK) accruals, and equity upside through warrants or conversion rights. Because mezzanine sits below senior debt in the capital stack, its risk profile is elevated; investors accept that they will be repaid only after all senior obligations are met. For this reason, mezzanine debt is often categorized as subordinated debt financing. In certain transactions, lenders may combine the senior and mezzanine layers into a single unitranche debt facility, streamlining documentation and reducing execution complexity. At Zaidwood Capital, we evaluate these structures against a company’s cash flow projections and strategic ambitions to build capital stacks that align risk and return profiles with long-term objectives.

    Mezzanine financing is most frequently used when a company’s senior debt capacity is exhausted, yet equity dilution is undesirable. Typical use cases include growth capital for expansion, acquisition financing, leveraged buyouts, and recapitalizations where flexible capital bridges the gap between senior debt and equity without ceding control. At Zaidwood Capital, our global lending services encompass mezzanine debt as a core component of the capital solutions we design—integrating subordinated debt financing and, where appropriate, unitranche debt structures that combine senior and mezzanine layers to streamline execution. This approach allows us to tailor risk-return profiles that match a company’s cash flow dynamics and strategic goals.

    While senior debt offers security and equity captures upside, mezzanine debt bridges the two with a balanced risk-return profile, providing essential flexibility for growing companies.

    This website is for informational purposes only and is not investment advice.

    Structuring Mezzanine Debt for Acquisitions and Growth

    As we move from senior to mezzanine structures, the role of hybrid capital becomes central to bridging funding gaps in complex transactions. Mezzanine debt structures occupy a unique position in the capital stack, sitting below senior obligations but above equity. At Zaidwood Capital, we structure these instruments as part of our full-cycle debt advisory, delivering flexible junior capital solutions for acquisitions and growth. While we leverage our network of over 4,000 institutional investors to source capital, we are not a registered broker-dealer and do not offer investment advice — please consult your own advisors before making financing decisions.

    The following table compares three common junior capital solutions used in acquisition financing:

    Mezzanine vs Unitranche vs Subordinated Debt
    FeatureMezzanine DebtUnitranche DebtSubordinated Debt
    StructureTwo-tranche (senior + sub) or standaloneSingle blended loan (senior + mezzanine combined)Strictly junior to senior debt
    Pricing10-18% all-inLIBOR + 500-800 bpsLIBOR + 600-900 bps
    CovenantsIncurrence-based, may include equity kickerMaintenance covenants typicalLess restrictive than senior
    Best Use CaseAcquisition financing with hybrid return profileMid-market borrowers seeking simplified documentationBridge financing or recapitalizations

    Each solution serves a distinct purpose, and the choice depends on the sponsor’s appetite for complexity, covenant flexibility, and return targets.

    Typical Interest Rates and Terms in 2026

    Current market conditions make mezzanine financing particularly relevant, with all-in pricing typically ranging from 10% to 18%. This spread includes a cash pay component tied to benchmark rates — often LIBOR-based — plus payment-in-kind interest and an equity kicker in the form of warrants. According to Zaidwood Capital’s internal CADE FAQ, the precise split between cash and PIK depends on transaction risk, while the warrants enhance the lender’s yield to compensate for junior security. Upfront fees, prepayment penalties, and structuring charges are also common, and we work with borrowers to model these layers so the total cost of capital remains transparent. In 2026, sustained demand from private equity firms and family offices continues to support a borrower-friendly but disciplined underwriting environment.

    The Role of Mezzanine in Buy-Side Transactions

    Mezzanine debt structures shine in leveraged buyouts and growth-capital raises where senior debt capacity alone falls short of the required enterprise value. By layering a junior tranche, sponsors can increase total leverage without ceding control — an approach we use frequently when advising on buy-side mandates. For emerging markets m&a acquisitions, where projected transaction volumes may surge 15% annually, mezzanine provides a flexible bridge that absorbs country and currency risks while preserving equity upside. The equity kicker aligns lender and sponsor incentives, allowing the financing to behave almost as quasi-equity, which is valuable in high-growth sectors like fintech or renewables. Our debt advisory team draws on the firm’s CADE FAQ and transaction experience to calibrate the right mix of senior debt, mezzanine, and equity for each acquisition.

    Integrating with Unitranche and Subordinated Debt

    In more complex capital structures, mezzanine debt is often combined with unitranche debt or subordinated debt financing to optimize the cost and documentation burden. Unitranche — a single blended loan — appeals to mid-market sponsors with its simplicity and maintenance covenants, but it may lack the return-enhancing features of a standalone mezzanine piece. When we integrate mezzanine with subordinated debt financing, the subordinated layer acts as a bridge facility or recapitalization tool sitting just above equity, while the mezzanine tranche retains its hybrid character. This layered approach can lower the weighted-average cost of capital and satisfy both covenant-light investors and lenders seeking higher yields. Zaidwood Capital’s internal CADE FAQ highlights that such integrated structures are especially common in emerging-market M&A and resource-intensive sectors, where bespoke terms and patient capital are essential. Our role is to design the sequencing — senior, unitranche, mezzanine, subordinated — so that the overall package meets the client’s strategic and liquidity objectives.

    Practical Framework for Evaluating Mezzanine Financing Options

    With a clear understanding of mezzanine basics, we now present a practical evaluation framework. For executives and private equity sponsors, selecting the right financing structure is critical to maximizing returns and minimizing risk. Our advisory team at Zaidwood Capital has developed this decision-focused guide to help you assess whether mezzanine debt structures align with your acquisition strategy and capital stack requirements.

    When to Choose Mezzanine Over Senior Debt

    Senior debt typically reaches its limit at 3-4x EBITDA, constrained by collateral coverage and maintenance covenant requirements. When additional capital is needed to close a transaction or fund growth initiatives, but further senior lien capacity is exhausted, mezzanine financing becomes a strategic solution. Unlike senior lenders who require secured collateral, mezzanine providers accept an unsecured or subordinated position, relying on cash flow analysis rather than hard asset coverage. This flexibility proves essential when the target company has limited fixed assets but strong, predictable free cash flow.

    In our experience, the decision often comes down to a trade-off between cost and flexibility. While unitranche debt can offer a simpler, single-document structure that blends senior and subordinated tranches, it typically provides less flexibility than a bifurcated capital structure. A unitranche facility may restrict prepayment options and lack the warrant overlay that aligns mezzanine investors with equity upside. We recommend evaluating your specific covenant tolerance and exit horizon before choosing between these subordinated alternatives.

    Step-by-Step Structuring for Private Equity Deals

    Structuring mezzanine financing requires a methodical approach to balance the interests of sponsors, senior lenders, and subordinated investors. Our framework follows a five-stage process refined through over 300 completed transactions.

    Diagram showing five stages of a mezzanine financing evaluation process from initial mandate to post-closing monitoring with downward arrows connecting each stage

    Five-stage mezzanine financing evaluation process flow diagram

    The process begins with the initial mandate and underwriting phase, where we assess the target company’s credit profile, historical cash flows, and projected debt service capacity. This determines the appropriate sizing of the subordinated debt financing tranche, typically targeting a total leverage level of five to seven times EBITDA inclusive of senior debt.

    Next, term sheet negotiation addresses the critical economic and control terms. Warrant coverage—the equity kicker that enhances investor returns—is negotiated alongside the cash coupon and any payment-in-kind (PIK) toggle features. When negotiating warrant terms, it is important to ensure alignment with global capital market standards to maintain market conformity and facilitate syndication if needed. The amortization schedule for mezzanine is often back-end loaded, with minimal principal payments during the early years to preserve portfolio company cash flow. Legal documentation and the intercreditor agreement then codify the relative rights of senior and subordinated lenders, followed by closing, funding, and post-closing covenant monitoring.

    Benefits of Mezzanine in Acquisition Financing

    Mezzanine financing offers distinct advantages that make it a powerful tool in acquisition capital structures. Based on our proprietary benefit analysis, the most compelling attribute is its function as a bridge to equity without immediate dilution. Existing shareholders retain full ownership and control, while any equity participation via warrants is deferred and typically limited in scope. Unlike equity investors, mezzanine providers generally do not require board seats, preserving operational control for management.

    From a cost perspective, mezzanine debt structures carry an all-in cost of 10 to 18 percent, and critically, the cash interest component is tax-deductible. This contrasts sharply with equity financing, where investors target a 20 to 30 percent internal rate of return through capital appreciation and dividends that are not deductible to the company. The effective after-tax cost advantage makes mezzanine an efficient instrument for bridging valuation gaps in competitive auction processes.

    The following matrix helps executives compare mezzanine debt and equity on key decision criteria.

    Mezzanine Debt vs Equity: Decision Matrix for Acquisition Financing
    CriteriaMezzanine DebtEquity Financing
    DilutionMinimal (via warrants or conversion on limited basis)Full dilution of existing shareholders
    Cost of Capital10-18% all-in (tax-deductible interest)Target IRR 20-30% (higher required return)
    ControlNo board seats typically; covenants onlyInvestors often receive board representation
    FlexibilityPrepayment options vary, call protection commonExit required for liquidity; no redemption schedule
    Best ForCompanies with stable cash flow seeking bridge capitalHigh-growth companies needing strategic guidance and long-term capital

    This framework, informed by industry benchmarks and Zaidwood Capital case studies, provides a practical lens for evaluating trade-offs. The choice between subordinated debt and equity ultimately depends on your liquidity horizon, control preferences, and the underlying predictability of portfolio company earnings. To see how these structures work in practice, refer to our case studies below. This is for informational purposes only; consult your financial advisor before making financing decisions.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis. Past performance does not guarantee future results.

    Advanced Considerations: Risk Allocation, Leverage Ratios, and Investor Alignment

    Building on our earlier discussion of baseline financing options, we now turn to the sophisticated structural elements that define effective mezzanine debt structures. For sponsors and companies evaluating growth capital, understanding risk allocation, leverage benchmarks and alignment mechanisms separates a well-structured transaction from one that introduces unintended friction. We focus here on the analytical framework Zaidwood Capital applies when advising clients through these complex capital stack decisions.

    Risk Allocation and Intercreditor Dynamics

    Risk allocation in mezzanine financing centers on contractual subordination and the intercreditor agreement. This agreement governs the relationship between senior and mezzanine lenders, defining payment waterfalls, standstill periods and remedies upon default. Because mezzanine debt sits behind senior obligations, recovery in a downside scenario depends heavily on how these provisions are drafted. We structure intercreditor terms that preserve mezzanine lender rights while respecting senior creditor priority, ensuring each party understands its position before capital is deployed.

    Leverage Ratio Benchmarks Across the Capital Structure

    Leverage ratios, typically expressed as Debt/EBITDA, provide a common yardstick for assessing financial risk. The table below summarizes the benchmarks we observe across Zaidwood Capital transactions and broader industry data:

    Leverage Ratio Benchmarks by Debt Type
    Debt TypeLeverage Ratio (Debt/EBITDA)Typical Uses
    Senior Debt2.5x – 4.0xRevolving credit, term loans
    Mezzanine Debt0.5x – 2.0x (on top of senior)Acquisition bridge, growth capital
    Unitranche Debt3.5x – 5.5x (combined)Mid-market leveraged buyouts
    Subordinated Debt1.0x – 2.5xRecapitalizations, rescue financing

    These ranges illustrate how each debt layer contributes to total leverage. Senior debt anchors the structure, while mezzanine facilities layer on additional capacity, typically 0.5x to 2.0x above the senior component. For unitranche debt, the combined ratio reaches materially higher levels, creating a different risk-return profile for investors.

    Higher leverage amplifies equity returns but also increases vulnerability to earnings volatility. Recent SEC regulatory updates reinforce the need for transparent leverage disclosure and risk retention compliance, particularly for structures that push total leverage beyond historical norms. We monitor these regulatory developments closely, as they directly influence structuring options and documentation standards for mezzanine and subordinated debt financing.

    Investor Alignment Mechanisms

    Aligning interests between debt holders and equity sponsors requires deliberate structural features. Beyond the base coupon, we often incorporate PIK interest components that preserve cash flow for operational needs while compounding value for lenders. Warrants or equity co-investment rights give mezzanine investors participation in upside, matching their risk exposure with potential reward. Board observer rights provide visibility into strategic decisions without impairing management autonomy, and change-of-control provisions ensure lenders are protected — or compensated — if ownership transitions occur.

    These mechanisms transform a simple debt instrument into a partnership-oriented capital solution. Sponsors benefit from flexible financing terms while investors gain safeguards and upside exposure that senior creditors typically do not receive.

    In the next section we explore how these structural considerations feed into the due diligence process and real-world case examples.

    This content is for informational purposes only and does not constitute investment advice. Readers should consult their own legal, tax and financial advisors before making any decisions.

    Frequently Asked Questions About Mezzanine Debt Structures

    What Are Mezzanine Debt Structures?

    Mezzanine debt structures sit between senior secured debt and equity in a company’s capital hierarchy. This financing is typically unsecured and subordinated to first-lien lenders, meaning it carries higher risk but also commands higher returns. A key feature of mezzanine financing is its equity participation component — often through warrants or conversion rights — which gives lenders upside potential beyond fixed interest payments.

    How Does Mezzanine Financing Compare to Unitranche Debt?

    While both are flexible capital solutions, unitranche debt blends senior and subordinated tranches into a single facility with one blended interest rate. In a mezzanine debt structure, the layers remain distinct: a senior lender holds first priority, and the mezzanine provider sits behind them. Unitranche simplifies administration but may limit the equity upside that defines mezzanine financing.

    What Are the Typical Uses for Mezzanine Debt?

    Companies commonly use subordinated debt to fund acquisitions, support growth capital initiatives, and execute recapitalizations. Because mezzanine financing does not require hard asset collateral, it is especially useful for businesses whose value lies in cash flows or intellectual property rather than physical assets. This flexibility makes it a go-to tool for middle-market transactions and sponsor-backed deals.

    How Does Mezzanine Debt Relate to Subordinated Debt Financing?

    Mezzanine debt is a form of subordinated debt financing, distinguished by its equity-linked features. All mezzanine instruments rank below senior obligations, but not all subordinated debt includes warrants or conversion rights. The additional return potential compensates mezzanine providers for their deeper position in the repayment waterfall.

    What Are the Main Risks of Mezzanine Financing?

    Because mezzanine debt is unsecured and junior to senior loans, recovery in a default scenario can be significantly lower. The higher interest cost also increases the financial burden on the borrower. However, for companies with stable cash flows and strong growth trajectories, the risk-return trade-off of a mezzanine debt structure can be strategically sound. Please note that all investments involve risk, and past performance does not guarantee future results; you should consult your legal, tax, and financial advisors before making decisions.

    Optimizing Your Capital Structure with Mezzanine Debt

    In our advisory work, we often position clients to benefit from hybrid instruments in mezzanine debt structures, which sit between senior obligations and common equity. This subordinated layer can strengthen the balance sheet while preserving ownership control.

    What Is Mezzanine Debt?

    We define this as subordinated debt financing that includes equity participation features, such as warrants, allowing lenders to share in upside without diluting founders prematurely.

    How It Optimizes Capital Structure

    By layering mezzanine capital above equity, companies reduce dilution and gain flexible repayment options like payment-in-kind interest. This bridge is particularly useful for acquisitions, management buyouts, and growth-stage expansion.

    Mezzanine vs. Unitranche vs. Senior Debt

    Feature Mezzanine Debt Unitranche Debt Senior Debt
    Position in capital structure Junior to senior, senior to equity Single blended tranche Most senior
    Interest rate type Higher fixed or floating with PIK Blended rate; typically floating Lowest, often floating
    Covenant strictness Fewer financial covenants Moderate Strictest
    Equity component Warrants or equity kickers common Usually none None
    Typical use case Acquisitions, buyouts, recapitalizations Mid-market LBOs, quick close Working capital, asset-heavy deals

    Unitranche debt blends senior and subordinated layers into one facility, while subordinated debt financing remains a more traditional second-lien or junior note. We help management teams evaluate each path against their capital needs and timeline.

    Trade-offs and Customization

    Mezzanine capital carries higher interest and potential equity give-ups, but it provides speed and fewer restrictive covenants than senior loans. Through our debt advisory services at Zaidwood Capital, we structure each facility to match a company’s cash flow profile without promising any specific outcome.

    This section is for informational purposes only and does not constitute investment advice. Consult your legal, tax, and financial advisors before making decisions. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Resources

  • Private Equity Continuation Funds: Complete Guide for Investors

    Private Equity Continuation Funds: Complete Guide for Investors

    Table of Contents

    Private equity continuation funds explained

    Private equity continuation funds are GP-led secondary transactions where a new fund vehicle is established to hold existing portfolio assets beyond the original fund’s term. These structures can be arranged as single-asset continuation vehicles or as multi-asset pools. The objective is twofold: they provide limited partners with an early liquidity mechanism while enabling the general partner to continue managing and growing the assets.

    In a typical transaction, the GP sponsors the new vehicle and offers existing LPs a choice — a cash exit at a reset valuation or the opportunity to roll their interests into the successor fund. This approach aligns incentives and can supply follow-on capital for further value creation.

    For fund managers, executing a continuation fund requires specialized capital-raising and placement capabilities. Learn more about our capital formation services. This is not investment advice — consult your professional advisors.

    How Private Equity Continuation Funds Work

    Private equity continuation funds, also known as GP-led secondary transactions, are sophisticated financial vehicles that allow general partners to extend their holding period for high-potential portfolio companies or assets. At Zaidwood Capital, we have observed a significant increase in GP-led secondary transactions as fund managers seek innovative ways to maximize returns for their investors. These structures provide liquidity options for existing limited partners while enabling continued value creation in promising investments.

    The core mechanism involves a GP initiating a GP-led secondary transaction by transferring assets from an existing fund into a newly formed continuation vehicle. This process typically includes both existing LPs and new institutional investors, with the GP retaining a significant stake to demonstrate confidence in the assets’ future performance and align interests across all parties involved.

    Flowchart of a GP-led continuation fund transaction with five connected stages in a professional blue and gray palette

    GP-led continuation fund transaction process flow

    The transaction flow illustrated above demonstrates how these complex structures come together. The process begins with asset identification and valuation, followed by the formation of the new vehicle, capital raising from both new and existing investors, and ultimately the transfer of assets to the continuation fund.

    Financing plays a critical role in structuring these transactions, and debt advisory services from Zaidwood Capital can provide the necessary financing structures for these funds. According to Zaidwood Capital’s internal knowledge resources, our Full-Cycle M&A and capital advisory practice encompasses mezzanine debt, venture debt, and asset-based lending structures that support GP-led secondary transactions. With access to over 4,000 institutional investors and $15 billion in deployable capital, we help structure the optimal financing package for each unique situation.

    The valuation process requires rigorous fairness opinions and third-party advisory to ensure alignment with LP interests. Independent valuation firms assess the transferred assets to establish a fair market price, protecting all stakeholders involved in the transaction.

    Continuation funds can be structured as single-asset continuation vehicles or multi-asset vehicles, depending on the GP’s strategic objectives. A single-asset continuation vehicle focuses on one high-conviction portfolio company, while multi-asset structures consolidate several related holdings. These structures have become increasingly prevalent in today’s private equity landscape, offering flexible solutions for portfolio optimization and extended value creation timelines.

    GP-Led Secondary Transactions and Single-Asset Vehicles

    GP-led secondary transactions have become a defining feature of today’s private equity landscape, driven by the growing use of private equity continuation funds. In a GP-led deal, a general partner facilitates the sale of existing limited partner interests to new investors, often by transferring a portfolio company into a newly created continuation fund. This structure gives both continuing and exiting LPs greater flexibility than a traditional fund liquidation.

    A prominent subset of these transactions is the single-asset vehicle. Here, a single portfolio company is moved into a standalone fund, allowing the GP to hold a high-performing asset beyond the original fund’s life. This approach unlocks the runway needed for additional value creation while providing immediate liquidity to LPs who wish to exit. In our experience, these vehicles also enable more tailored governance terms and focused board oversight, which can accelerate strategic initiatives and operational improvements, provide clearer reporting metrics for investors concentrated on concentration risk and exit timing, and support alignment of incentives among continuing stakeholders while preserving LP choice and protections. We have seen demand for single-asset continuation vehicles increase significantly as GPs seek longer holding periods for prized assets.

    Why do GPs favor these structures? First, they can retain top-performing companies rather than selling them prematurely. Second, they raise follow-on growth capital to fund expansion or acquisitions. Third, they offer existing LPs a clear choice: cash out at fair value or roll their interest into the new vehicle. These transactions typically require independent valuations and approval from the LP advisory committee, ensuring alignment with capital market standards for secondary processes.

    At Zaidwood Capital, we advise clients on navigating these transactions from initial structuring through close. Our work in the private equity secondary market confirms that well-designed continuation funds balance the interests of all parties while capturing additional upside. The next section explores the valuation techniques that underpin fairness opinions in these evolving deal structures.

    Several interrelated factors explain this surge in popularity. We see that private equity continuation funds have become a cornerstone of liquidity solutions in 2026, driven by regulatory clarity, market demand for flexible exits, and the structural innovation of GP-led transactions.

    The U.S. Securities and Exchange Commission (SEC) has been a primary catalyst for this growth. SEC investor protection has been a key priority, with the SEC strengthening its initiatives to oversee GP-led secondary transactions. Through proposed rule changes and enforcement priorities, the regulator has clarified the framework for exempt offerings and secondary market activity, making it easier for fund managers to structure continuation vehicles that safeguard investor interests while providing much-needed transactional certainty.

    Market demand for liquidity solutions has further accelerated the trend. Institutional investors are increasingly turning to these structures to realize partial or full exits without triggering forced asset sales that could dilute returns. Private equity continuation funds give LPs the flexibility to recycle capital while GPs retain high-performing assets for further value creation. With fund lifespans extending beyond traditional horizons, the ability to execute gp-led secondary transactions has become essential for aligning the longer-term interests of managers and their limited partners.

    Structurally, the rise of single-asset continuation vehicles has been a defining feature of this cycle. These vehicles bundle a single portfolio company into a new fund, allowing the GP to extend the investment period and pursue additional growth while offering existing LPs the choice to liquidate or roll their interests. This targeted approach has gained traction as a flexible way to manage concentrated positions, reduce portfolio complexity, and align incentives without the legal and operational burden of full-fund restructurings. These examples show private equity continuation funds balance liquidity needs with longer-term investment horizons overall.

    Having examined the drivers, we now turn to the mechanics of these transactions and how they are structured to meet the needs of sponsors and investors alike.

    Benefits and Risks for LPs and GPs

    For GPs considering a continuation fund, the strategic advantages are compelling. Private equity continuation funds allow general partners to access liquidity from older fund portfolios without forcing a premature sale of assets that still have meaningful upside potential. We see this as a powerful tool that aligns interests by giving GPs the ability to extend their management of high-performing assets—particularly through the use of single-asset continuation vehicles—while simultaneously offering limited partners a clear choice between realizing gains and maintaining exposure. From an LP perspective, this structure provides valuable optionality. Rather than facing a binary outcome when a fund nears the end of its life, investors receive a liquidity event for their legacy fund interests coupled with the ability to roll over their commitment if they believe in the continued growth trajectory of the underlying portfolio.

    However, these transactions are not without complexity. One of the most persistent challenges lies in determining a fair market price for inherently illiquid assets, which requires rigorous third-party valuation work and independent fairness opinions. The inherent GP–LP conflict of interest sits at the center of every GP-led secondary transaction—the GP serves as both sponsor of the existing fund and, effectively, the buyer in the new continuation vehicle. To manage this, we advise clients to insist on transparent disclosure, independent governance structures, and the active involvement of legal and financial advisors who represent LP interests throughout the process.

    All GP-led secondary transactions are subject to FINRA regulatory compliance standards, including requirements for fairness opinions and transparent disclosure. When a broker-dealer such as Finalis Securities LLC is engaged, adherence to FINRA rules is mandatory. The Financial Industry Regulatory Authority (FINRA) establishes the regulatory framework that governs how securities firms involved in these transactions must operate, providing a baseline of investor protection through its oversight of disclosure practices, fair-dealing obligations, and conflict-of-interest management. This regulatory overlay reinforces the governance discipline that sophisticated LPs should demand.

    We emphasize that continuation funds are not risk-free. LPs should carefully evaluate the GP’s track record with similar structures, the specific governance protections built into the transaction, and whether the continuation vehicle genuinely aligns with their portfolio objectives. When structured thoughtfully and governed transparently, continuation funds can serve as a valuable liquidity and portfolio management solution—but the burden of due diligence rests squarely on all parties involved.

    This content is for informational purposes only and does not constitute investment advice or an offer, solicitation, or recommendation to transact. Investments involve risk and may be illiquid; investors may lose all or part of their investment. Zaidwood Capital LLC is not a registered broker-dealer. Securities are offered through Finalis Securities LLC, a separate entity.

    Best Practices for Evaluating Continuation Fund Opportunities

    Private equity continuation funds represent a growing segment of GP-led secondary transactions where a general partner transfers one or more portfolio assets from an existing fund into a new vehicle under the same management. While these structures can offer extended value-creation runway and fresh capital, they demand rigorous investor scrutiny to ensure the transaction serves limited partner interests fairly. We believe a methodical evaluation framework is essential for any LP assessing such opportunities.

    At the core of every analysis are several critical factors. First, we examine GP incentive alignment—specifically whether the manager is committing meaningful co-investment capital to the continuation vehicle and how the fee structure impacts net returns. Second, the fairness of the valuation process requires close attention, including whether an independent third-party opinion has been obtained and how the pricing compares to recent market benchmarks. Third, the composition and independence of the oversight committee or advisory board play a vital role in mitigating conflicts of interest, as does the transparency of disclosure around any existing GP–LP dynamics that may influence the proposed transaction.

    A thorough review must also consider the fund’s historical track record and the strategic rationale for retaining the asset rather than pursuing an outright sale. Investors should scrutinize the fee structure carefully, including management fees, any transaction-related costs, and the impact on carried interest calculations. Zaidwood Capital notes that evaluating the underlying financing terms is equally important, and our debt advisory team often helps clients analyze leverage arrangements embedded in continuation fund structures to ensure they align with long-term value-creation objectives. We also evaluate exit timing, market receptivity, and operational improvement plans to ensure the continuation path is realistic and achievable over time.

    These due diligence pillars—alignment, valuation integrity, independent oversight, and fee transparency—form the foundation of informed LP decision-making in GP-led secondary transactions. With these best practices in mind, our team can assist in structuring and vetting such opportunities.

    Key Takeaways and Next Steps in Continuation Fund Strategy

    Our earlier sections laid out how private equity continuation funds serve as flexible structures that extend fund life and deliver intermediate liquidity. These vehicles allow general partners to hold prized assets longer while giving limited partners options to roll over or exit.

    GP-led secondary transactions and single-asset continuation vehicles form the core of this strategy, aligning sponsor and investor interests through transparent pricing and governance. At Zaidwood Capital, we advise on structuring these transactions, from selecting the appropriate vehicle to managing the reinvestment process.

    As you evaluate your next move, you may consider:

    • Reviewing your current fund documents and limited partnership agreements for rollover provisions.
    • Weighing single-asset continuation funds against multi-asset GP-led solutions based on your portfolio concentration and return objectives.
    • Engaging a capital advisor experienced in secondary transactions and structured liquidity events.

    Our Continuation Fund FAQ details common questions, and we invite you to book a discovery call for tailored guidance on your specific situation.

    Resources