Table of Contents
- Understanding Bank Mergers in the United States
- Bank M&A Fundamentals: Economics, Drivers, and Deal Structures
- Navigating the Bank Merger Regulatory Approval Process
- Executing Bank Merger Integration: Strategies for Success
- Advanced Topics in Bank Mergers and Acquisitions
- Frequently Asked Questions About Bank Mergers
- The Future of Bank M&A and Strategic Advisory
Understanding Bank Mergers in the United States
Bank mergers in the United States are a primary driver of industry transformation, enabling institutions to build scale, cut costs, and extend their market presence. For stakeholders evaluating these moves, a clear picture of how they work and why they happen is essential.
In the United States, bank mergers are the combination of two or more banking institutions into a single legal entity. Such transactions are typically driven by the pursuit of economies of scale, geographic expansion into new markets, or the need to comply with increasingly stringent regulatory frameworks—all of which can strengthen the combined organization’s competitive position.
- Current bank consolidation trends show regional banks merging to compete with the largest national players.
- Meanwhile, community banks often consolidate to pool resources and manage the rising costs of technology and compliance.
These transactions must also secure approvals from the Federal Reserve, OCC, FDIC, and relevant state agencies, adding a layer of complexity that underscores the value of expert advisory.
For any institution contemplating a merger, navigating these hurdles demands deep market knowledge. Beyond deal negotiation, the real test often comes during bank merger integration, where organizations must unify systems, cultures, and operations to realize the transaction’s full potential. That is where understanding what is an investment bank becomes essential — these advisors guide clients through valuation, due diligence, deal structuring, and regulatory compliance. We combine data from Sovereign Data Nexus with our Velocity Matrix to accelerate execution.
With this foundation, we can now examine how investment banks structure and execute these complex transactions.
Bank M&A Fundamentals: Economics, Drivers, and Deal Structures
Building on the role of investment banks, we now examine the fundamentals that drive bank mergers—a key force reshaping the financial landscape. These combinations seek economies of scale, revenue synergies, and improved competitive positioning. By combining operations, acquiring banks can reduce overhead, expand market share, and unlock value that neither could achieve independently. At Zaidwood Capital, our Full-Cycle M&A services guide clients through these complex transactions.
Investment banks—such as boutique firms like Zaidwood Capital—provide essential advisory services to structure and execute these deals. To understand what an investment bank does, see what is an investment bank.
Several key drivers fuel bank M&A, as outlined in the comparison table below.
| Driver | Description | Example Impact |
|---|---|---|
| Economies of Scale | Reducing cost-to-income ratio by merging back-office functions. | Cost savings of 15–25% of combined operating expenses. |
| Diversification | Expanding product lines and geographic footprint to reduce risk. | Higher fee income ratio; lower net interest margin volatility. |
| Regulatory Compliance | Spread fixed compliance costs across a larger asset base. | Reduction in compliance cost per dollar of assets. |
| Technology Modernization | Investing in AI, digital banking, and cybersecurity at scale. | Faster customer acquisition and lower IT unit cost. |
Economies of scale remains a primary rationale: by consolidating back-office operations, merging banks can reduce their cost-to-income ratio, with CFA Institute research indicating potential cost savings of 15–25% of combined operating expenses. Diversification through geographic or product-line expansion stabilizes earnings, lowering net interest margin volatility and boosting fee income ratios. Expanding into new geographies or offering wealth management and treasury services smooths revenue streams, making the combined institution more resilient to interest rate cycles. The fixed costs of regulatory compliance can be spread over a larger asset base, driving down the per-dollar compliance burden—an increasingly critical advantage. Technology modernization underpins many recent transactions; after a merger, the combined entity can invest more heavily in AI, digital banking, and cybersecurity, achieving faster customer acquisition and a lower IT unit cost. Successful bank merger integration demands seamless harmonization of systems and cultures to realize these technology benefits. Together, these drivers create a powerful case for consolidation, reshaping the competitive landscape for regional and national banks alike.
In terms of deal structure, three common arrangements dominate. Stock-for-stock mergers—the most prevalent—exchange the acquirer’s shares for the target’s equity, preserving cash and aligning shareholder interests. Cash acquisitions, often used when the buyer has ample liquidity, provide a clean exit for target shareholders. Mergers of equals feature shared governance and a balanced exchange ratio, though careful negotiation of management roles is critical. Each approach carries distinct tax, accounting, and governance implications that require expert advisory. We at Zaidwood Capital tailor these structures to each client’s strategic objectives, ensuring full-cycle steering from valuation through integration. Our Boutique M&A and Capital Advisory Firm brings cross-border expertise to navigate these complexities.
These bank consolidation trends reflect an industry-wide push for resilience and efficiency. Understanding how consolidation reshapes competitive dynamics helps dealmakers identify value creation opportunities. With a firm grasp of the economic drivers, we turn to the valuation methods used in bank M&A.
Navigating the Bank Merger Regulatory Approval Process
With a clear understanding of the strategic drivers behind bank mergers, we now turn to the regulatory landscape that governs these transactions. Navigating the regulatory approval process for bank mergers requires a thorough understanding of the agencies involved and their requirements. Our Full-Cycle M&A advisory includes guiding clients through these complexities.
Key Regulatory Bodies and Their Roles
The United States bank merger regulatory approval process involves several key agencies, each with distinct jurisdiction. The Federal Reserve Board has authority to approve mergers involving bank holding companies and state-member banks. The Federal Deposit Insurance Corporation (FDIC), which enforces key FDIC bank merger regulation, approves mergers involving insured state non-member banks. The Office of the Comptroller of the Currency (OCC) is responsible for national banks, while the Department of Justice (DOJ) reviews every transaction for potential antitrust concerns under the Clayton Act and Sherman Act. The Federal Reserve’s analysis emphasizes competitive effects and the convenience and needs of the community, while the OCC places particular weight on capital adequacy and future earnings prospects. The FDIC, on the other hand, evaluates deposit concentration and the potential impact on the Deposit Insurance Fund.
The following table summarizes each regulator’s role:
| Regulatory Body | Role in Bank Merger Approval | Key Considerations |
|---|---|---|
| Federal Reserve Board | Approves mergers involving bank holding companies and state-member banks. | Must consider competitive effects, financial condition, and CRA performance. |
| FDIC | Approves mergers involving insured state non-member banks and interstate mergers. | Assesses deposit concentration, community impact, and management capabilities. |
| OCC | Approves mergers involving national banks. | Evaluates capital adequacy, future earnings prospects, and convenience/needs. |
| DOJ | Reviews antitrust implications of any bank merger. | May challenge mergers that materially reduce competition in a relevant market. |
Understanding which regulator has primary oversight is essential, as filing requirements vary. For instance, applications to the Federal Reserve often require form FR Y-2, while the FDIC mandates Form 6300/04 for non-member bank transactions; the OCC uses the Interagency Bank Merger Act Application. Our team at Zaidwood Capital helps clients prepare these submissions correctly from the outset.
The Application and Review Process
The Bank Merger Act (12 U.S.C. § 1828(c)) requires pre-approval from the appropriate federal banking agency before any regulated merger can close. The process begins with a pre-filing consultation to discuss scope and concerns. Following this, the formal application is submitted with detailed financials, pro forma ratios, and a comprehensive description of the transaction.
Once submitted, the application undergoes inter-agency review. The primary banking regulator evaluates safety and soundness, competitive impact, and community convenience. The DOJ simultaneously reviews antitrust implications and may sue to block anticompetitive mergers. A 30-day public comment period follows, allowing community input. The agency weighs comments alongside its own findings and assesses the plan for bank merger integration as a sign of management strength.
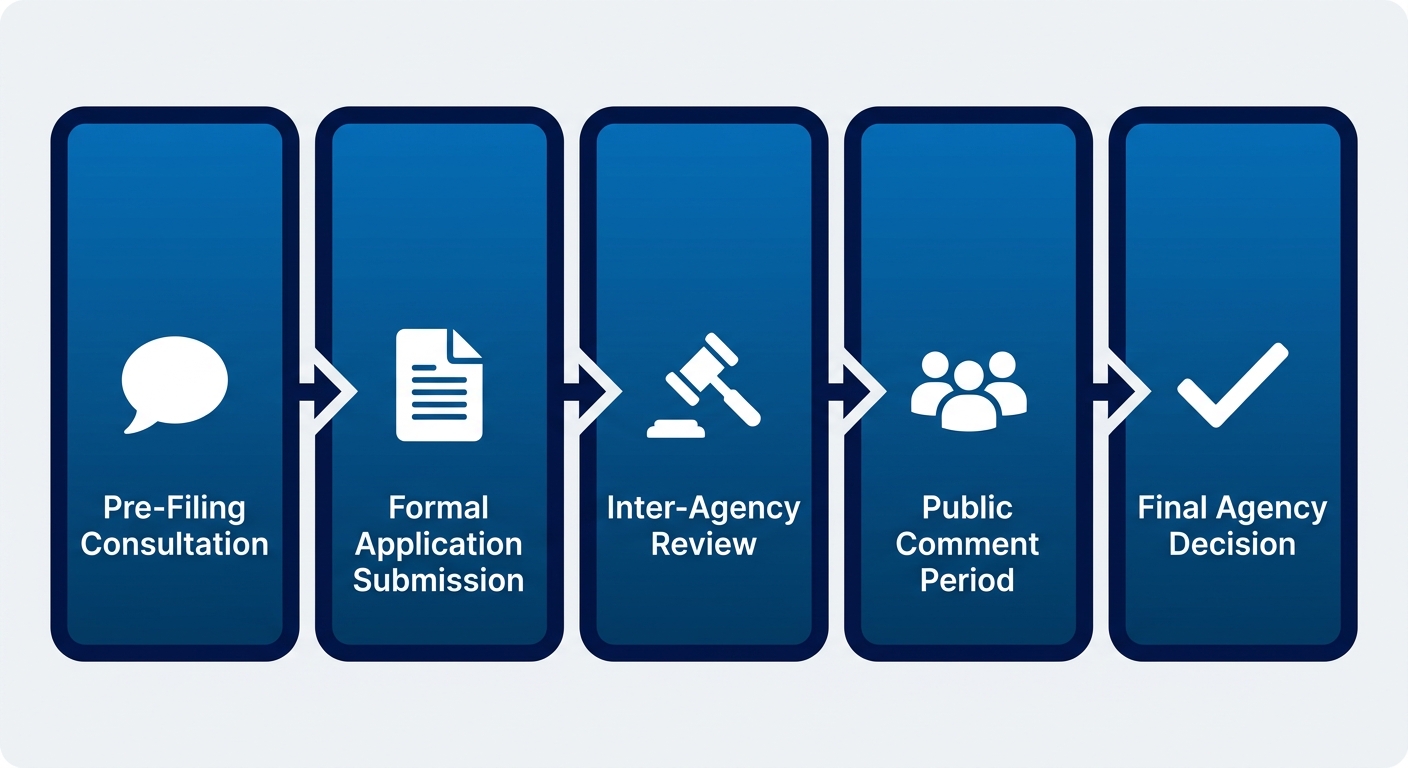
Navigating the bank merger regulatory approval process in five stages.
Throughout the review, our advisors leverage the Velocity Matrix to track milestones and ensure every regulatory request is addressed promptly.
Community Reinvestment Act Considerations
A bank’s Community Reinvestment Act (CRA) performance rating plays a critical role in merger approval. Regulators must consider the institution’s record of meeting the credit needs of its entire community, including low- and moderate-income neighborhoods. A rating of Outstanding or Satisfactory supports the application, while a rating of Needs to Improve or Substantial Noncompliance can trigger delays or outright denial. According to the FDIC, CRA performance is evaluated over a multi-year period and includes both lending and service activities.
To mitigate CRA-related risks, we recommend a thorough CRA self-assessment, strengthened community development lending, and robust documentation of community support. Glen Ellyn Bank’s M&A guide notes that early regulatory engagement on CRA issues can prevent last-minute surprises.
Timeline and Best Practices for Approval
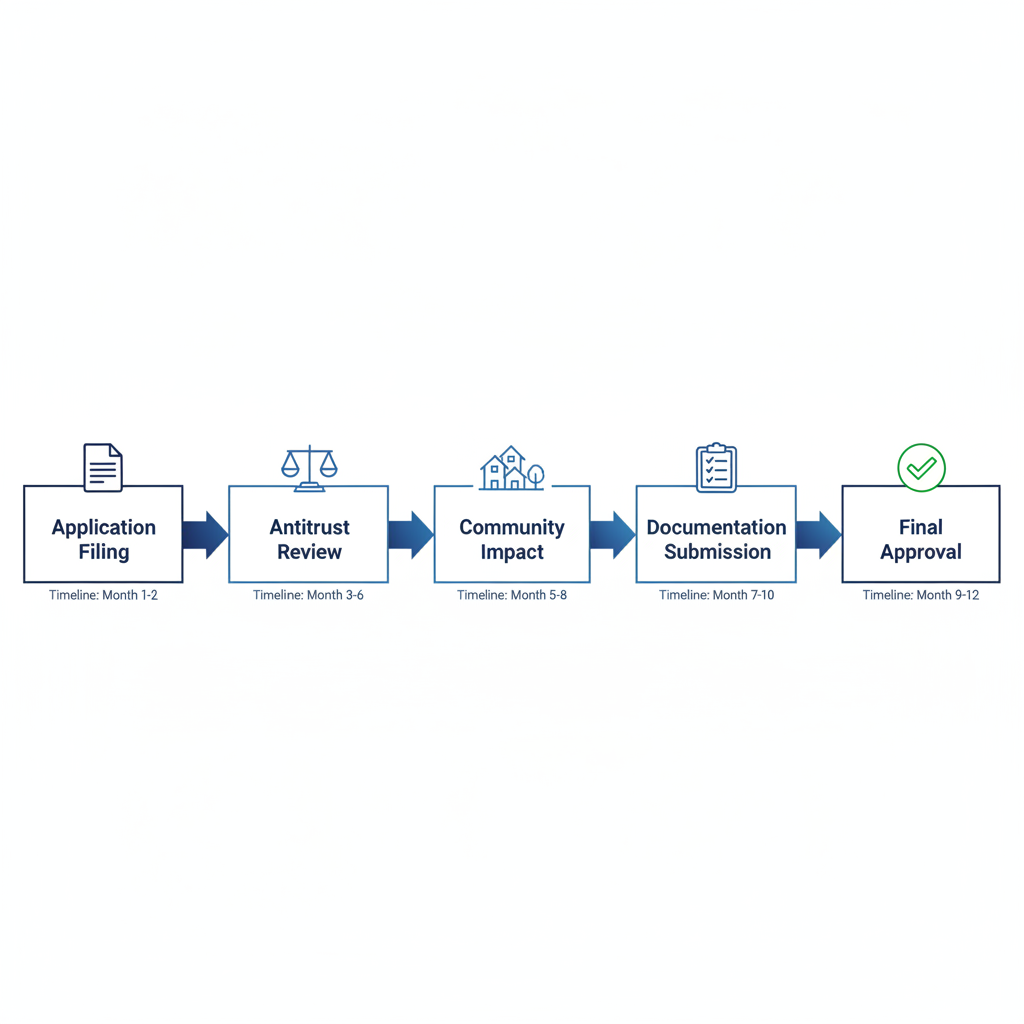
The approval timeline for a bank merger typically spans four to nine months. The initial review takes 30 to 60 days, followed by a 30-day public comment period, with a final decision within 60 to 90 days. Given current bank consolidation trends, the timeline may be influenced by market concentration data. Proactive measures accelerate the process. We recommend early communication with regulators, precise form preparation, CRA documentation, and community outreach. Our Velocity Matrix streamlines regulatory documentation and tracking to reduce delays. Once regulatory approval is secured, the focus shifts to integrating operations and capturing synergies—a topic we cover in the next section.
Executing Bank Merger Integration: Strategies for Success
After finalizing the deal structure, the critical phase of integration begins. Bank merger acquisition strategies 2026 must evolve beyond simple consolidation to address the complex interplay of people, processes, and technology. As a Boutique M&A and Capital Advisory Firm, we understand that the difference between a successful combination and a value-destroying merger often lies in the rigor and foresight applied during the first 100 days of integration. Success in bank mergers requires a dedicated framework that aligns leadership, retains essential talent, and consolidates core infrastructure without interrupting customer service or eroding market confidence.
Pre-Merger Integration Planning
Effective integration starts well before regulatory approval. We advise clients to establish a dedicated Integration Management Office (IMO) with clear decision-making authority at least 60 to 90 days prior to deal close. This team develops the blueprint that defines cost synergy targets—such as branch network consolidation and back-office efficiencies—and revenue cross-sell objectives across combined product lines. It is important to note, however, that projected synergies depend heavily on execution quality and market conditions; they can lead to significant value creation but require realistic baseline assumptions. The IMO should appoint workstream leads for operations, technology, compliance, and culture, each accountable for milestone delivery against a unified timeline.
Cultural and Operational Alignment
Cultural misalignment remains one of the most underestimated risks during bank consolidation trends. We recommend conducting structured cultural assessments of both institutions to identify gaps in leadership style, risk appetite, and employee engagement. From these findings, leadership should develop a joint cultural statement with input from employees at all levels—not just the C-suite. Retaining key talent is equally critical: early retention packages and transparent career pathing can significantly reduce regrettable turnover. For bank merger integration to succeed, operational alignment must complement cultural harmonization. This means consolidating branch networks within 90 days where overlap exists, standardizing policies and procedures, and creating a single operating model that frontline staff can adopt quickly.
Technology and Systems Consolidation
Technology integration represents both the greatest opportunity and the most substantial execution risk in bank mergers. We advocate a phased migration approach that prioritizes customer-facing digital channels and core banking platforms. Data integrity must be verified through rigorous parallel testing before any system cutover; a single data reconciliation error can erode customer trust and trigger regulatory scrutiny. Our Full-Cycle M&A methodology leverages the Sovereign Data Nexus to maintain secure, auditable data environments throughout consolidation. The sequence typically begins with email and communication systems, proceeds to treasury and risk management platforms, and concludes with long-term core banking migration. Testing protocols should include simulated transaction volumes, penetration testing for cybersecurity vulnerabilities, and fallback procedures for rapid rollback if anomalies appear.
The following table contrasts integration strategies across three critical dimensions: operations, technology, and culture.
| Dimension | Strategy | Key Success Factors |
|---|---|---|
| Operations | Consolidate branch networks and back-office functions within 90 days. | Clear communication to employees; unified policies and procedures. |
| Technology | Migrate core banking systems and data to a single platform. | Rigorous testing; data integrity checks; parallel runs before cutover. |
| Culture | Define combined values, leadership alignment, and retention programs. | Employee listening sessions; cultural KPIs in performance reviews. |
Operations consolidation delivers the fastest visible efficiencies, but technology migration creates the long-term platform for scalable growth. Culture, though hardest to measure, ultimately determines whether the combined institution can execute on the other two dimensions effectively.
Measuring Post-Merger Performance
Tracking integration progress demands a focused set of KPIs that link directly to deal thesis assumptions. We typically monitor cost synergy realization as a percentage of the original target, employee turnover rate (with particular attention to key-person retention), customer retention rate across product categories, and system downtime metrics during migration windows. Monthly steering committee reviews should compare actual performance to the IMO baseline plan, with variance explanations required for any deviation exceeding 5%. Post-merger reviews conducted at six and twelve months help capture lessons learned and refine the integration playbook for future transactions. With these strategies in place, the focus shifts to monitoring and realizing the full deal value.
This content is for informational purposes only and does not constitute investment advice.
Advanced Topics in Bank Mergers and Acquisitions
When evaluating advanced aspects of bank mergers, it becomes clear that regulatory and integration complexities demand a strategic approach. At Zaidwood Capital, we apply our Full-Cycle M&A methodology to help financial institutions navigate these challenges effectively.
Navigating the Federal Reserve’s merger approval process is a critical first step. The Fed requires detailed applications, public comment periods, and thorough community impact assessments to ensure proposed combinations do not harm local credit access. Understanding the intricacies of Federal Reserve bank merger approval is essential for any institution considering a transaction. Drawing on our experience advising on healthcare M&A, we recognize that regulatory shifts—such as amendments to the Community Reinvestment Act and enhanced prudential standards—can significantly alter deal viability and integration planning. At Zaidwood Capital, we have observed how these evolving rules reshape the competitive landscape and require proactive compliance strategies.
Once regulatory clearance is obtained, achieving successful bank merger integration proves to be the most complex phase. Cultural misalignment between organizations, the consolidation of disparate technology platforms, and the harmonization of compliance frameworks pose substantial operational risks. For instance, merging loan origination systems and aligning risk management protocols can delay synergy realization. We guide clients through these integration hurdles by employing disciplined project management and deep industry insight, helping to capture the promised efficiencies of the merger without disrupting customer service.
Capital raising forms the foundation of many bank mergers. Our firm’s work in securing tailored financing for enterprise AI companies—ranging from equity rounds to structured debt solutions—demonstrates how bespoke capital structures can be adapted to meet bank acquisition funding needs. In the current environment, bank consolidation trends show increased activity among mid-sized institutions seeking scale and efficiency. As a Boutique M&A and Capital Advisory Firm, we deploy our Financial Services 3.0 methodology to structure capital raises that satisfy regulatory capital requirements and fuel post-merger growth. All advisory services are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.
Frequently Asked Questions About Bank Mergers
Here are answers to frequently asked questions about bank mergers. While bank consolidation poses unique challenges, we also advise on healthcare mergers and acquisitions.
How do investment banks assist in bank mergers? Investment banks provide valuation, due diligence, and negotiation support to guide institutions through complex bank mergers. As a Boutique M&A and Capital Advisory Firm, Zaidwood Capital tailors this advisory approach to middle-market transactions.
What does a bank merger process involve? The process includes target identification, due diligence, regulatory approvals, and post-merger bank merger integration. Each phase demands rigorous financial modeling and careful coordination—where our full-cycle M&A support proves vital.
What is driving current bank consolidation trends? Drivers include technology investments, cost synergies, and regulatory changes. Boutique M&A and Capital Advisory Firms like Zaidwood Capital help navigate these trends.
For personalized guidance on your bank merger, contact Zaidwood Capital.
The Future of Bank M&A and Strategic Advisory
Looking ahead, the dynamics in bank mergers are redefined by powerful macro forces. According to CFA Institute research, evolving capital requirements and fintech licensing reshape consolidation, while AI-driven due diligence and digital integration accelerate timelines.
As a Boutique M&A and Capital Advisory Firm in Financial Services 3.0, we leverage the Sovereign Data Nexus and Velocity Matrix to accelerate due diligence for bank merger integration. Precision Catalyst may assist in deal sourcing, though outcomes are not guaranteed. In bank consolidation trends, unpredictability persists, and past performance does not guarantee future results. Partnering with a forward-thinking advisory firm is therefore essential.