Zaidwood Capital

Tag: Buy-Side M&A

  • Best Buy-Side M&A Strategies for 2026

    Best Buy-Side M&A Strategies for 2026

    Table of Contents

    Streamlining Buy-Side M&A with Boutique Advisory

    Successful buy-side M&A demands a focused, personalized approach that large-scale institutions rarely deliver. A boutique M&A advisory services firm brings high-touch, full-cycle support to every phase of your buy-side acquisition strategy, from target identification through integration planning. We deploy proprietary tools like Sovereign Data Nexus for precise, data-driven screening and Precision Catalyst for targeted investor engagement. Throughout buy-side due diligence and negotiation, our Velocity Matrix accelerates execution without sacrificing rigor. With 80+ years of collective experience and a global network of over 4,000 investors, we streamline complex buy-side mandates into disciplined, efficient outcomes, and tailored integration playbooks when needed — extending directly into the rigorous due diligence that follows.

    1. Master the Buy-Side Process

    For acquirers, the first fundamental is mastering the buy-side M&A process—the sequence of actions a buyer takes from target identification to closing.

    A well-defined buy-side acquisition strategy anchors every step, from target screening and initial due diligence through valuation analysis and negotiation. During buy-side due diligence, our team uncovers risks and validates assumptions; this layered investigation continues well beyond the initial phase, intensifying as we arrange financing and approach final due diligence and closing. As a boutique M&A advisor, we dedicate senior-level attention and proprietary execution resources—such as our Precision Catalyst and Velocity Matrix—to maintain transaction momentum while preserving the acquirer’s control over timeline and information flow. This structured framework reduces execution risk and ensures that each decision is driven by data, not haste.
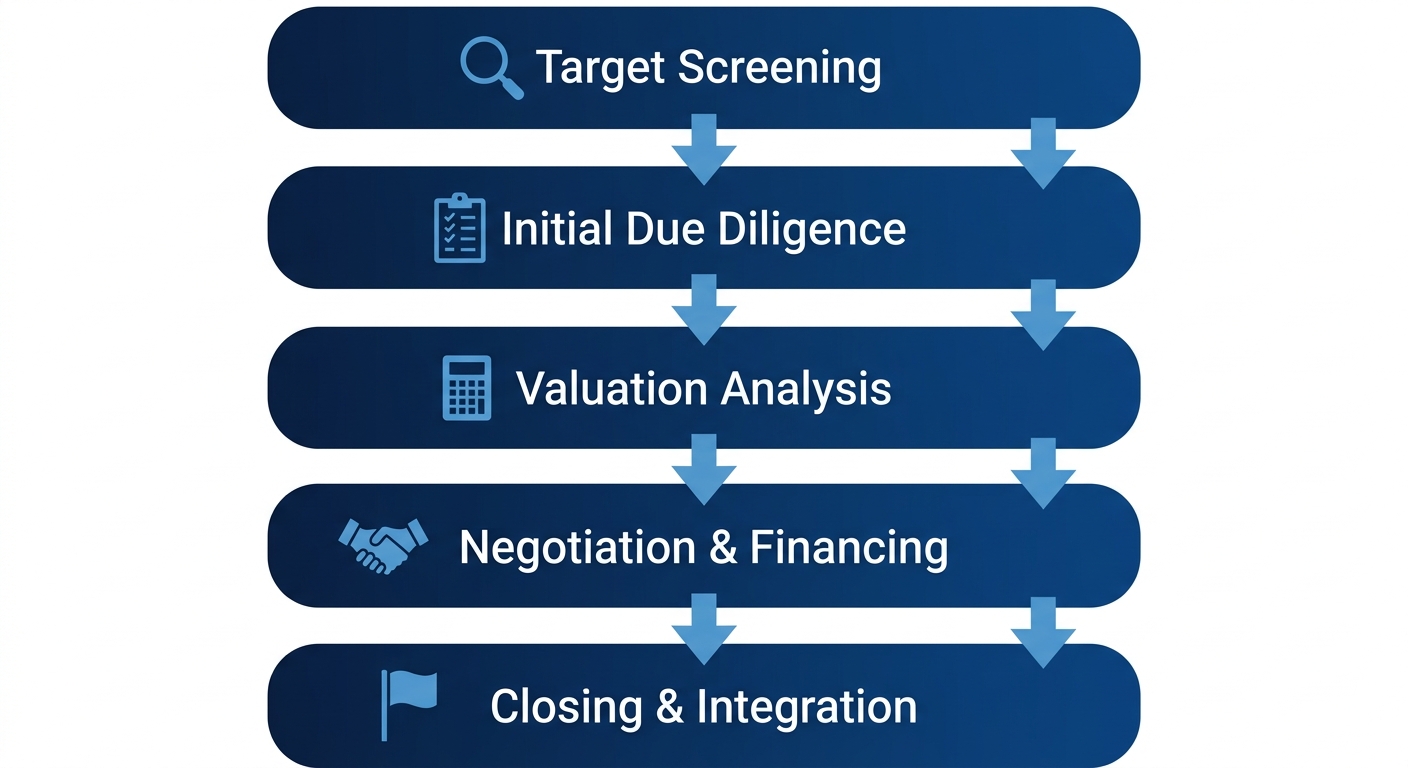
    Vertical process flow diagram showing five core stages of the M&A buy-side process: Target Screening, Initial Due Diligence, Valuation Analysis, Negotiation & Financing, and Closing & Integration.

    Five-stage M&A buy-side process flow with icons.

    A disciplined approach combined with an experienced boutique partner equips acquirers to navigate complexity with confidence, avoid reactive decisions, and pursue acquisitions that advance long-term strategic goals with precision.

    2. Follow Advisory Best Practices

    In buy-side M&A, adherence to professional standards separates trusted advisors from transactional facilitators. As a Boutique M&A and Capital Advisory Firm, Zaidwood Capital embeds industry-leading best practices into every engagement to ensure integrity and client focus.

    We follow the CFA Institute Code of Ethics and Standards of Professional Conduct, the global benchmark for ethical conduct in investment management. These standards demand integrity, competence, diligence, and respect in all client interactions. In our buy-side advisory work, we apply these principles by rigorously managing conflicts of interest, maintaining strict confidentiality, and conducting thorough buy-side due diligence. Every team member adheres to these standards, reinforcing our commitment to fiduciary duty and client-centric service. Our advisory best practices in buy-side transactions are built on these ethical foundations, ensuring that each mandate is handled with precision and care.

    These principles are embedded in our full-cycle M&A advisory process, which we detail next, and they inform every buy-side acquisition strategy we develop.

    3. Mitigate Key Transaction Risks

    Once opportunities are identified, the next critical step is mitigating key transaction risks. In buy-side M&A, proactive risk mitigation protects deal value and timeline.

    In healthcare mergers and acquisitions regulatory hurdles such as antitrust reviews under the Hart-Scott-Rodino Act, fraud and abuse laws (Stark, Anti-Kickback, False Claims Act), and HIPAA data privacy requirements can delay or derail transactions. Through rigorous buy-side due diligence that integrates our Sovereign Data Nexus, we scan proprietary regulatory databases to flag these risks early and structure mitigation steps before they become deal-breakers.

    Energy M&A transactions face distinct challenges, including environmental impact assessments, emissions compliance, foreign investment reviews (CFIUS), and local permitting delays. Our Velocity Matrix accelerates the mitigation timeline by coordinating counsel and compliance reviews so that these issues are resolved well before closing.

    Because each industry carries distinct risk profiles, a one-size-fits-all mitigation plan fails; we craft custom strategies that reduce exposure and enhance readiness without guaranteeing risk elimination. A robust buy-side acquisition strategy embeds these measures from the outset. With these risks addressed, the focus shifts to seamless execution and our full-cycle advisory ensures every stage is supported by data-driven insights.

    4. Source Prime Acquisition Targets

    In buy-side M&A, sourcing premium acquisition targets is the critical first step that determines the ultimate success of a transaction. Our disciplined approach begins by defining ideal criteria and activating proprietary sourcing channels to surface high-potential opportunities from the start.

    We focus on companies with annual revenues between $5 million and $50 million that exhibit strong recurring revenue streams, synergistic product-market fit, and audit-ready financials. Our buy-side acquisition strategy employs our Sovereign Data Nexus to conduct data-driven screening across broad markets, combined with active engagement in PE/VC portfolios and direct outreach at industry conferences. Once a shortlist forms, we initiate buy-side due diligence through a rapid vetting phase, leveraging our Velocity Matrix to filter unsuitable targets within 48 hours. Ensuring alignment between the buyer’s acquisition strategy and the target’s growth trajectory is paramount, as our Tech M&A guide details.

    This rigorous process maximizes the probability of pinpointing high-potential targets, allowing our clients to move toward transaction execution with confidence.

    Disclaimer: This content is for informational purposes only and is not an offer or solicitation to buy or sell securities. Zaidwood Capital is not a registered broker-dealer; securities, if offered, are through Finalis Securities LLC. Past performance does not guarantee future results; investments involve risk, including possible loss of principal. Consult your advisors before investing.

    5. Execute Thorough Due Diligence

    Once potential acquisition targets have been identified, the next critical phase in a successful buy-side M&A deal is rigorous due diligence. This systematic investigation goes far beyond a simple financial review, serving as the bedrock for risk mitigation and value confirmation.

    We conduct buy-side due diligence that examines multiple dimensions of the target company. Our process includes a deep dive into financial statements, legal contracts, operational capabilities, commercial positioning, tax structure, and regulatory compliance. We leverage our proprietary Sovereign Data Nexus platform to enable deeper data access and faster, more secure analysis. Our comprehensive m&a due diligence services provide the data visibility essential for evaluating risks and uncovering hidden value drivers.

    This disciplined approach is a cornerstone of any effective buy-side acquisition strategy. The insights generated help validate investment assumptions and may highlight potential deal-breakers before they become costly liabilities. While due diligence cannot eliminate all uncertainty, it significantly reduces it, and the findings directly inform valuation, negotiation strategy, and final deal terms.

    6. Understand Buy-Side vs. Sell-Side

    Having outlined the broad M&A landscape, it is critical to understand the two primary perspectives driving every deal. In buy-side M&A, a company acquires another to achieve strategic goals such as market expansion or technology acquisition. Sell-side M&A focuses on selling a company or assets to maximize shareholder value through preparation and buyer solicitation.

    We at Zaidwood Capital recognize that buy-side engagements center on target identification, valuation, and the thorough buy-side due diligence needed to assess a target’s financials and operations. A deliberate buy-side acquisition strategy guides this phase from search through negotiation. Conversely, sell-side mandates emphasize positioning, data room preparation, and term sheet negotiation, with the seller’s mindset shaped by value preservation and process control. Appreciating both sets of objectives helps parties anticipate each other’s motivations.

    Grasping these perspectives enables business owners to select an advisory partner who can navigate either role effectively. With this distinction in mind, the next step is to explore the rigorous due diligence process on the buy-side.

    7. Develop a Winning Acquisition Strategy

    In the evolving energy landscape, winning in buy-side M&A starts with a deliberate strategy anchored in three powerful drivers: consolidation among mid-size players, regulatory pivots toward renewables, and leaps in extraction technology. A sound buy-side acquisition strategy demands clear objectives—market share growth, technology acquisition, or geographic expansion—before evaluating targets. We align buy-side due diligence with those objectives, stress-testing financial health, operational readiness, and environmental compliance, not just checking boxes. Our proprietary Sovereign Data Nexus and rapid-execution Velocity Matrix surface intelligence that larger firms often overlook. Crucially, our research shows that cultural misalignment causes 70% of deals to underperform, so we map integration milestones early and we establish measurable KPIs and timelines to track integration progress and value realization after closing regularly. A disciplined plan, executed with a Boutique M&A and Capital Advisory Firm at your side, turns market complexity into realized growth.

    8. Choose the Right Advisory Partner

    With a clear strategy defined, the next critical step is selecting the advisory partner who can execute it. For a successful buy-side M&A, you need more than a broker—you need a team with proprietary sourcing intelligence, a global investor network, and full-cycle execution capability. We believe the right partner should distinguish themselves in four key areas.

    • Deal Sourcing & Data Access: The partner should offer more than a standard network. Our Sovereign Data Nexus provides private-server access to pre-qualified enterprises and institutional investors, giving your buy-side acquisition strategy an edge through data-driven targeting and thorough buy-side due diligence preparation.
    • Network Quality & Relevance: With connections to 4,000+ global investors and deep experience across healthcare, technology, and energy, our team can match your transaction to the right institutional or private capital.
    • Full-Cycle Execution: From strategic documentation—pitch decks, business plans, pro forma financials—to secure data room management and closing, our Precision Catalyst and Velocity Matrix frameworks are designed to accelerate your timeline without sacrificing rigor.
    • Compliance & Transparency: Securities are offered through Finalis Securities LLC, a registered broker-dealer. We are a separate, unaffiliated entity and make no outcome guarantees, ensuring you receive objective, compliant guidance.

    Accelerate Your Buy-Side Deal with Expert Support

    Accelerating your buy-side M&A deal requires the right combination of data, speed, and strategic insight — hallmarks of our approach at Zaidwood Capital. Our Sovereign Data Nexus powers deeper, faster buy-side due diligence, compressing weeks of manual research. By leveraging proprietary data, we uncover opportunities and mitigate risks faster than conventional methods. The Velocity Matrix framework compresses the deal timeline, enabling rapid execution even in complex transactions. Our Precision Catalyst leverages digital marketing to identify and engage acquisition targets, giving clients an edge. From strategic documentation and data room management to capital formation, our full-cycle M&A capabilities ensure a single partner can accelerate your transaction. Our team’s expertise is backed by top-tier investment management certification resources, ensuring we apply the highest standards to your deal. Our comprehensive buy-side acquisition strategy integrates these capabilities to deliver faster, more efficient outcomes. With hundreds of transactions advised and a global investor network, Zaidwood Capital is your partner for accelerated buy-side success. Explore how our full-cycle approach delivers results.
    Resources

  • Direct Lending Market Comparison: Top Private Capital Strategies

    Direct Lending Market Comparison: Top Private Capital Strategies

    Table of Contents

    Direct Lending Market: A Competitive Capital Source for Middle-Market Companies

    Middle-market firms facing rigid bank underwriting increasingly turn to the direct lending market for speed and flexibility. Unlike traditional bank loans, direct lending—provided by non-bank institutions—offers faster execution, covenant-light structures, and reduced regulatory hurdles. Our firm’s research confirms that borrowers value this private credit market for its ability to close deals swiftly.

    Current U.S. direct lending spreads remain competitive, attracting middle-market companies away from syndicated loans. Zaidwood Capital’s market intelligence shows direct lending integrates with broader private capital raising strategies, including GP-led secondary transactions that provide liquidity. Companies pursuing emerging markets M&A also benefit from direct lending’s speed and flexibility. In the following section, we outline how our team structures these customized solutions.

    1. Competitive Interest Rate Spreads

    In the U.S. direct lending market, borrowers seek competitive pricing amid tightening spreads. According to Zaidwood Capital’s market analysis, current all-in yields reflect the following typical ranges in basis points (bps):

    • Senior secured direct loans for mid-market transactions: SOFR + 400–600 bps.
    • Unitranche structures for high-quality sponsors: SOFR + 350–500 bps, while smaller or riskier borrowers may see spreads of +600–800 bps.
    • Second-lien or mezzanine tranches: SOFR + 800–1,200 bps.

    Spread compression over the past year has been driven by heightened competition among direct lenders, a trend we also observe in private capital raising strategies and GP-led secondary transactions. Deal size, credit quality, and leverage shape pricing, and our network enables us to secure competitive terms in the U.S. direct lending market. While spreads remain competitive, sponsors pursuing emerging markets M&A often face wider spreads due to higher perceived risk. These benchmarks directly influence the cost of capital across deal structures, a dynamic we navigate for every mandate.

    2. Flexible Financing Structures

    Beyond standard capital raising, we offer flexible financing structures that leverage the direct lending market to deliver faster execution and custom terms compared to traditional bank loans. As our internal FAQ on direct lending explains, this alternative to bank financing bridges gaps where conventional credit often falls short, especially for mid-market transactions.

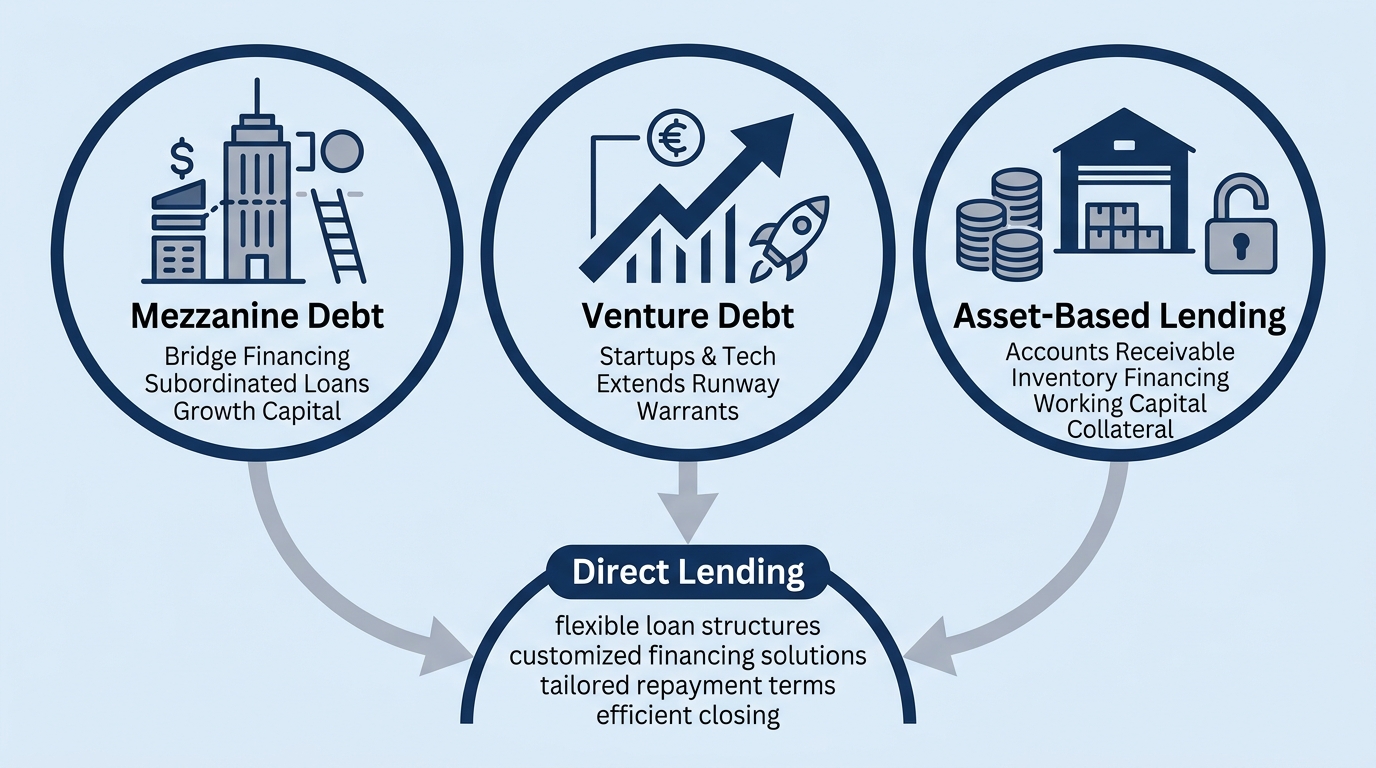
    Our tailored solutions encompass mezzanine debt, venture debt, equipment financing, and asset-based lending. Each instrument is custom-quoted to the client’s specific transaction, ensuring the right capital structure for growth, acquisitions, or liquidity. By operating in the direct lending market, we can craft flexible covenants and amortization schedules that align with your cash-flow profile. These structures support private capital raising strategies that go beyond one-size-fits-all bank terms.

    Infographic showing three flexible financing structures: mezzanine debt, venture debt, and asset-based lending connected to a direct lending hub.

    Flexible financing structures connected to direct lending.

    This flexible financing approach is designed to reinforce your buy-side M&A strategies with speed and precision, complementing our Full-Cycle M&A and capital advisory. To explore a custom-quote structure for your next transaction, Book A Call. This is not an offer or commitment; all financing is subject to due diligence and final documentation.

    3. Speed and Certainty of Execution

    In today’s direct lending market, speed and certainty of execution are decisive advantages for businesses evaluating private capital raising strategies.

    Traditional syndicated bank loans demand months of negotiation among multiple syndicate tiers and require extensive regulatory filings under SEC capital raising regulations; in stark contrast, direct lenders issue committed capital letters upfront and close in weeks, with fewer parties, less documentation, and a near-certain funding outcome.

    Zaidwood Capital’s proprietary market intelligence shows that current U.S. direct lending interest rate spreads remain favorable for borrowers, indicating that institutional lenders are actively seeking to deploy capital and can move swiftly when opportunities arise.

    Our approach to Streamlining Transactions shortens the search and negotiation cycle, and with a global network of over 4,000 investors, we accelerate execution for transactions ranging from corporate debt to GP-led secondary transactions, reducing opportunity cost and securing better terms.

    This speed and certainty, combined with Zaidwood Capital’s full-cycle advisory platform, streamlines access to substantial institutional capital for businesses pursuing growth.

    4. Middle-Market Capital Access

    Middle-market companies with revenues between $10 million and $1 billion frequently encounter a capital gap that traditional bank loans cannot fill, making access to capital in the direct lending market a vital alternative. As our FAQ notes, direct lending transactions close weeks faster than bank loans, with fewer covenants and flexible terms that adapt to a company’s cash flows rather than rigid formulas. Post-2008 regulatory changes constrained traditional bank lending, cementing the direct lending market as the core funding channel for mid-size firms. We help middle-market firms structure direct lending opportunities through our network of over 4,000 institutional investors and $15 billion in deployable capital, accelerating execution and reducing time-to-close. Beyond direct lending, our team deploys wider private capital raising strategies, including GP-led secondary transactions, to meet each company’s unique capital needs. Because direct lending operates under FINRA regulation direct lending, all participants must ensure strict compliance. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.

    5. Private Equity Buyout Support

    The direct lending market has become a cornerstone of private equity buyouts as firms seek speed and flexibility beyond traditional bank leverage loans. We at Zaidwood Capital see direct lender financing offering bespoke terms that align with the specific cash flow profiles of portfolio companies. This private credit approach sidesteps the rigid syndication processes of conventional banks, enabling faster closings and more creative capital structures. GP-led secondary transactions further illustrate how direct lending injects liquidity, allowing general partners to hold assets longer while offering LPs partial exits. Our private capital raising strategies incorporate direct lending solutions to support full-cycle buyout execution from acquisition through value creation. Direct lending also complements traditional bank financing by filling gaps where syndicated markets retreat, a dynamic we harness in our advisory work. As deal complexity grows, we view direct lending not as a niche instrument but as an enabling component driving the next phase of transaction structuring and capital deployment.

    6. Regulatory Landscape and Liquidity

    The direct lending market has experienced profound changes as regulatory oversight intensifies. Heightened scrutiny from the SEC and evolving risk-retention rules have dampened risk appetite among lenders, tightening liquidity dynamics across the sector. This shift is reshaping how capital flows into private credit.

    As bank-led lending retrenches, institutional capital increasingly pivots toward the direct lending sector. Stringent regulatory frameworks—including enhanced disclosure requirements and capital adequacy standards—drive allocators to reassess exposure. Our own analysis confirms that the regulatory environment compels investors to seek more resilient structures and transparency.

    These pressures have accelerated the adoption of private capital raising strategies and GP-led secondary transactions. By facilitating liquidity through secondary market solutions, managers can mitigate the constraints imposed by today’s regulatory landscape.

    Navigating this complexity demands deep market intelligence. Our firm leverages a network of over 4,000 institutional investors and $24.4B+ in aggregate transaction volume to help clients secure capital formation and liquidity in regulated markets. We help lenders and sponsors adapt their strategies, ensuring they remain positioned for success.

    7. Private Capital Raising Strategies

    For middle-market firms, private capital raising strategies offer an alternative to public markets, with the direct lending market serving as a vital source of flexible financing. These approaches enable capital formation for acquisitions, recapitalizations, and liquidity events while avoiding the regulatory complexities of an IPO.

    We help clients evaluate several private capital raising strategies:

    • Equity financing
    • Debt financing
    • Mezzanine debt
    • Direct lending
    • GP-led secondary transactions

    Direct lending, from non-bank institutional lenders, provides tailored capital complementing traditional bank loans. GP-led secondary transactions provide liquidity for limited partners while general partners can continue managing assets. At Zaidwood Capital, we design and execute these capital raises using our network of over 4,000 institutional investors and $15B+ in deployable capital, tailoring solutions to each firm’s profile. We integrate rigorous due diligence as part of our full-cycle M&A and capital advisory approach to ensure a seamless path from strategy to close.

    This site is for informational purposes only. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a broker-dealer.

    8. GP-Led Secondary Transactions

    In a GP-led secondary transaction, the general partner sells a portfolio company into a newly formed continuation fund backed by both existing and new limited partners. This approach, part of broader private capital raising strategies, provides early liquidity to LPs while allowing the GP to retain the asset and pursue additional value creation over a longer horizon. For careful LPs, these transactions offer a path to realize returns before a traditional exit; for GPs, they preserve management continuity and extend the runway for further growth.

    At Zaidwood Capital, we advise GPs on structuring these deals, securing institutional capital through our network of over 4,000 investors, and managing execution from start to finish. Our equity advisory and liquidity solutions practice ensures that each transaction is tailored to the fund’s objectives, streamlining transactions within our full-cycle M&A and capital advisory framework. Beyond GP-led secondaries, we support a spectrum of liquidity and capital formation strategies, including our broader equity advisory and debt advisory capabilities, positioned to serve mid-market funds across changing market cycles.

    Evaluating Direct Lending for Your Capital Strategy

    When evaluating the direct lending market, we recognize it as a private credit solution where institutional lenders provide capital directly to companies, bypassing traditional bank intermediaries.

    Direct lenders typically deliver faster execution, fewer covenants, and more flexible terms than banks—a key advantage when evaluating the direct lending market for companies with strong fundamentals seeking growth capital or acquisition financing without dilutive equity. Through direct lending, we streamline transactions, providing faster access to institutional capital. To determine fit, we assess the lender’s track record, deal flow, and alignment with your capital structure goals.

    As part of a broader set of private capital raising strategies, direct lending can complement other financing tools. GP-led secondary transactions frequently employ direct lending structures to facilitate liquidity or recapitalization.

    Resources

  • Best Quality of Earnings Report for Mid-Market Deals 2026

    Best Quality of Earnings Report for Mid-Market Deals 2026

    Table of Contents

    The Role of Quality of Earnings Reports in Mid-Market M&A

    Following a comprehensive due diligence review, buyers and lenders in mid-market M&A transactions focus on the Quality of Earnings (QoE) report, an independent assessment of a target company’s historical financial performance, adjusted for non-recurring items. This analysis goes far beyond audited financials by evaluating revenue sustainability, customer concentration, and the normalization of operating expenses and working capital. A well-prepared quality of earnings report provides a clearer view of recurring EBITDA, which serves as the foundation for valuation and debt sizing.

    Why QoE Matters in Mid-Market Deals

    The insights from an earnings quality analysis routinely reshape transaction terms. Buyers use the adjusted EBITDA to support purchase price adjustments, earnout structures, and net-working-capital targets. Lenders, in turn, demand a validated earnings baseline before committing acquisition debt. Moreover, the QoE often uncovers deferred-revenue patterns or concentration risks that, if ignored, can surface as costly post-close liabilities. In mid-market transactions where information gaps are common, a thorough QoE report reduces post-close surprises and gives the commissioning party a stronger negotiating position.

    Because mid-market companies frequently lack the internal resources to produce a GAAP-independent earnings analysis on their own, many engage specialized M&A advisors to manage the QoE process. At Zaidwood Capital, we integrate the QoE directly into our full-cycle due diligence offering, coordinating with independent accounting firms to deliver a report that buy-side and sell-side clients can rely on during negotiation and financing. We handle all financial data in accordance with rigorous confidentiality standards. For information on how we protect client information, please review Zaidwood Capital Privacy Policy.

    What Defines a Quality of Earnings Report

    A critical subset of due diligence, central to mid-market transaction diligence, is the Quality of Earnings Report, a financial analysis that evaluates the recurring, normalized earnings of a target company. At Zaidwood Capital, we define a QoE report as a rigorous assessment of earnings sustainability, designed to strip out non-recurring items and present a true picture of operating performance. This analysis is a cornerstone of our full-cycle due diligence process for mid-market M&A transactions.

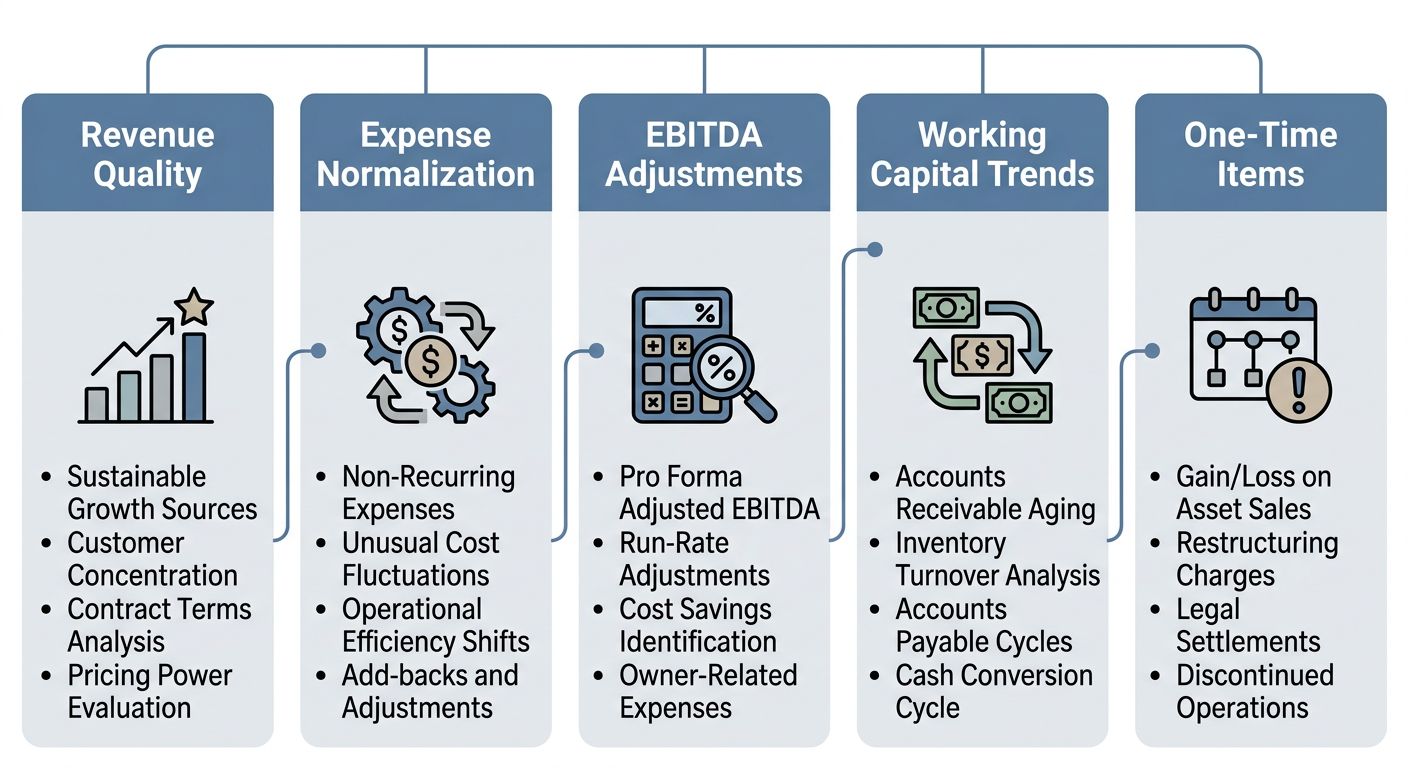
    A comprehensive earnings quality analysis examines several critical areas. Revenue quality scrutinizes the predictability and diversification of income streams. Expense normalization adjusts for one-time costs, owner’s compensation, or other out-of-ordinary expenses. EBITDA adjustments remove non-operating or non-cash items to reflect sustainable earnings. Working capital trends highlight operational liquidity needs and potential cash drags. One-time items, such as litigation settlements or asset sales, are excluded to reveal the underlying earning power. These dimensions collectively inform whether the company’s earnings are sustainable and repeatable for future periods.

    Infographic with five columns representing core areas of a quality of earnings analysis: Revenue Quality, Expense Normalization, EBITDA Adjustments, Working Capital Trends, and One-Time Items, each with icons and bullet lists on a muted blue and gray palette.

    Zaidwood Capital’s Quality of Earnings analysis framework visualized in five key areas.

    By producing a normalized earnings base, the QoE report helps both buyers and sellers reach consensus on valuation. For buy-side M&A professionals, this analysis highlights the true recurring profitability of a target, removing distortions that could inflate or deflate the purchase price. Sellers also benefit, as a well-documented QoE report can justify a premium and accelerate negotiation.

    As part of our Full-Cycle M&A and capital advisory services, we integrate QoE analysis into every engagement to provide clients with clear, defensible financial insights. The report is not an audit; it does not verify financial statement accuracy in compliance with accounting standards. Instead, it offers transaction-specific intelligence that traditional audits often miss. Zaidwood Capital utilizes QoE reports as a core component of its full-cycle due diligence, ensuring that both buy-side and sell-side mandates are grounded in reliable earnings data. By identifying true economic earnings, a QoE report streamlines negotiations and reduces the risk of post-close surprises.

    Next, we examine the core components that define a comprehensive QoE analysis.

    Securities are offered through Finalis Securities LLC, an independent entity from Zaidwood Capital. This content is for informational purposes and does not constitute investment advice.

    Core Components of a Quality of Earnings Analysis

    A quality of earnings report for mid-market deals goes beyond audited financials to uncover the true recurring cash flow a buyer can rely on. In this section, we break down the three pillars of a quality of earnings analysis: normalization adjustments, working capital scrutiny, and EBITDA sustainability. Drawing on Zaidwood Capital’s due diligence expertise, we show how each component strengthens deal-making for institutional and private investors.

    Normalization Adjustments and Add-Backs

    Normalization adjustments strip away non-operational or inflated expenses to present a clean EBITDA. These adjustments are critical because audited financials may include non-recurring gains or expenses that distort the company’s sustainable earning power. In our analyses, we identify above-market owner compensation, one-time legal fees, personal expenses run through the business, and related-party transactions at non-market terms.

    • Owner’s Compensation Adjustment: Aligning above-market owner salary and benefits to industry-standard compensation for a replacement manager
    • Non-Recurring Expenses: One-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition
    • Personal Expenses: Personal travel, entertainment, vehicles, or family members on payroll not related to business operations
    • Related-Party Transactions: Above-market rent, management fees, or service charges paid to entities owned by the seller or their family

    We substantiate each adjustment with corroborating evidence—payroll records, lease agreements, invoices—and provide a clear rationale in our reports. A quality of earnings analysis also flags off-balance-sheet liabilities like operating leases or contingent obligations that can alter deal value. For example, an owner drawing $600,000 when market rate is $200,000 inflates expenses by $400,000, a typical adjustment we see. By documenting every add-back, we give buyers confidence in the normalized earnings figure. Additionally, QoE reports look beyond the balance sheet to identify contingent payments or environmental indemnities that may not be booked but represent real future cash outflows.

    Working Capital Analysis and Debt-Like Items

    Working capital analysis determines the normalized net operating capital needed post-acquisition. We assess seasonal needs, payment cycles, and industry norms, then compare that to the target company’s actual levels. The gap—whether surplus or deficit—becomes an adjustment to the purchase price. For instance, if a business has excess working capital relative to its normalized requirement, the buyer may credit the seller for that amount at closing; conversely, a deficiency reduces the price. Our QoE reports present these adjustments with supporting schedules so that both buyers and sellers can negotiate from a common understanding.

    Debt-like items are obligations that function as debt but are not on the balance sheet as such. Examples include deferred revenue, underfunded pensions, or installment sale obligations. We identify these, quantify their impact, and deduct them from the equity value, just as we would formal debt. This analysis prevents the buyer from inheriting hidden financial burdens and ensures the enterprise value accurately reflects the business’s true financial position.

    EBITDA Quality and Sustainability Assessment

    EBITDA sustainability evaluation dissects the recurring nature of earnings. We examine revenue concentration risk—if a company depends on a single customer for more than 10% of revenue, that concentration creates vulnerability. Customer retention trends, contract renewal probabilities, and churn rates indicate how sticky the revenue base is. We also assess margin stability, checking whether gross and operating margins are sustainable or eroded by pricing pressure. In emerging markets M&A, we place extra focus on revenue concentration and retention because currency swings, regulatory shifts, and political instability can quickly reshape earnings. We evaluate supplier relationships to ensure margins are not artificially supported by short-term concessions, and we consider macroeconomic trends that could influence future earnings. Through our QoE reports, we help buyers distinguish durable cash flows from those that could evaporate post-acquisition, providing a forward-looking perspective essential for informed investment decisions.

    Selecting a Quality of Earnings Provider for Your Mid-Market Deal

    A quality of earnings report for mid-market deals is one of the most important tools for de-risking an acquisition, and choosing the right provider directly influences the credibility of your financial analysis. For companies in the $20M–$100M revenue range, the provider’s expertise, speed, and post-engagement support can make a material difference in how the QoE findings are received by lenders, underwriters, and counterparties.

    Evaluating Boutique Firm Expertise for QoE Analysis

    Boutique firms such as Zaidwood Capital specialize in delivering a highly tailored Quality of Earnings analysis that aligns with the specific dynamics of mid-market transactions. Their teams typically bring deep industry knowledge and direct senior partner involvement, ensuring that the engagement is led by an experienced professional who understands both the financial and strategic dimensions of the deal. In contrast, Big Four accounting firms offer a broad, generalist approach with standardized QoE templates that can miss the nuances of niche sectors. Mid-tier regional firms occupy a middle ground, providing moderate specialization but often with less senior oversight than a dedicated boutique.

    The critical differentiator is the level of partner engagement. At a boutique, the senior team leads the QoE analysis from start to finish, which shortens feedback loops and results in a more focused report. Big Four firms typically rely on junior staff for the bulk of the fieldwork, with partner review at the conclusion, while mid-tier firms show variability in senior involvement. This direct access to senior talent often translates into faster turnaround times and more actionable insights for the acquirer.

    The following comparison table summarizes key distinctions to inform your selection.

    Common Add-Backs and Adjustments in Quality of Earnings Reports
    Adjustment TypeDescriptionTypical EBITDA ImpactCommon Example
    Owner’s Compensation AdjustmentAligning above-market owner salary and benefits to industry-standard compensation for a replacement manager+$150,000 to $500,000 add-backOwner paying themselves $600,000 when market rate for a general manager is $200,000
    Non-Recurring ExpensesOne-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition+$50,000 to $300,000 add-back$200,000 in legal fees from a one-time litigation matter
    Personal ExpensesPersonal travel, entertainment, vehicles, or family members on payroll not related to business operations+$25,000 to $150,000 add-backCompany-leased luxury vehicle used primarily for personal use
    Related-Party TransactionsAbove-market rent, management fees, or service charges paid to entities owned by the seller or their family+$75,000 to $400,000 add-backPaying $30,000/month rent to a seller-owned LLC when market rate is $15,000

    Boutique firms consistently deliver deep specialization and hands-on partner involvement, often completing a QoE engagement in as little as 2–4 weeks—roughly half the time of a Big Four engagement. Moreover, firms like Zaidwood Capital adhere to established capital markets best practices, incorporating frameworks from ICMA capital markets to ensure the analysis meets rigorous industry standards. This commitment to both speed and quality makes boutique advisors a compelling choice for mid-market acquirers.

    Scope and Cost Expectations for Mid-Market Companies

    For a $20M–$100M-revenue company, the scope of a Quality of Earnings engagement should be calibrated to deal complexity and the acquirer’s specific concerns. A one-size-fits-all report rarely adds value; instead, the engagement scope must be defined collaboratively, focusing on revenue recognition policies, working capital trends, customer concentration risks, and any carve-out adjustments that could affect normalized EBITDA. At Zaidwood Capital, we work directly with buyers to design a custom scope that addresses the unique drivers of the target business, avoiding unnecessary line items that inflate cost without improving decision-making.

    Cost expectations reflect the level of customization. Boutique firms like Zaidwood Capital typically quote $25,000–$50,000 for a $20M-revenue company, while Big Four firms can range from $75,000 to over $150,000 for a similar-sized engagement. Mid-tier regional firms generally fall between $40,000 and $80,000. All figures are custom quotes and depend on data availability, the number of entities involved, and the speed required. We emphasize that our pricing is never a fixed fee; each engagement is priced based on the precise scope and timeline agreed upon, with full-cycle support extending from the initial QoE analysis through deal close.

    Integrating QoE Findings into Deal Structuring

    A Quality of Earnings report is not just a diligence artifact—it directly shapes the final deal terms. When normalized EBITDA adjustments reveal that reported earnings overstate true recurring cash flow, buyers can negotiate purchase price reductions or post-closing true-ups. Earnout structures become more defensible when the QoE identifies revenue volatility or concentration risks that warrant contingent payments. Similarly, representation and warranty insurance underwriters increasingly rely on QoE findings to set coverage limits and exclusions, making a thorough report a valuable risk-transfer tool.

    At Zaidwood Capital, our full-cycle advisory model ensures that QoE insights flow seamlessly into the negotiation and documentation phases. We translate EBITDA adjustments into specific purchase price adjustment mechanisms, design earnout milestones linked to verifiable financial metrics, and help acquirers present the QoE to insurers to secure favorable underwriting terms. This integrated approach reduces re-trading risk and accelerates the path to a signed purchase agreement. Once you have selected the right partner, the next step is implementing a disciplined QoE process that turns financial analysis into concrete deal terms. As with any investment, past performance does not guarantee future results, and we recommend consulting professional advisors to tailor the approach to your deal.

    How Quality of Earnings Reports Influence Purchase Price and Deal Terms

    A quality of earnings report for mid-market deals does more than flag accounting irregularities; it serves as the core negotiating lever for adjusting the purchase price and crafting protective deal provisions. At Zaidwood Capital, we treat the QoE report as the definitive source for reconciling reported financials with normalized economic reality. This alignment is essential before we engage in price discussions.

    In our experience, the most direct impact of the QoE report is a purchase price adjustment derived from normalized EBITDA. When the report strips out non-recurring revenue or one-time expenses, it recalibrates the basis on which the acquisition multiple is applied. A lower sustainable EBITDA can reduce the implied valuation, prompting the buyer to seek a price reduction. Conversely, a seller whose earnings prove clean and recurring can leverage the report to sustain or elevate the offer. Beyond EBITDA, the working capital peg—determined by historical QoE trend analysis—can shift the final cash consideration. If the report reveals that the target’s normalized net working capital is lower than originally represented, the buyer rightfully demands a dollar-for-dollar reduction at closing. Sellers with positive QoE results often use this as a shield against overly burdensome indemnification clauses, while buyers rely on the analysis to insert additional covenants or expand representations and warranties when risks are evident.

    Earnout structures are another area where QoE findings carry substantial weight. We typically link earnout payments to forward-looking financial metrics that have been validated by the quality of earnings (QoE) review. This ensures that post-closing milestones are both achievable and reflective of the business’s true earning power, reducing disputes later. Likewise, indemnification horizons and escrow amounts are calibrated to the specific risks flagged in the report. A revenue recognition issue might extend the survival period for related claims and increase the escrow holdback, while a clean report shortens those protections. Underpinning this rigor are regulatory standards that shape our financial analysis. FINRA securities regulation, administered by the Financial Industry Regulatory Authority, sets expectations for broker-dealer reporting that influence how we assess earnings quality in private transactions. Similarly, SEC securities regulation, enforced by the U.S. Securities and Exchange Commission, mandates GAAP compliance and reinforces the importance of accurate data in all valuations. In the following section, we demonstrate how these adjustments play out in a real mid-market transaction.

    Common Questions About Quality of Earnings Reports in Mid-Market Deals

    After establishing the importance of a quality of earnings report for mid-market deals, we address the most common questions buyers and sellers ask before engaging a QoE provider.

    What is a quality of earnings report, and why is it essential for mid-market deals? A QoE analysis examines earnings sustainability and quality, revealing adjustments needed in private-company financials and uncovering risks like customer concentration.

    How does a QoE differ from standard due diligence, and what adjustments does it uncover? Unlike standard due diligence, a QoE report serves as a complementary tool—used by advisors like Zaidwood Capital—to examine normalized EBITDA, margin trends, and working capital, separating recurring from one-time items and revenue mix.

    How does a QoE report impact valuation and deal structure? By surfacing these insights, a QoE can bridge valuation gaps and influence purchase price multiples, giving both sides clearer grounds for negotiation.

    Next, we’ll walk through the practical steps of commissioning a QoE report for your mid-market transaction.

    Leveraging Quality of Earnings Reports for Smarter M&A Decisions

    A Quality of Earnings report for mid-market deals dissects financials to expose sustainable earnings by stripping out one-offs. It flags risks like premature revenue booking, strengthening your negotiation position. Mid-market firms with less polished reporting especially benefit. At Zaidwood Capital, a quality of earnings report for mid-market deals anchors our full-cycle due diligence, alongside operational, commercial, and IT assessments, to deliver a complete picture. Compliance with SEC securities regulation ensures data reliability, and leveraging QoE minimizes post-close shocks. Deeper insight drives smarter M&A decisions.

    Resources

  • Top Buy-Side M&A Strategies for 2026: Expert Insights

    Top Buy-Side M&A Strategies for 2026: Expert Insights

    Table of Contents

    In the dynamic world of buy-side M&A, acquirers face intense challenges in sourcing viable targets amid market volatility and competitive pressures. This acquirer-focused approach empowers strategic expansion through precise target acquisition planning, contrasting sell-side processes where sellers prioritize valuation maximization and buyer outreach. While sell-side deals often span 6-9 months with broad auctions, buy-side emphasizes targeted diligence to mitigate risks.

    At Zaidwood Capital, we provide expert mergers and acquisitions advisory tailored for buy-side acquisition strategy, guiding clients from opportunity identification through due diligence, valuation, negotiation, and integration. With over 300 completed deals and $24.4B in transaction volume, our team leverages a network of 4,000+ investors to access $15B+ in deployable capital, ensuring full-cycle support for informed decisions.

    Discover the six key benefits of partnering with our boutique firm, starting with superior target sourcing that lays the foundation for successful buy-side due diligence and execution.

    1. Precise Target Identification

    In buy-side M&A, identifying the right acquisition targets amid vast opportunities poses significant challenges for growth-focused firms. Without precise sourcing, companies risk prolonged searches and missed synergies, complicating expansion strategies.

    Our approach streamlines this through rigorous criteria including market fit, financial health, and synergy potential, ensuring targets align with your buy-side acquisition strategy. We leverage the proprietary Deal Vault for access to vetted opportunities and conduct sector mapping with preliminary screening to accelerate discovery. As highlighted in resources on selecting M&A advisor, effective advisors embody competence, compassion, and integrity to guide strategic target hunting. Our extensive network of over 4,000 investors and $15B in deployable capital further enhances acquisition opportunity scouting, drawing from more than 300 completed transactions for proven results.

    For instance, we recently matched a mid-market client with a complementary asset in under three months via network introductions, enabling swift evaluation and integration planning before advancing to due diligence.

    2. Thorough Due Diligence Execution

    In the realm of buy-side due diligence, thorough validation is essential to uncover hidden risks and maximize acquisition value. At Zaidwood Capital, we execute comprehensive reviews that integrate financial, legal, operational, commercial, IT, and human capital assessments, drawing on our 300+ completed deals to support clients in navigating complex transactions.

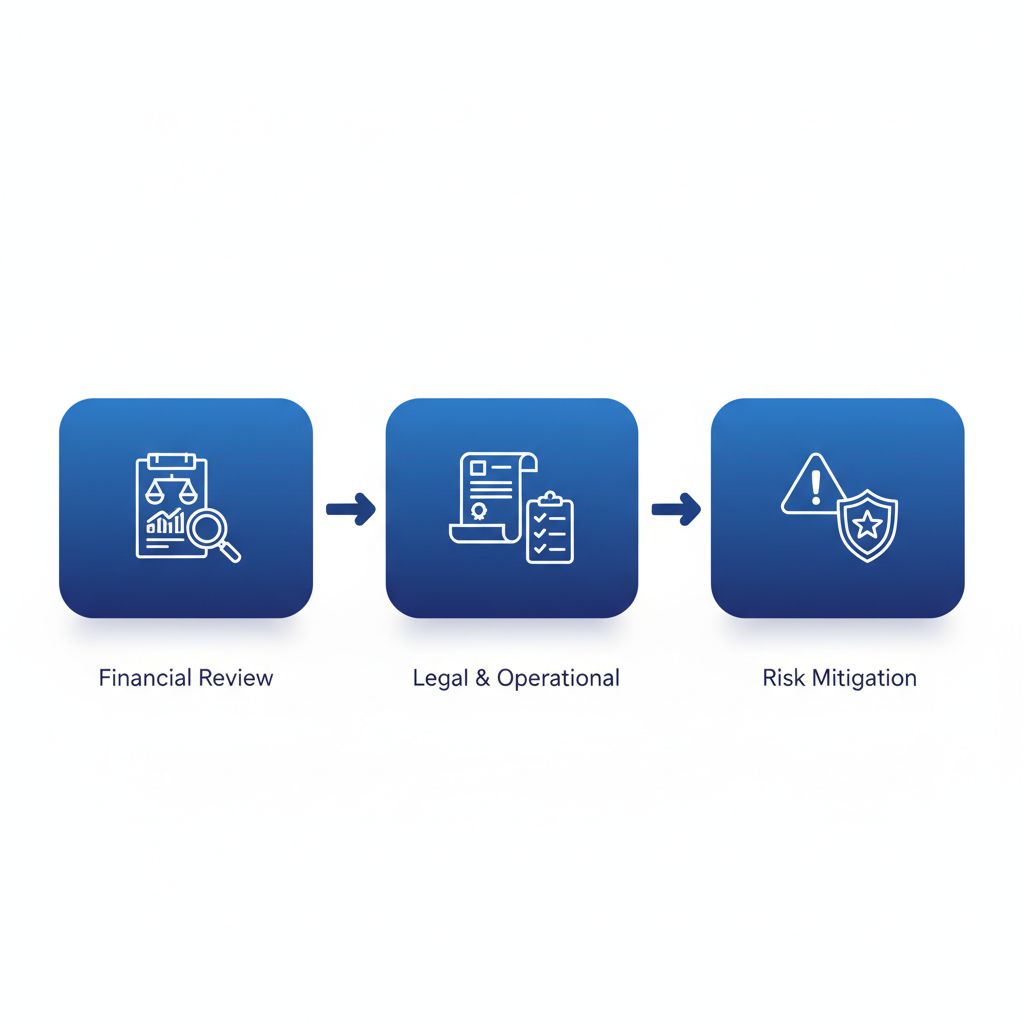
    Horizontal process flow diagram showing three stages of buy-side due diligence in mergers and acquisitions: financial review, legal and operational assessment, and risk mitigation.

    Key phases of thorough due diligence execution in M&A buy-side process

    Our process begins with secure data room access, allowing detailed examination of target financials and operations. We then conduct third-party verifications and multi-faceted risk assessments, incorporating antitrust considerations from established guidelines to ensure compliance. As a leading boutique M&A advisory firm, we streamline buy-side M&A by providing integrated diligence, including checklists for red flags like discrepancies in revenue reporting or unresolved litigation.

    • Verify financial statements against independent audits.
    • Assess legal contracts for potential liabilities.
    • Evaluate operational efficiencies and IT security.

    A key tip from our engagements: Always probe management representations early to detect inconsistencies that could derail deals, fostering informed buy-side acquisition strategies before advancing to valuation.

    This rigorous approach transitions seamlessly into precise target valuation, the next critical layer in our acquisition vetting protocols.

    3. Strategic Valuation Insights

    In buy-side M&A, overlooking valuation pitfalls can lead to overpaying for targets or missing synergy opportunities, undermining deal success. Our team at Zaidwood Capital leverages advanced techniques and capital advisory services to ensure precise deal pricing analysis, drawing from $24.4 billion in aggregate transaction volume for informed acquisition worth assessment.

    We apply discounted cash flow (DCF) modeling to project future cash flows, comparable company analysis for market benchmarks using our network of over 4,000 investors, and precedent transactions to gauge historical premiums. In buy-side acquisition strategy, we quantify synergies through detailed revenue and cost projections, integrating pro forma financials to model post-merger performance. This data-driven approach supports negotiations by establishing defensible value ranges that optimize capital deployment.

    A key tip for synergy modeling: Focus on realistic cost savings from operational overlaps, validated by our market intelligence, to avoid inflated expectations that erode value during integration.

    4. Effective Negotiation Support

    In buy-side M&A transactions, negotiation risks abound, including overpaying due to incomplete information or overlooking hidden liabilities that erode value post-closing. These challenges can derail even the most promising deals without expert intervention. At Zaidwood Capital, we mitigate these risks by leveraging insights from buy-side due diligence to inform strategic positioning.

    We provide seasoned guidance from our leadership team, drawing on industry-standard practices to navigate term sheets, letters of intent (LOIs), and closing conditions. Key negotiation levers include price adjustments tied to working capital contingencies and structured earn-outs that align seller incentives with performance milestones. We emphasize robust representations and warranties to protect against undisclosed issues, while our expertise in strategic documentation ensures precise deal term bargaining. This approach secures favorable outcomes and seamlessly transitions to post-merger integration planning. Our investment bank advisory experience highlights the importance of senior professionals in volatile transaction environments, where retaining expertise drives successful acquisition closing tactics.

    A practical tip for buy-side M&A: When drafting an LOI, insist on broad exclusivity periods with clear milestones to prevent seller distractions, allowing time to refine your acquisition strategy based on diligence findings.

    5. Seamless Integration Planning

    Following the successful negotiation of a buy-side M&A deal, the integration phase presents significant challenges, including aligning operations and capturing merger synergy realization. At Zaidwood Capital, we guide clients through this critical transition to ensure value creation without disruptions.

    Our integration roadmap begins with comprehensive target onboarding frameworks, focusing on team onboarding and seamless system mergers. We advise on operational alignment to streamline processes and enhance efficiency. For financing, our debt advisory expertise supports post-deal restructuring, optimizing capital structures to reduce costs and improve liquidity. Additionally, our equity advisory services facilitate liquidity solutions, enabling stakeholders to realize gains strategically. These steps form a structured buy-side acquisition strategy that maximizes post-acquisition value.

    A key best practice involves prioritizing cultural fit during integration. We recommend early engagement with leadership teams to foster collaboration, mitigating resistance and building a unified vision. This approach not only accelerates synergy realization but also lays the foundation for long-term success in the evolving M&A landscape.

    6. Robust Risk Management

    In buy-side M&A transactions, potential pitfalls like regulatory hurdles and financial discrepancies often threaten value creation. We at Zaidwood Capital, one of the buy-side M&A firms, recognize these challenges and integrate proactive risk management into every stage of the process, ensuring clients achieve sustainable outcomes through informed decision-making.

    Our approach begins with thorough buy-side due diligence to uncover hidden liabilities early, followed by strategic consulting that assesses and addresses acquisition hazard controls. We deliver fairness opinions for objective valuation insights, while our capital introductions connect clients to a diverse network of over 4,000 investors, mitigating funding dependencies. Leveraging the Zaidwood Deal Vault, we provide access to risk-vetted opportunities, strengthening overall deal risk frameworks and supporting resilient buy-side acquisition strategies. This ongoing advisory minimizes disruptions and maximizes transaction success.

    For effective contingency planning, develop multiple scenarios with backup financing and regulatory compliance checklists. This preparation allows quick pivots, safeguarding investments in dynamic markets.

    Partnering for Acquisition Excellence

    In summary, our buy-side M&A advisory services at Zaidwood Capital deliver six core benefits that drive process efficiency, value optimization, and strategic alignment. From expert target sourcing and comprehensive buy-side due diligence to robust risk management, we empower your buy-side acquisition strategy with proven acquirer success pathways. Our track record includes over 300 completed deals, aggregating $24.4 billion in transaction volume, and access to a network of more than 4,000 institutional investors.

    When selecting an M&A advisor, prioritize firms with deep industry expertise, extensive investor connections, and full-cycle capabilities like ours. Evaluate based on alignment with your commercial goals, demonstrated results, and tailored support for seamless execution.

    Ready to elevate your acquisitions? Contact us at Zaidwood Capital today for a confidential consultation and personalized guidance on your next strategic move.

    Resources