Zaidwood Capital

Category: Capital Advisory

  • Tech Mergers and Acquisitions: Complete Guide for 2026

    Tech Mergers and Acquisitions: Complete Guide for 2026

    Table of Contents

    The Landscape of Tech Mergers and Acquisitions

    Tech mergers and acquisitions are accelerating at a historic pace, propelled by the convergence of artificial intelligence and cybersecurity disruption. We observe that ai-driven m&a dominates mid-market dealmaking as companies race to integrate generative AI, while cybersecurity acquisitions surge in response to intensifying threat landscapes and new regulatory frameworks. This velocity creates immense opportunity but also unparalleled complexity for investors and business owners alike.

    In this fast-moving environment, traditional advisory models often struggle to keep up. As a boutique investment banking firm, we combine decades of collective investment banking experience with proprietary data and a global network of over 4,000 investors. Our Sovereign Data Nexus and Precision Catalyst platforms accelerate due diligence and investor matching, delivering the speed and precision that today’s tech transactions demand. This evolving landscape requires a strategic advisor with both agility and institutional knowledge—qualities we bring to every engagement, from initial strategy through final close.

    Key Milestones in the Tech M&A Process

    Navigating the tech mergers and acquisitions landscape requires a structured, milestone-driven framework to manage complexity and unlock value. At Zaidwood Capital, we believe that before you can appreciate the nuances of each stage, you should understand what is an investment bank and how a dedicated advisory team serves as a strategic partner throughout the process. The following milestones outline our systematic approach.

    • Strategic Assessment & Target Identification
      We start by clarifying your growth objectives and screening potential targets that align with your strategic vision. Our team leverages proprietary data networks to identify opportunities that might otherwise go unnoticed.
    • Valuation & Financial Modeling
      Using advanced financial modeling, we triangulate a company’s intrinsic value and quantify potential synergies. This phase ensures you have a realistic pricing framework before entering negotiations.
    • Due Diligence (Including Cybersecurity & IP Audits)
      A rigorous evaluation of financial statements, operational metrics, and legal risks is conducted, with special attention to technology assets, cybersecurity posture, and data privacy compliance. In AI-driven M&A and cybersecurity acquisitions, our proprietary data access via the Sovereign Data Nexus allows for deeper analysis of intellectual property portfolios and cyber risk exposure.
    • Negotiation & Letter of Intent
      Investment bankers facilitate valuation discussions, presenting industry benchmarks and helping bridge gaps through creative deal structuring—such as earn-outs or seller financing. A non-binding letter of intent is then drafted to formalize key terms.
    • Regulatory Approvals & Compliance
      Navigating antitrust, data sovereignty, and sector-specific regulations is critical. We coordinate with legal counsel to ensure all filings are complete and timelines are managed proactively.
    • Closing & Deal Documentation
      Our Full-Cycle M&A approach encompasses deal vault management and the preparation of definitive agreements. We oversee the final exchange of consideration and transfer of ownership, ensuring every detail is documented and compliant.
    • Post-Merger Integration
      Success doesn’t end at closing; we help clients execute integration plans that capture synergies, align cultures, and safeguard critical technology architectures. Continuous monitoring of cybersecurity risks remains a priority.

    With a clear understanding of these milestones, it becomes evident why experienced advisory guidance is critical. Our role as a Boutique M&A and Capital Advisory Firm is to streamline each step, mitigating risk and positioning clients for long-term value creation. In the following sections, we’ll explore each milestone in greater depth to help you prepare for a successful transaction.

    In tech mergers and acquisitions, regulatory complexity often determines whether a transaction reaches completion or stalls indefinitely. Beyond financial and technical due diligence, regulatory compliance emerges as a critical hurdle. Our firm combines deep advisory experience with proprietary intelligence tools to help clients anticipate and address these challenges.

    For transactions involving telecommunications infrastructure, the review process demands particularly careful navigation. The FCC telecommunications agency must approve any transfer of spectrum licenses or communications assets, a process our team streamlines through early engagement and thorough preparation. According to the Federal Communications Commission, public interest hearings and foreign ownership rules frequently extend review timelines, especially in tech mergers and acquisitions where national security considerations intersect with infrastructure control. We help clients prepare comprehensive filings that address these nuanced requirements from the outset.

    Cross-border financing structures introduce additional regulatory dimensions that many acquirers underestimate. The International Capital Market Association establishes the Green Bond Principles, a critical framework when technology acquirers issue sustainable debt to fund acquisitions. For technology M&A transactions spanning multiple jurisdictions, ICMA standards provide essential guidance on disclosure requirements and market practices that protect both issuers and investors. In ai-driven M&A, regulatory scrutiny of data privacy compliance often intersects with these capital market requirements, creating layered obligations that demand coordinated advisory support.

    Cybersecurity acquisitions frequently trigger filings under the Committee on Foreign Investment in the United States, adding national security review to already complex transaction timelines. Our Sovereign Data Nexus platform monitors real-time regulatory changes and precedent decisions across these agencies, helping clients anticipate potential friction points. While advisory experience reduces execution risk, each transaction remains unique, and regulatory outcomes depend on the specific deal structure and government determinations. We provide clarity without promising specific results.

    Once regulatory approvals are secured, the focus shifts to rapid, compliant integration. Our Velocity Matrix accelerates this transition, enabling clients to move from approval to operational execution without sacrificing regulatory diligence or transaction momentum.

    Preparing Your Company for Due Diligence

    Once you have identified a potential acquisition target, thorough preparation is the next critical step, particularly in the dynamic landscape of tech mergers and acquisitions. For founders and management teams, the due diligence process can feel overwhelming, but a structured, proactive approach transforms it from a hurdle into an opportunity to showcase your company’s value. At Zaidwood Capital, we guide our clients through this critical phase, ensuring that every facet of the business is scrutinized and presented to withstand the most rigorous investor or buyer examination. The goal is not just to survive diligence but to leverage it as a strategic step toward a successful transaction.

    We advise our clients to focus on three fundamental preparatory tasks. First, compile and organize all foundational documentation. This includes audited financial statements, corporate tax returns, capitalization tables, material contracts, and all historical investor presentations and board decks. Second, assemble a dedicated, cross-functional internal response team. This group should include key leaders from finance, legal, and operations who are empowered to answer questions and pull records quickly. Third, establish a secure, meticulously indexed virtual data room. A well-structured data room accelerates the review process and signals operational maturity to potential partners.

    For companies involved in ai-driven m&a or cybersecurity acquisitions, the diligence requirements extend far beyond standard financial and legal review. A significant portion of the evaluation will focus on technology and intellectual property. Be prepared to demonstrate clear ownership and defensibility of your core IP, including patents, trademarks, and proprietary code. We help our clients prepare detailed documentation of AI model training data, algorithm logic, and bias mitigation protocols. Equally non-negotiable is a thorough review of your cybersecurity infrastructure, incident response history, and data privacy compliance. Addressing these technology-specific areas proactively is a powerful risk-mitigation strategy that prevents deal-derailing surprises.

    As your Boutique M&A and Capital Advisory Firm, we streamline this entire preparation phase. We provide a tailored readiness checklist and can manage the deal vault, ensuring all sensitive information remains secure and organized. This hands-on support allows you to stay focused on running your business. A robust financial analysis is the bedrock of this process, and professionals with a strong foundation, including those who have completed a CFA certification program, add significant rigor to the financial modeling and valuation perspectives that underpin a solid diligence review.

    With your company thoroughly prepared, the formal due diligence process can proceed more efficiently, often beginning with the opening of a secure data room to invited parties.

    Evaluating the Cost and Value of M&A Advisory

    In today’s dynamic deal environment, tech mergers and acquisitions require rigorous evaluation of advisory cost and value. As a Boutique M&A and Capital Advisory Firm, we believe clients must look beyond headline fees to assess the full spectrum of value an advisor delivers throughout the transaction lifecycle.

    Understanding Fee Structures

    M&A advisory fees generally follow two primary models. A retainer fee compensates the advisor for upfront work, including market analysis, buyer identification, and initial due diligence preparation. This structure ensures dedicated resources are committed to the engagement from day one, aligning incentives for thorough preparation rather than rushed execution. The second model, a success fee, is contingent upon closing and typically calculated as a percentage of transaction value. This arrangement directly ties advisor compensation to outcomes, creating strong alignment around achieving optimal deal terms. Many engagements combine both structures, balancing ongoing commitment with performance-based rewards.

    Value Drivers and Differentiating Factors

    Evaluating advisory value requires examining factors beyond the fee schedule. Proprietary data access represents a critical differentiator. Through our Sovereign Data Nexus, we leverage private servers and exclusive market intelligence to identify opportunities and benchmark valuations that public databases cannot replicate. This infrastructure powers informed decision-making, particularly in specialized sectors like ai-driven m&a and cybersecurity acquisitions, where traditional valuation metrics often fall short. Execution speed, driven by our Velocity Matrix methodology, compresses timelines without sacrificing diligence quality. Finally, investor engagement capabilities, enhanced by our Precision Catalyst platform, ensure targeted outreach to qualified counterparties rather than broad, unfocused marketing.

    Boutique advisory firms offer distinct advantages over bulge-bracket institutions, including senior-level attention throughout the engagement, specialized sector expertise, and flexible fee arrangements. While larger banks provide global distribution networks and multi-product capabilities, boutique firms deliver personalized service and dedicated focus on middle-market transactions where nuanced industry knowledge creates measurable value.

    For industry standards and best practices, clients may refer to organizations such as the ICMA capital market association and the CFA Institute, whose ethical frameworks and professional guidelines establish benchmarks for advisory conduct.

    Criteria for Evaluating Advisory Value

    • Transaction track record in relevant sectors and deal sizes
    • Network quality, measured by access to decision-makers at strategic acquirers and institutional investors
    • Technological capabilities that enhance data security, valuation accuracy, and investor targeting
    • Professional standards, including adherence to CFA Institute ethical guidelines and demonstrated commitment to fiduciary responsibility

    With these evaluation criteria in mind, one can better navigate the selection process for an advisory partner aligned with specific transaction objectives.

    The landscape of tech mergers and acquisitions is being reshaped by two powerful forces: the application of artificial intelligence and a surge in cybersecurity-focused dealmaking. As a Boutique M&A and Capital Advisory Firm, Zaidwood Capital sees these trends creating both opportunity and complexity for growth companies and investors. To understand these shifts, it is helpful to revisit what is an investment bank and how its core advisory services are being transformed by technology. The traditional functions of capital raising and full-cycle M&A are now augmented by proprietary data, AI-driven analytics, and rapid execution capabilities that distinguish boutique platforms from larger wirehouses.
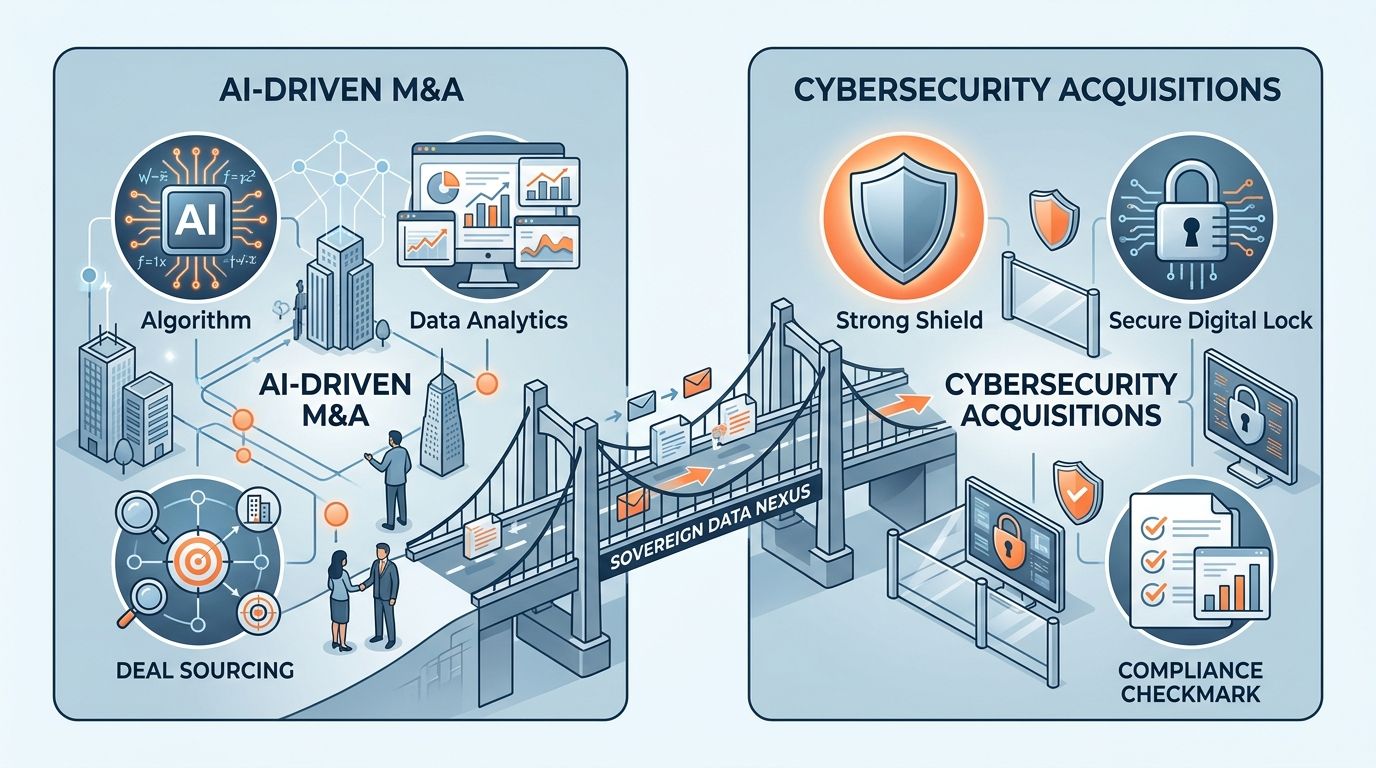
    Infographic showing AI-driven M&A on left and cybersecurity acquisitions on right connected by Sovereign Data Nexus bridge
    AI and cybersecurity acquisition trends infographic

    Now, AI-powered M&A is transforming every stage of the deal lifecycle. Our Sovereign Data Nexus employs machine learning to scan thousands of targets, flagging financial and operational red flags and surfacing data-driven opportunities that traditional manual screening would miss. Predictive valuation models, built on historical transaction data and real-time market signals drawn from our global investor network, help our team price transactions with greater precision. This is not just a pre-deal advantage; AI tools are increasingly used in post-merger integration to identify synergy realizations and operational efficiencies that protect deal value. For clients, staying ahead of trends in ai-driven m&a requires access to proprietary data and tech-enabled diligence, which translates into faster, more informed decision-making—a distinct edge in competitive processes.

    Cybersecurity acquisitions have become a dominant theme in the current cycle. Companies are acquiring specialized security firms to defend against evolving threats, comply with tightening regulations, and build competitive moats around their digital assets. With over $24.4 billion in aggregate transaction volume handled by our team, we have witnessed a sharp increase in deals targeting cybersecurity providers. The growth in cybersecurity acquisitions reflects a strategic imperative to embed security as a driver of resilience. Our Velocity Matrix enables rapid execution, and our network of 4,000+ investors actively seeks cyber-focused deals. This approach allows clients to capitalize on market opportunities before conditions change.

    Understanding these emerging trends—and how a boutique platform like Zaidwood Capital leverages the Sovereign Data Nexus and Velocity Matrix—is essential for any stakeholder considering a technology-driven transaction. In our next section, we explore how we structure and execute full-cycle deals that capitalize on these dynamics.

    Achieving Success in Tech Mergers and Acquisitions

    Success in tech mergers and acquisitions hinges on speed, proprietary data, and rigorous due diligence. In a landscape where cybersecurity acquisitions can turn on undiscovered vulnerabilities, and ai-driven M&A requires deep technical evaluation, traditional advisory is no longer enough.

    We address this through our proprietary deal infrastructure. Our Sovereign Data Nexus provides secure, transaction-specific servers and exclusive data sets, enabling the granular risk assessment technology deals demand. The Velocity Matrix then compresses execution timelines without sacrificing quality, a critical advantage in fiercely competitive tech auctions. Underpinning both is the Precision Catalyst, our integrated investor-engagement engine that uses digital marketing and capital-markets expertise to align startups, growth companies, and institutional capital at the right moment.

    We deliver this as Full-Cycle M&A: end-to-end support from strategic documentation through to a closed transaction. While these capabilities sharpen execution, every deal involves inherent risk and requires careful regulatory and legal compliance. These tools form the foundation of our advisory process, explored in the next section.
    Resources

  • Tree Care Industry Trends 2026: What You Must Know

    Tree Care Industry Trends 2026: What You Must Know

    Table of Contents

    As we examine tree care industry trends 2026, it’s clear that technology and capital are driving a fundamental transformation. The adoption of AI-powered tree risk assessment technology allows arborists and municipalities to make data-driven decisions, improving safety and operational efficiency across urban canopies.

    At the same time, climate-resilient urban canopy management is moving from a niche concern to a mainstream priority. As extreme weather events intensify, cities are recognizing the critical role of trees in cooling, carbon sequestration, and stormwater management. In our view, the shift from reactive tree removal to proactive care enabled by technology and climate policy is a long-term structural change that will fuel demand for advanced services.

    Capital is following these structural tailwinds. We are observing growing M&A activity in the tree care sector, mirroring patterns identified in Zaidwood Capital’s overview of emerging markets M&A. Consolidation is enabling companies to scale and attract institutional investors seeking stable, infrastructure-linked returns. The influx of capital into tech-enabled tree care companies further signals market confidence in the sector’s growth.

    For investors, these converging trends create a favorable landscape for participating in the environmental infrastructure space. We believe that understanding these drivers can help position portfolios for the maturation of green infrastructure, though past performance does not guarantee future results. Ultimately, this article is for informational purposes and does not constitute an offer, solicitation, or investment advice.

    Understanding the Tree Care Industry’s Structural Shift

    The tree care industry trends 2026 point to a fundamental structural shift reshaping arboricultural services and their investment landscape. Three primary drivers are fueling this transformation:

    • Adoption of AI-powered tree risk assessment technology
    • Mandates for climate-resilient urban canopy management
    • Accelerating M&A consolidation across historically fragmented markets

    Technology is the first seismic force. Innovative firms are deploying AI-powered tree risk assessment technology to evaluate health, stability, and failure probability with precision never before possible. These platforms analyze multispectral imagery, weather patterns, and soil data to forecast liabilities at scale, capturing the attention of private equity and growth-focused investors.

    Climate imperatives are the second driver. Municipalities worldwide are mandating climate-resilient urban canopy management to combat heat islands and stormwater surges. The resulting fragmentation and unmet compliance demand create natural roll-up opportunities. Regional platforms that can consolidate services while meeting sustainability metrics are becoming prime targets for strategic acquirers and institutional funds seeking ESG-aligned exposure.

    Finally, M&A consolidation is accelerating across the tree care sector. Zaidwood Capital’s deep dive into emerging markets M&A reveals a 15 percent annual surge in transaction volumes across developing economies—a dynamic mirrored in North American specialty services. This structural momentum positions the tree care industry for increased emerging markets M&A activity, drawing interest from sovereign wealth funds and cross-border alliances.

    Technology and Climate Adaptation: Drones, AI, and Resilient Canopies

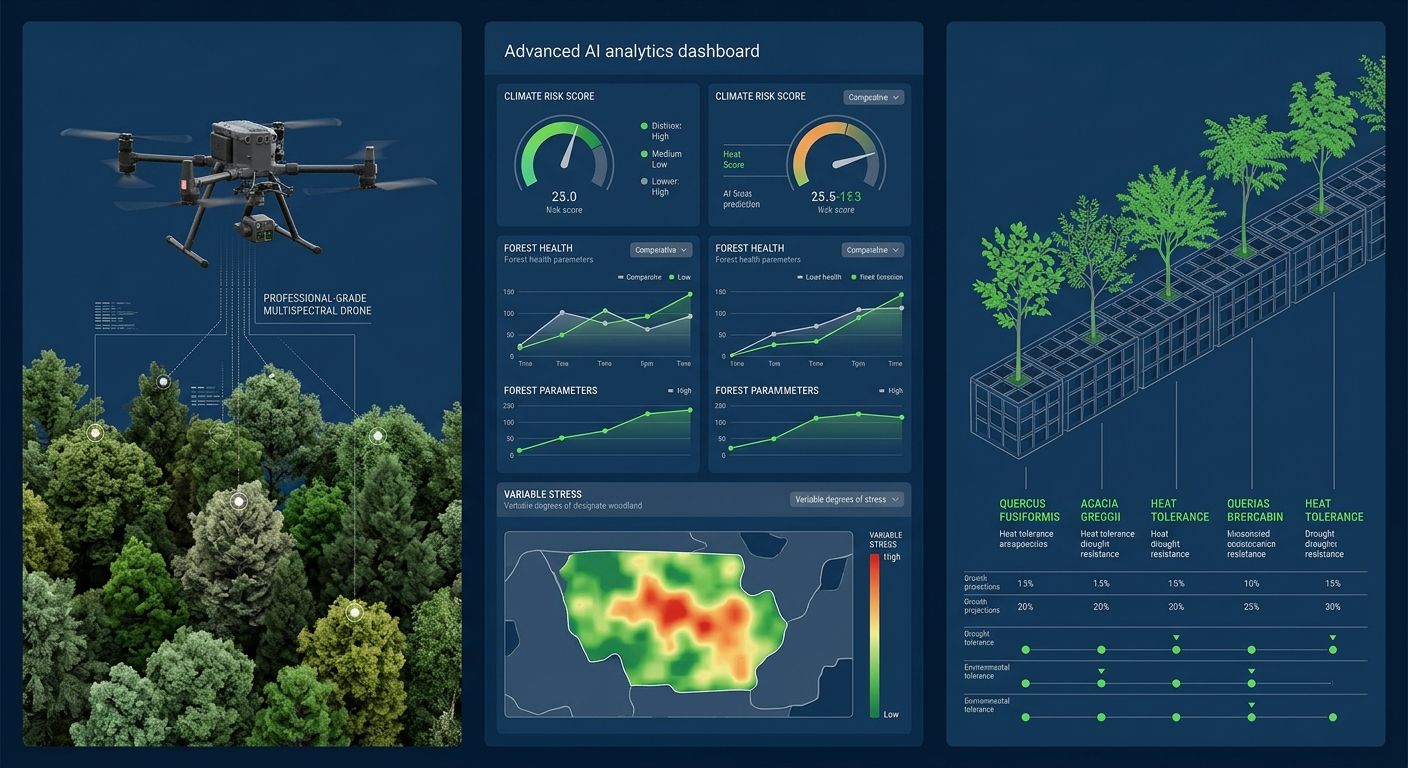
    Among the most impactful tree care industry trends 2026 are the rapid adoption of drone-based health assessments, AI-powered risk prediction, and climate-adaptive species selection.

    Horizontal infographic with three columns showing drone with multispectral camera over tree canopy, AI risk dashboard, and heat-tolerant tree species

    Technology and climate adaptation with drones, AI, and resilient canopies

    Drone-Based Arborist Health Assessments

    Drone-based arborist health assessments are revolutionizing the field. Equipped with multispectral and LiDAR sensors, drones capture high-resolution imagery and 3D data that reveal early signs of disease long before symptoms are visible to the naked eye. This approach improves safety and cuts inspection costs by up to 50% compared to traditional methods.

    AI-Powered Tree Risk Assessment Technology

    The next frontier in arboriculture is AI-powered tree risk assessment technology. By feeding data from IoT soil moisture probes and historical weather patterns into machine learning models, these systems can predict the probability of limb failure with remarkable accuracy. This allows arborists to schedule preventive maintenance proactively.

    Climate-Adaptive Tree Care Practices

    Professionals are rethinking species selection to create climate-resilient urban canopy management strategies. Heat- and drought-tolerant species gaining prominence include Quercus macrocarpa (Bur Oak), Ulmus ‘Morton Glossy’ (Triumph™ Elm), and Gleditsia triacanthos var. inermis (Thornless Honeylocust). These proactive steps ensure that urban forests continue to deliver ecosystem services as conditions shift.

    Residential Service Growth and the Labor Crisis: Practical Implications for 2026

    Outlook for Residential Tree Service Growth

    Three primary catalysts drive demand for residential tree services: home improvement activity, severe weather events, and accelerating urbanization. Homeowners are increasingly aware of the value mature trees bring to property valuations. According to the urban tree care framework, increased urban sprawl and aging tree stocks require professional risk mitigation well into 2026.

    How Labor Shortage Shapes Pricing and Operations

    Despite strong demand, a shortage of certified arborists is reshaping the sector. In acute markets, residential prices have risen 15–20% as firms bid up wages. Adoption of AI-powered tree risk assessment technology allows crews to prioritize inspections using drone imagery, mitigating the shortage by improving efficiency for existing staff.

    Investment Valuation and Capital Formation in the Tree Care Sector

    Understanding tree care industry trends 2026 is essential for business owners. Valuation typically revolves around adjusted EBITDA multiples in the 3-5x range. Beyond traditional metrics, companies demonstrating AI-powered tree risk assessment technology implementation and climate-resilient urban canopy management command premium pricing from institutional investors.

    How is AI transforming tree risk assessment in 2026?
    AI-powered tree risk assessment technology uses predictive analytics to detect hazards early, reducing emergency costs and improving safety.

    What is climate-resilient urban canopy management?
    It focuses on selecting diverse, drought-tolerant species and strategic planting to help urban forests weather climate shifts.

    Why choose a veteran-owned tree service?
    Consider a veteran owned tree service like Climbing Grunt for discipline and commitment to safety.

    Resources

  • Institutional Capital Sources: Ultimate Guide to Private Credit

    Institutional Capital Sources: Ultimate Guide to Private Credit

    Table of Contents

    Understanding Institutional Capital Sources

    Institutional capital sources represent large pools of investment funds managed by organizations such as pension funds, insurance companies, sovereign wealth funds, and private credit funds. These entities provide substantial financing for corporate growth, acquisitions, and real estate ventures.

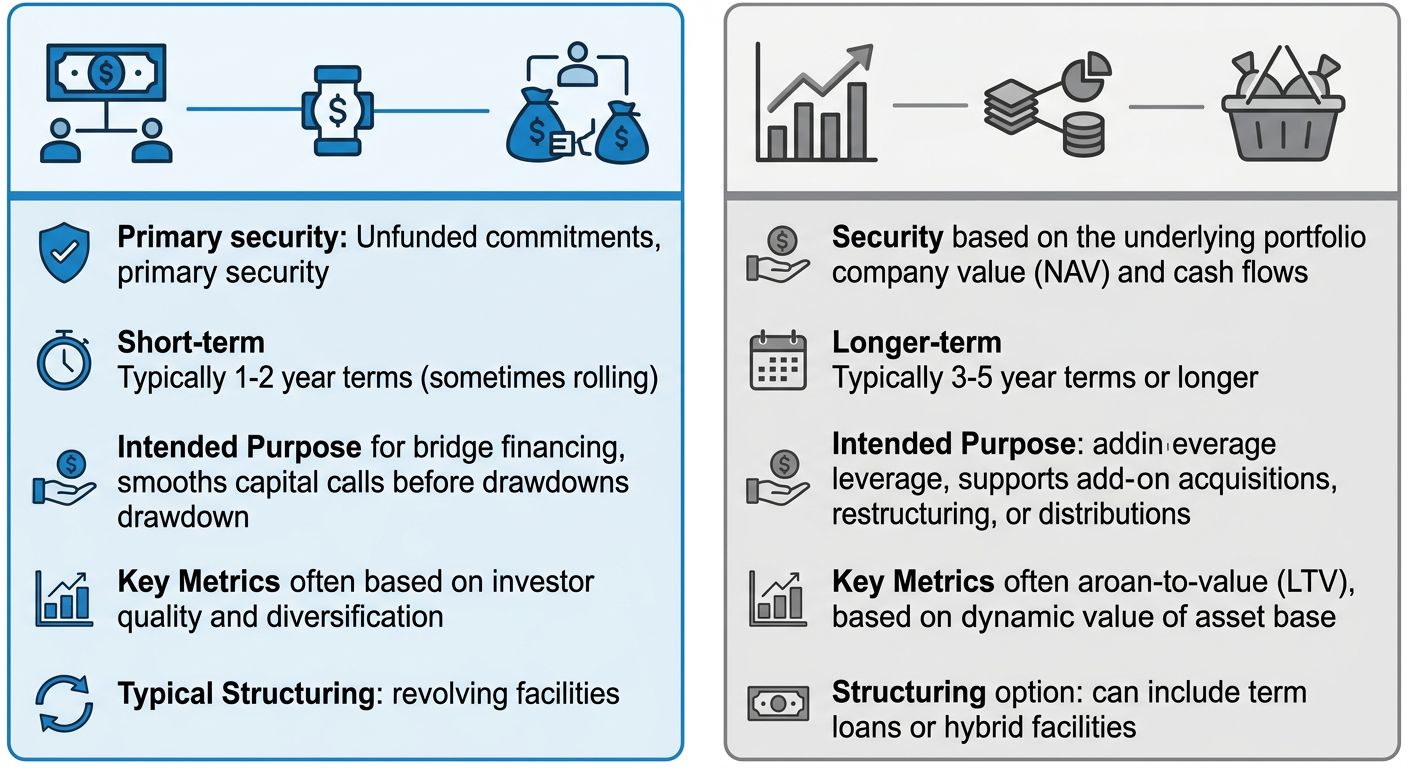
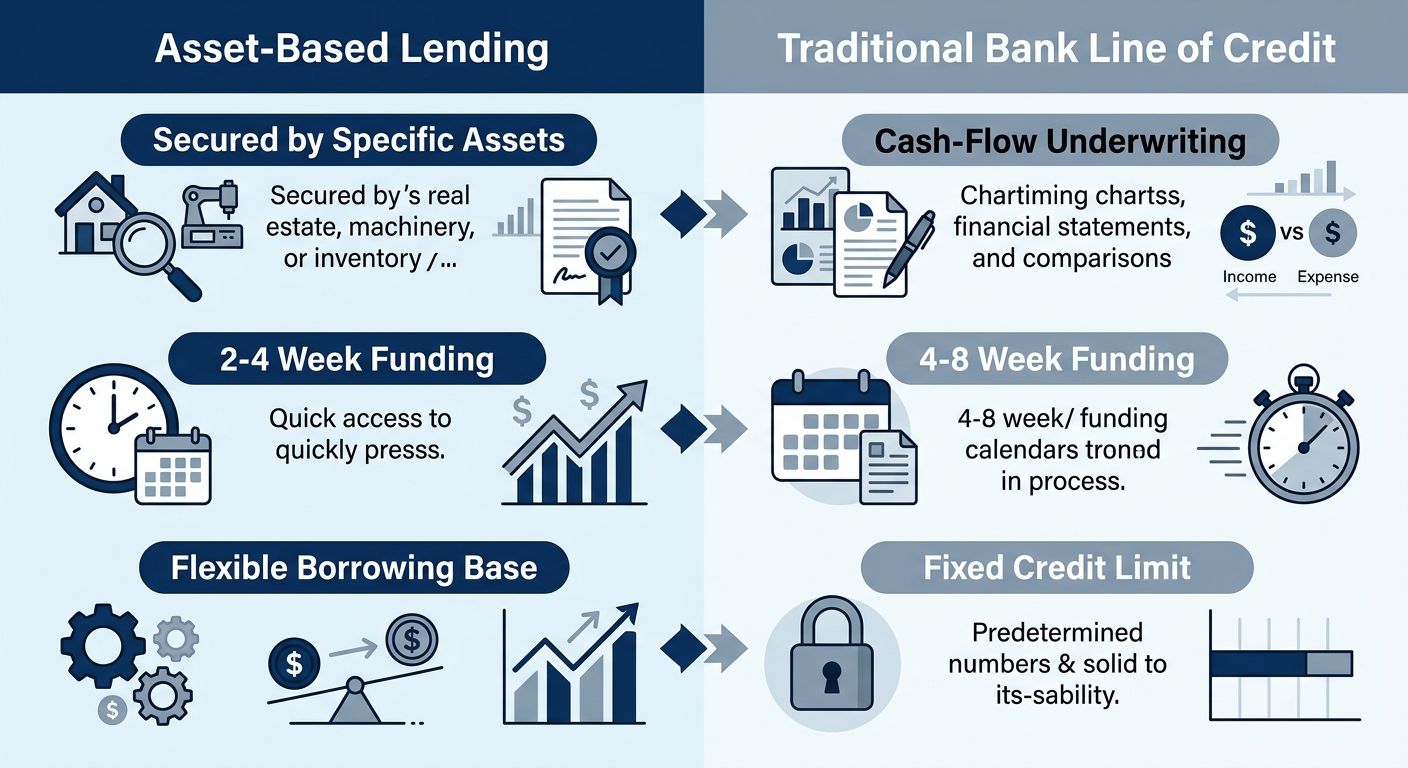
    Private credit lenders operate in the direct lending space, offering customized financing solutions through asset-based lending and cash flow financing structures. Through our global lending services, companies can access these tailored institutional funding options. These lenders typically seek long-term partnerships with growing businesses, providing larger capital amounts with more flexible terms than traditional bank financing.

    Sovereign wealth funds, such as those in the Middle East and Asia, are government-owned investment vehicles that deploy capital into infrastructure, real estate, and strategic sectors globally. These government investment funds bring patient capital with extended investment horizons.

    Through our network of over 4,000 global investors, we connect clients with institutional investor capital sources suited to their transaction requirements. Securities offerings are facilitated through Finalis Securities LLC, a registered broker-dealer.

    Assess Your Readiness for Institutional Capital

    Institutional capital sources such as private credit lenders and sovereign wealth funds can provide transformative financing for growth-stage companies. At Zaidwood Capital, we encourage businesses to assess their readiness across several key dimensions before engaging these sophisticated capital partners.

    • Financial and asset readiness: Investors generally expect at least $5–$10 million in revenue and positive EBITDA. For asset-based lending, clear collateral coverage and strong asset quality are critical. And liquidity runway matters.
    • Management and governance: An experienced leadership team, a clean capitalization table, and transparent financial reporting demonstrate organizational maturity and reduce investor risk.
    • Market positioning: Defensible competitive advantages, a clear growth trajectory, and a large addressable market signal the ability to scale and capture value.
    • Compliance and due diligence readiness: Companies must be prepared to meet SEC regulations (including Regulation D) and have audited financials, legal documents, and a compelling pitch deck ready.

    Assessing these areas objectively is the first step. Engaging professional capital advisory services can help bridge any gaps, guiding you through due diligence and matching your profile with institutional investors who align with your growth objectives.

    Identify Target Institutional Investor Profiles

    Identifying the right institutional capital sources is the foundation of every transaction we advise on. Within the global capital ecosystem, we isolate institutional investor profiles that align precisely with each client’s industry, deal size, and financing structure—whether equity, debt, or hybrid capital.

    Our process draws on data published by the Federal Reserve Bank of New York to track institutional activity and capital flow trends, revealing which investor segments are most active for a given mandate. We then apply classification standards from the International Capital Market Association to map investors by risk appetite, asset class preference, and transaction size thresholds. This shapes a shortlist that can include private credit lenders, sovereign wealth funds, pension funds, endowments, and family offices.

    Through our mergers and acquisitions advisory, we connect each institutional profile to the appropriate transaction structure and capital strategy. With an aggregated network of over 4,000 institutional and private investors representing more than $15 billion of deployable capital, updated quarterly, we can surface the institutional capital pools most relevant to your objectives.

    This information is for informational purposes only and does not constitute an offer. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Prepare Investor Pitch Materials

    Based on the due diligence insights gathered earlier, we now assemble investor pitch materials designed to secure funding from institutional capital sources. This critical step translates analytical findings into compelling narratives that drive investment decisions. Our approach leverages Zaidwood Capital’s Full-Cycle M&A and capital advisory framework.

    • Value Proposition & Market Analysis: We craft a clear narrative that connects your opportunity to institutional capital sources, including a market analysis slide.
    • Targeted Messaging: Debt-oriented materials resonate among private credit lenders, while equity pitches are assessed by sovereign wealth funds.
    • Financial Projections: All pro formas carry the disclaimer: “These projections are for informational purposes and do not guarantee future results.”
    • Compliance & Regulatory Requirements: Every deck includes risk factors as required by the SEC. We are not a registered broker-dealer; securities are offered through Finalis Securities LLC. Always refer to the securities regulation authority for updated guidance on private placement rules.
    • Zaidwood Capital Advantage: Our Deal Vault and 4,000+ global investors provide a distribution edge without implying guaranteed outcomes.

    With completed materials, we move to presenting them through our institutional network of over 4,000 investors. Book a Call to finalize your materials and start engaging capital sources.

    Approach Sovereign Wealth Funds and Endowments

    We access diverse institutional capital sources by targeting sovereign wealth funds (SWFs) and endowments, each with distinct mandates. SWFs, such as stabilization funds in the Middle East, seek long-term value creation, while university endowments based in the US follow spending policies that balance growth and liquidity. Identifying these mandates is the critical first step in full-cycle M&A and capital advisory.

    Our engagement strategy leverages proprietary data, specifically the Sovereign Data Nexus, to pinpoint funds with aligned investment criteria. We then initiate contact through investor relations channels, presenting our capital introductions and due diligence capabilities. Communications are structured to comply with regulatory frameworks, including those established by the Financial Industry Regulatory Authority (FINRA), which governs promotional materials and accredited investor verification.

    We apply the Velocity Matrix to structure and accelerate deal flow, combined with Precision Catalyst for targeted matching between opportunities and institutional pools. We explicitly avoid promising specific outcomes or guaranteeing transactions. This website is for informational purposes only and is not an offer or solicitation. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. Beyond sovereign wealth funds and endowments, institutional capital sources include private credit lenders, which we address next.

    Engage Private Credit Lenders

    As we expand the discussion beyond traditional institutional capital sources, private credit lenders represent a distinct and increasingly vital segment of the financing landscape. These are institutional investors — from specialized debt funds to family offices and sovereign wealth funds — that provide non-bank financing directly to companies. At Zaidwood Capital, we connect our clients to a deep network of these alternative capital providers.

    Two of the most common structures offered by private credit lenders are asset-based lending, which is secured by a company’s tangible assets, and cash flow financing, which is underwritten against projected revenue streams. Our qualification framework, which mirrors the rigorous documentation standards benchmarked by the International Capital Market Association (ICMA), ensures a smooth due diligence process. The broader liquidity environment, shaped by Federal Reserve Bank services, continuously affects the terms and availability of capital from these lenders.

    We facilitate these engagements by aligning a client’s financial profile — supported by three years of audited financials and multi-year cash flow projections — with the specific mandates of institutional investors. Individual outcomes will vary, but this targeted approach helps streamline what is often a complex capital raise, setting the stage for us to explain how we actively enable these introductions.

    Before any deal closes, a thorough due diligence and legal review must be completed. We guide clients through this phase to identify risks, verify claims, and ensure regulatory compliance, a prerequisite for attracting institutional capital sources like private credit lenders and sovereign wealth funds.

    Adhering to SEC securities regulation ensures disclosure compliance and reduces legal risk. The U.S. Securities and Exchange Commission (SEC) sets the baseline for securities offerings and anti-fraud provisions. Meanwhile, FINRA oversees the broker-dealer firms that execute transactions, adding another layer of oversight that institutional investors demand.

    A typical review includes:

    • Regulatory compliance check (SEC rules)
    • Broker-dealer oversight (FINRA)
    • Legal document review (NDAs, term sheets, purchase agreements)
    • Client material preparation (deal memoranda, legal opinions)

    This rigorous process satisfies the due diligence standards of private credit lenders and sovereign wealth funds. Once regulatory compliance is confirmed, our Full-Cycle M&A and capital advisory team streamlines the transition to negotiation and closing. (This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to transact. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.)

    Negotiate Terms and Structure the Deal

    Once due diligence confirms the opportunity, the next phase is negotiating terms and structuring the deal to align with the expectations of institutional capital sources. Negotiating with institutional capital sources requires understanding their distinct priorities: private credit lenders typically focus on cash-flow coverage, collateral quality, and floating-rate benchmarks tied to effective Fed funds, while sovereign wealth funds often seek co-investment rights, board representation, and long-term alignment with investment horizons. Current monetary policy, as reflected in rate data from the Federal Reserve Bank of New York, directly influences structure choices—floating versus fixed rates, coupon floors, and covenant flexibility. At Zaidwood Capital, we leverage our full-cycle advisory and proprietary Sovereign Data Nexus to customize structures that balance these competing demands and institutional investor preferences. With terms negotiated and structure agreed, the transaction moves to documentation and closing.

    Close and Maintain Institutional Relationships

    We actively identify and cultivate long-term partnerships with institutional capital sources that align with our clients’ strategic objectives. Operating outside the scope of a registered broker-dealer — a distinction clarified by the Financial Industry Regulatory Authority (FINRA) — we serve as a capital introduction intermediary, facilitating connections rather than executing securities transactions.

    Our network spans sovereign wealth funds, private credit lenders, pension funds, endowments, foundations, and insurance companies. Through our proprietary Sovereign Data Nexus and Velocity Matrix platforms, we match clients to these institutional capital sources based on investment criteria, sector focus, and capital requirements. Beyond the initial introduction, we maintain these relationships through periodic updates, reporting, and facilitated meetings — ensuring sustained engagement without guaranteeing specific outcomes.

    With access to 4,000+ global investors and over $15 billion in deployable capital, we are positioned to support your capital formation goals. Book A Call to discuss your institutional strategy.

    Overcoming Common Barriers to Institutional Capital

    However, accessing these institutional capital sources is not automatic — companies must overcome several well-known hurdles. Many businesses find that institutional capital sources from sovereign wealth funds and other large investors remain out of reach due to gaps in documentation, governance, and financial transparency.

    A frequent barrier is insufficient or poorly organized asset documentation, which prevents companies from qualifying for asset-based lending. Our FAQ outlines that institutions require a clear, verifiable collateral base and detailed asset records. For asset-based lending or cash-flow financing, presenting a strong collateral package and a verifiable cash-flow history is essential. Companies that invest in structured asset tracking and formal appraisals greatly improve their eligibility and signal readiness to private credit lenders.

    Lack of audited financial statements and credible cash-flow projections is another top reason for rejection. Institutional investors typically require three years of audited financials and three- to five-year cash-flow forecasts. Our qualification framework shows that without these, even otherwise healthy businesses struggle to demonstrate their repayment capacity. By committing to regular audits and building realistic, multi-year projections, companies can close this critical gap.

    Inadequate governance structures and limited credit histories further complicate access. The International Capital Market Association (ICMA) emphasizes that institutional investors expect transparency, standardized reporting, and robust risk management. Adopting these standards reduces friction and builds the confidence of sovereign wealth funds and private credit market lenders. Additionally, preparing a detailed business plan with pro-forma financials, a clear use-of-funds explanation, and a credible repayment strategy demonstrates the kind of institutional readiness that professional investors expect.

    Proactive preparation and early engagement with a capital advisor can streamline the entire process. With proper documentation and governance alignment, these barriers can be systematically addressed — which is exactly where our Full-Cycle M&A and capital advisory services come into play.

    Your Pathway to Institutional Capital

    Accessing institutional capital sources—from private credit lenders in the US to sovereign wealth funds worldwide—requires a partner with deep investor relationships. Our network includes pension funds, family offices, and other institutional investors. Zaidwood Capital connects you to over 4,000 investors with more than $15B in deployable capital.

    Our proprietary tools—Sovereign Data Nexus, Precision Catalyst, and Velocity Matrix—streamline due diligence, investor outreach, and deal execution. With $24.4B+ in aggregate transaction volume and more than 300 deals completed, we deliver full-cycle M&A and capital advisory. Securities are offered through Finalis Securities LLC (member FINRA/SIPC) in compliance with regulatory requirements. Past performance does not guarantee future results.

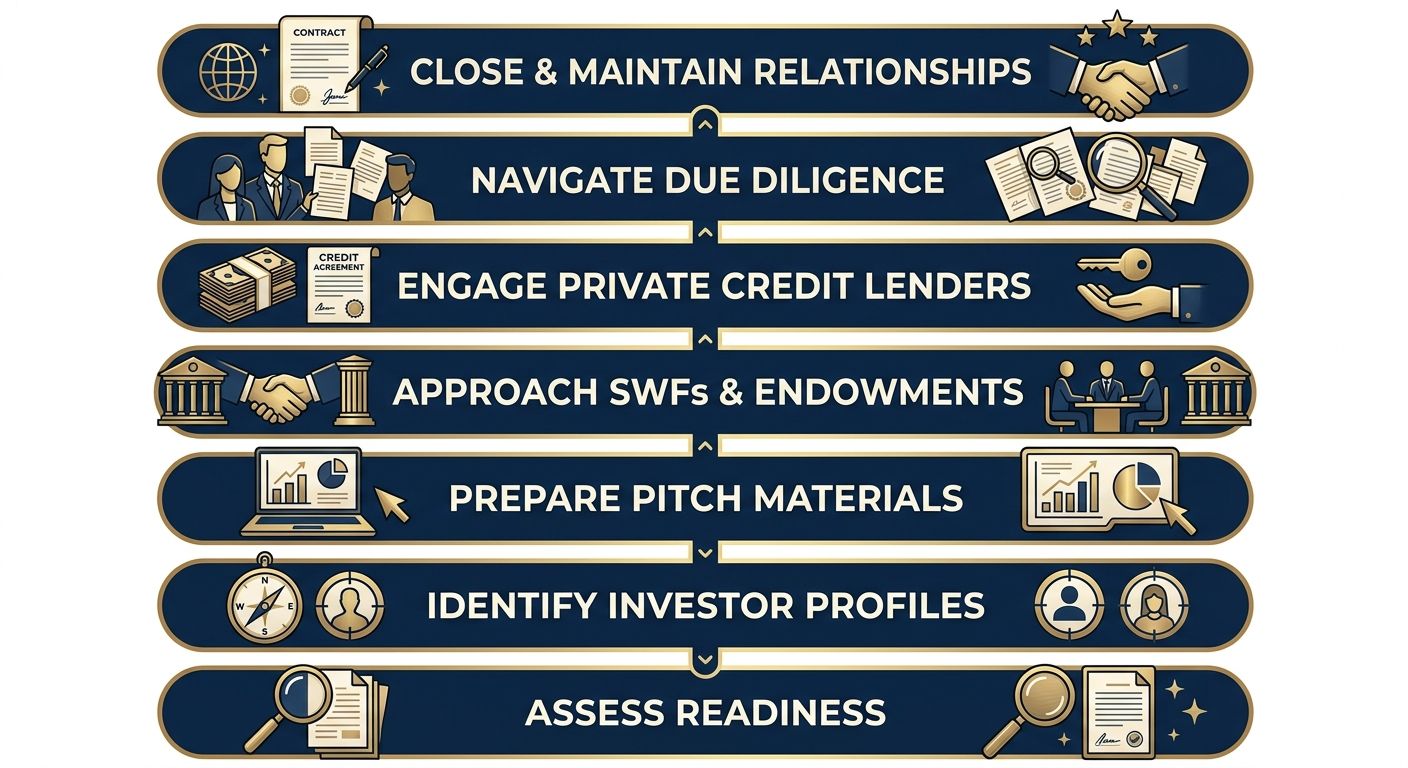
    Seven-step capital pathway infographic showing each advisory stage from readiness assessment to deal closing and relationship management.

    Your Pathway to Institutional Capital in seven clear steps

    This seven-step process brings clarity to every phase of capital raising, from readiness assessment to deal closing. Begin your pathway today. Book a call with our team to discuss your capital raising goals and discover how our investor network can work for you.

    Resources

  • Best Quality of Earnings Report for Mid-Market Deals 2026

    Best Quality of Earnings Report for Mid-Market Deals 2026

    Table of Contents

    The Role of Quality of Earnings Reports in Mid-Market M&A

    Following a comprehensive due diligence review, buyers and lenders in mid-market M&A transactions focus on the Quality of Earnings (QoE) report, an independent assessment of a target company’s historical financial performance, adjusted for non-recurring items. This analysis goes far beyond audited financials by evaluating revenue sustainability, customer concentration, and the normalization of operating expenses and working capital. A well-prepared quality of earnings report provides a clearer view of recurring EBITDA, which serves as the foundation for valuation and debt sizing.

    Why QoE Matters in Mid-Market Deals

    The insights from an earnings quality analysis routinely reshape transaction terms. Buyers use the adjusted EBITDA to support purchase price adjustments, earnout structures, and net-working-capital targets. Lenders, in turn, demand a validated earnings baseline before committing acquisition debt. Moreover, the QoE often uncovers deferred-revenue patterns or concentration risks that, if ignored, can surface as costly post-close liabilities. In mid-market transactions where information gaps are common, a thorough QoE report reduces post-close surprises and gives the commissioning party a stronger negotiating position.

    Because mid-market companies frequently lack the internal resources to produce a GAAP-independent earnings analysis on their own, many engage specialized M&A advisors to manage the QoE process. At Zaidwood Capital, we integrate the QoE directly into our full-cycle due diligence offering, coordinating with independent accounting firms to deliver a report that buy-side and sell-side clients can rely on during negotiation and financing. We handle all financial data in accordance with rigorous confidentiality standards. For information on how we protect client information, please review Zaidwood Capital Privacy Policy.

    What Defines a Quality of Earnings Report

    A critical subset of due diligence, central to mid-market transaction diligence, is the Quality of Earnings Report, a financial analysis that evaluates the recurring, normalized earnings of a target company. At Zaidwood Capital, we define a QoE report as a rigorous assessment of earnings sustainability, designed to strip out non-recurring items and present a true picture of operating performance. This analysis is a cornerstone of our full-cycle due diligence process for mid-market M&A transactions.

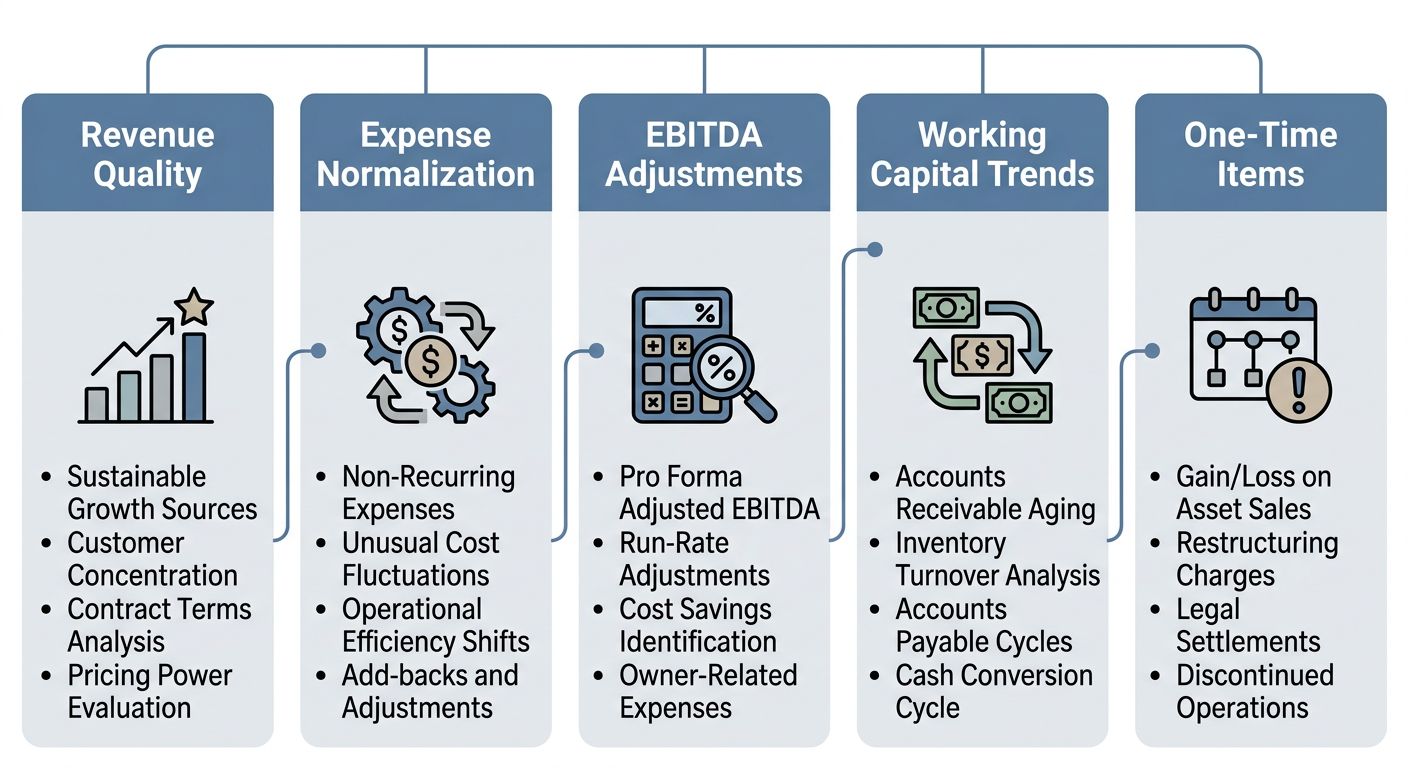
    A comprehensive earnings quality analysis examines several critical areas. Revenue quality scrutinizes the predictability and diversification of income streams. Expense normalization adjusts for one-time costs, owner’s compensation, or other out-of-ordinary expenses. EBITDA adjustments remove non-operating or non-cash items to reflect sustainable earnings. Working capital trends highlight operational liquidity needs and potential cash drags. One-time items, such as litigation settlements or asset sales, are excluded to reveal the underlying earning power. These dimensions collectively inform whether the company’s earnings are sustainable and repeatable for future periods.

    Infographic with five columns representing core areas of a quality of earnings analysis: Revenue Quality, Expense Normalization, EBITDA Adjustments, Working Capital Trends, and One-Time Items, each with icons and bullet lists on a muted blue and gray palette.

    Zaidwood Capital’s Quality of Earnings analysis framework visualized in five key areas.

    By producing a normalized earnings base, the QoE report helps both buyers and sellers reach consensus on valuation. For buy-side M&A professionals, this analysis highlights the true recurring profitability of a target, removing distortions that could inflate or deflate the purchase price. Sellers also benefit, as a well-documented QoE report can justify a premium and accelerate negotiation.

    As part of our Full-Cycle M&A and capital advisory services, we integrate QoE analysis into every engagement to provide clients with clear, defensible financial insights. The report is not an audit; it does not verify financial statement accuracy in compliance with accounting standards. Instead, it offers transaction-specific intelligence that traditional audits often miss. Zaidwood Capital utilizes QoE reports as a core component of its full-cycle due diligence, ensuring that both buy-side and sell-side mandates are grounded in reliable earnings data. By identifying true economic earnings, a QoE report streamlines negotiations and reduces the risk of post-close surprises.

    Next, we examine the core components that define a comprehensive QoE analysis.

    Securities are offered through Finalis Securities LLC, an independent entity from Zaidwood Capital. This content is for informational purposes and does not constitute investment advice.

    Core Components of a Quality of Earnings Analysis

    A quality of earnings report for mid-market deals goes beyond audited financials to uncover the true recurring cash flow a buyer can rely on. In this section, we break down the three pillars of a quality of earnings analysis: normalization adjustments, working capital scrutiny, and EBITDA sustainability. Drawing on Zaidwood Capital’s due diligence expertise, we show how each component strengthens deal-making for institutional and private investors.

    Normalization Adjustments and Add-Backs

    Normalization adjustments strip away non-operational or inflated expenses to present a clean EBITDA. These adjustments are critical because audited financials may include non-recurring gains or expenses that distort the company’s sustainable earning power. In our analyses, we identify above-market owner compensation, one-time legal fees, personal expenses run through the business, and related-party transactions at non-market terms.

    • Owner’s Compensation Adjustment: Aligning above-market owner salary and benefits to industry-standard compensation for a replacement manager
    • Non-Recurring Expenses: One-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition
    • Personal Expenses: Personal travel, entertainment, vehicles, or family members on payroll not related to business operations
    • Related-Party Transactions: Above-market rent, management fees, or service charges paid to entities owned by the seller or their family

    We substantiate each adjustment with corroborating evidence—payroll records, lease agreements, invoices—and provide a clear rationale in our reports. A quality of earnings analysis also flags off-balance-sheet liabilities like operating leases or contingent obligations that can alter deal value. For example, an owner drawing $600,000 when market rate is $200,000 inflates expenses by $400,000, a typical adjustment we see. By documenting every add-back, we give buyers confidence in the normalized earnings figure. Additionally, QoE reports look beyond the balance sheet to identify contingent payments or environmental indemnities that may not be booked but represent real future cash outflows.

    Working Capital Analysis and Debt-Like Items

    Working capital analysis determines the normalized net operating capital needed post-acquisition. We assess seasonal needs, payment cycles, and industry norms, then compare that to the target company’s actual levels. The gap—whether surplus or deficit—becomes an adjustment to the purchase price. For instance, if a business has excess working capital relative to its normalized requirement, the buyer may credit the seller for that amount at closing; conversely, a deficiency reduces the price. Our QoE reports present these adjustments with supporting schedules so that both buyers and sellers can negotiate from a common understanding.

    Debt-like items are obligations that function as debt but are not on the balance sheet as such. Examples include deferred revenue, underfunded pensions, or installment sale obligations. We identify these, quantify their impact, and deduct them from the equity value, just as we would formal debt. This analysis prevents the buyer from inheriting hidden financial burdens and ensures the enterprise value accurately reflects the business’s true financial position.

    EBITDA Quality and Sustainability Assessment

    EBITDA sustainability evaluation dissects the recurring nature of earnings. We examine revenue concentration risk—if a company depends on a single customer for more than 10% of revenue, that concentration creates vulnerability. Customer retention trends, contract renewal probabilities, and churn rates indicate how sticky the revenue base is. We also assess margin stability, checking whether gross and operating margins are sustainable or eroded by pricing pressure. In emerging markets M&A, we place extra focus on revenue concentration and retention because currency swings, regulatory shifts, and political instability can quickly reshape earnings. We evaluate supplier relationships to ensure margins are not artificially supported by short-term concessions, and we consider macroeconomic trends that could influence future earnings. Through our QoE reports, we help buyers distinguish durable cash flows from those that could evaporate post-acquisition, providing a forward-looking perspective essential for informed investment decisions.

    Selecting a Quality of Earnings Provider for Your Mid-Market Deal

    A quality of earnings report for mid-market deals is one of the most important tools for de-risking an acquisition, and choosing the right provider directly influences the credibility of your financial analysis. For companies in the $20M–$100M revenue range, the provider’s expertise, speed, and post-engagement support can make a material difference in how the QoE findings are received by lenders, underwriters, and counterparties.

    Evaluating Boutique Firm Expertise for QoE Analysis

    Boutique firms such as Zaidwood Capital specialize in delivering a highly tailored Quality of Earnings analysis that aligns with the specific dynamics of mid-market transactions. Their teams typically bring deep industry knowledge and direct senior partner involvement, ensuring that the engagement is led by an experienced professional who understands both the financial and strategic dimensions of the deal. In contrast, Big Four accounting firms offer a broad, generalist approach with standardized QoE templates that can miss the nuances of niche sectors. Mid-tier regional firms occupy a middle ground, providing moderate specialization but often with less senior oversight than a dedicated boutique.

    The critical differentiator is the level of partner engagement. At a boutique, the senior team leads the QoE analysis from start to finish, which shortens feedback loops and results in a more focused report. Big Four firms typically rely on junior staff for the bulk of the fieldwork, with partner review at the conclusion, while mid-tier firms show variability in senior involvement. This direct access to senior talent often translates into faster turnaround times and more actionable insights for the acquirer.

    The following comparison table summarizes key distinctions to inform your selection.

    Common Add-Backs and Adjustments in Quality of Earnings Reports
    Adjustment TypeDescriptionTypical EBITDA ImpactCommon Example
    Owner’s Compensation AdjustmentAligning above-market owner salary and benefits to industry-standard compensation for a replacement manager+$150,000 to $500,000 add-backOwner paying themselves $600,000 when market rate for a general manager is $200,000
    Non-Recurring ExpensesOne-time legal fees, consulting engagements, relocation costs, or restructuring charges unlikely to repeat post-acquisition+$50,000 to $300,000 add-back$200,000 in legal fees from a one-time litigation matter
    Personal ExpensesPersonal travel, entertainment, vehicles, or family members on payroll not related to business operations+$25,000 to $150,000 add-backCompany-leased luxury vehicle used primarily for personal use
    Related-Party TransactionsAbove-market rent, management fees, or service charges paid to entities owned by the seller or their family+$75,000 to $400,000 add-backPaying $30,000/month rent to a seller-owned LLC when market rate is $15,000

    Boutique firms consistently deliver deep specialization and hands-on partner involvement, often completing a QoE engagement in as little as 2–4 weeks—roughly half the time of a Big Four engagement. Moreover, firms like Zaidwood Capital adhere to established capital markets best practices, incorporating frameworks from ICMA capital markets to ensure the analysis meets rigorous industry standards. This commitment to both speed and quality makes boutique advisors a compelling choice for mid-market acquirers.

    Scope and Cost Expectations for Mid-Market Companies

    For a $20M–$100M-revenue company, the scope of a Quality of Earnings engagement should be calibrated to deal complexity and the acquirer’s specific concerns. A one-size-fits-all report rarely adds value; instead, the engagement scope must be defined collaboratively, focusing on revenue recognition policies, working capital trends, customer concentration risks, and any carve-out adjustments that could affect normalized EBITDA. At Zaidwood Capital, we work directly with buyers to design a custom scope that addresses the unique drivers of the target business, avoiding unnecessary line items that inflate cost without improving decision-making.

    Cost expectations reflect the level of customization. Boutique firms like Zaidwood Capital typically quote $25,000–$50,000 for a $20M-revenue company, while Big Four firms can range from $75,000 to over $150,000 for a similar-sized engagement. Mid-tier regional firms generally fall between $40,000 and $80,000. All figures are custom quotes and depend on data availability, the number of entities involved, and the speed required. We emphasize that our pricing is never a fixed fee; each engagement is priced based on the precise scope and timeline agreed upon, with full-cycle support extending from the initial QoE analysis through deal close.

    Integrating QoE Findings into Deal Structuring

    A Quality of Earnings report is not just a diligence artifact—it directly shapes the final deal terms. When normalized EBITDA adjustments reveal that reported earnings overstate true recurring cash flow, buyers can negotiate purchase price reductions or post-closing true-ups. Earnout structures become more defensible when the QoE identifies revenue volatility or concentration risks that warrant contingent payments. Similarly, representation and warranty insurance underwriters increasingly rely on QoE findings to set coverage limits and exclusions, making a thorough report a valuable risk-transfer tool.

    At Zaidwood Capital, our full-cycle advisory model ensures that QoE insights flow seamlessly into the negotiation and documentation phases. We translate EBITDA adjustments into specific purchase price adjustment mechanisms, design earnout milestones linked to verifiable financial metrics, and help acquirers present the QoE to insurers to secure favorable underwriting terms. This integrated approach reduces re-trading risk and accelerates the path to a signed purchase agreement. Once you have selected the right partner, the next step is implementing a disciplined QoE process that turns financial analysis into concrete deal terms. As with any investment, past performance does not guarantee future results, and we recommend consulting professional advisors to tailor the approach to your deal.

    How Quality of Earnings Reports Influence Purchase Price and Deal Terms

    A quality of earnings report for mid-market deals does more than flag accounting irregularities; it serves as the core negotiating lever for adjusting the purchase price and crafting protective deal provisions. At Zaidwood Capital, we treat the QoE report as the definitive source for reconciling reported financials with normalized economic reality. This alignment is essential before we engage in price discussions.

    In our experience, the most direct impact of the QoE report is a purchase price adjustment derived from normalized EBITDA. When the report strips out non-recurring revenue or one-time expenses, it recalibrates the basis on which the acquisition multiple is applied. A lower sustainable EBITDA can reduce the implied valuation, prompting the buyer to seek a price reduction. Conversely, a seller whose earnings prove clean and recurring can leverage the report to sustain or elevate the offer. Beyond EBITDA, the working capital peg—determined by historical QoE trend analysis—can shift the final cash consideration. If the report reveals that the target’s normalized net working capital is lower than originally represented, the buyer rightfully demands a dollar-for-dollar reduction at closing. Sellers with positive QoE results often use this as a shield against overly burdensome indemnification clauses, while buyers rely on the analysis to insert additional covenants or expand representations and warranties when risks are evident.

    Earnout structures are another area where QoE findings carry substantial weight. We typically link earnout payments to forward-looking financial metrics that have been validated by the quality of earnings (QoE) review. This ensures that post-closing milestones are both achievable and reflective of the business’s true earning power, reducing disputes later. Likewise, indemnification horizons and escrow amounts are calibrated to the specific risks flagged in the report. A revenue recognition issue might extend the survival period for related claims and increase the escrow holdback, while a clean report shortens those protections. Underpinning this rigor are regulatory standards that shape our financial analysis. FINRA securities regulation, administered by the Financial Industry Regulatory Authority, sets expectations for broker-dealer reporting that influence how we assess earnings quality in private transactions. Similarly, SEC securities regulation, enforced by the U.S. Securities and Exchange Commission, mandates GAAP compliance and reinforces the importance of accurate data in all valuations. In the following section, we demonstrate how these adjustments play out in a real mid-market transaction.

    Common Questions About Quality of Earnings Reports in Mid-Market Deals

    After establishing the importance of a quality of earnings report for mid-market deals, we address the most common questions buyers and sellers ask before engaging a QoE provider.

    What is a quality of earnings report, and why is it essential for mid-market deals? A QoE analysis examines earnings sustainability and quality, revealing adjustments needed in private-company financials and uncovering risks like customer concentration.

    How does a QoE differ from standard due diligence, and what adjustments does it uncover? Unlike standard due diligence, a QoE report serves as a complementary tool—used by advisors like Zaidwood Capital—to examine normalized EBITDA, margin trends, and working capital, separating recurring from one-time items and revenue mix.

    How does a QoE report impact valuation and deal structure? By surfacing these insights, a QoE can bridge valuation gaps and influence purchase price multiples, giving both sides clearer grounds for negotiation.

    Next, we’ll walk through the practical steps of commissioning a QoE report for your mid-market transaction.

    Leveraging Quality of Earnings Reports for Smarter M&A Decisions

    A Quality of Earnings report for mid-market deals dissects financials to expose sustainable earnings by stripping out one-offs. It flags risks like premature revenue booking, strengthening your negotiation position. Mid-market firms with less polished reporting especially benefit. At Zaidwood Capital, a quality of earnings report for mid-market deals anchors our full-cycle due diligence, alongside operational, commercial, and IT assessments, to deliver a complete picture. Compliance with SEC securities regulation ensures data reliability, and leveraging QoE minimizes post-close shocks. Deeper insight drives smarter M&A decisions.

    Resources

  • Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Table of Contents

    Choosing Between Boutique and Bulge Bracket Investment Banking

    When weighing boutique vs bulge bracket investment banking, the core distinction lies in service scope and client intimacy. Specialist advisory firms offer focused, senior-led strategies that often result in faster execution and stronger alignment with client goals. Large global banks provide extensive capital markets access and resources suited for complex cross-border mandates. For companies considering private equity exit opportunities, boutique advisors frequently deliver customized positioning within their specific industry ecosystems. Similarly, talent dynamics around investment banking compensation packages reflect the differing demands of these models. We track SEC regulatory updates closely, as heavier compliance overhead affects larger institutions disproportionately while we leverage our full-cycle M&A and capital advisory approach to integrate deep advisory with proprietary data, streamlining transactions without the structural friction of multi-layered global firms.

    Ultimately, choosing between these paths depends on your transaction scope and strategic priorities. Our model bridges the gap by combining the personalized guidance of a boutique with the data-driven precision and investor network scale that growing companies require, a balance explored further in the next section.

    1. Senior Banker Attention and Personal Service

    In the boutique vs bulge bracket investment banking debate, one key differentiator is the level of senior attention you receive. At large, full-service firms, deal execution is often delegated to junior teams while managing directors appear only at critical milestones. We find this approach can dilute accountability and slow decision-making.

    Our model is fundamentally different. When you engage a boutique investment banking firm like Zaidwood Capital LLC, your mandate is led directly by our principals from pitch to close. As outlined in our description of M&A advisory services, senior bankers provide strategic guidance, valuation, negotiation support, and hands-on deal management throughout the entire lifecycle. This structure ensures decades of combined experience are applied to your specific strategic goals, delivering more tailored advice and faster execution.

    This personalized service is particularly valued by private equity firms seeking seamless exit execution and by companies requiring discreet, high-touch advisory. By leveraging our proprietary network and data resources, our senior team simplifies complex transactions, embodying our commitment to Streamlining Transactions with precision and focus.

    2. Tailored Fee Structures for Mid-Market Deals

    When considering boutique vs bulge bracket investment banking, the fee negotiation dynamics shift substantially for middle-market transactions. Unlike the rigid, standard pricing grids common at large institutions, we design our compensation around each mandate’s unique contours. This flexibility ensures your advisory costs reflect actual deal complexity rather than a one-size-fits-all schedule, aligning our incentives directly with your outcome.

    A typical framework might blend an initial retainer with a success-based component, or we may structure a milestone-driven fixed fee for a carve-out divestiture. The mix is always negotiated, absorbing variables like target size, cross-border diligence, and sector-specific resource requirements. For private equity firms managing portfolio company exits, this custom approach preserves more equity value while delivering institutional-quality execution. Our compensation benchmarks, detailed on our FAQ page, illustrate how tailored structures sit competitively within industry norms. As we always clarify, fees are custom-quoted and subject to mutual agreement rather than a published rate card.

    This disciplined yet adaptable approach removes friction from the engagement, letting you forecast costs with clarity. Next, we will walk through how our execution process turns that aligned structure into deal momentum.

    3. Specialized Industry Expertise

    Specialized industry expertise is a defining hallmark of the boutique model in investment banking. Unlike generalist institutions, boutique firms concentrate intellectual and relational capital into targeted verticals, cultivating an intimate understanding of sector dynamics, competitive landscapes, and value drivers. In private equity exit opportunities, this depth translates directly into superior deal sourcing because advisory teams speak the same operational language as founders, operators, and institutional buyers. Drawing from our own capital network exceeding $15 billion and an aggregate transaction volume surpassing $24.4 billion, we see consistent evidence that specialization sharpens valuation insight and accelerates execution.

    Sector-specific knowledge also shapes how boutique teams prepare portfolio companies for exit. Advisors often bring prior operating experience within the industries they serve, allowing them to anticipate buyer diligence questions and position assets around the metrics that matter most to private equity firms. When general partners evaluate acquisition targets, they rely on advisors who can interpret unit economics, regulatory nuances, and customer concentration risks without a learning curve, an advantage that industry depth systematically delivers.

    Industry depth shortens timelines and reduces transaction friction, qualities that matter acutely when fund lifecycles and market windows dictate exit timing. The structural alignment between boutique specialization and private equity mandates explains why sector-focused advisory teams continue gaining share in middle-market transactions. As the discussion shifts toward compensation structures, that same specialized expertise becomes a tangible factor influencing how transaction professionals are rewarded for execution.

    4. Agile Decision-Making and Speed

    Agile decision-making and speed represent some of the most compelling differentiators when evaluating boutique vs bulge bracket investment banking advisory services. At Zaidwood Capital, our lean, partner-led structure eliminates the multiple layers of approval and internal bureaucracy that typically slow down larger institutions. This streamlined architecture translates into faster, more decisive action for our clients.

    The role of an M&A advisor is inherently to accelerate deal timelines through proactive market intelligence and efficient coordination of due diligence. We execute this through our proprietary Velocity Matrix framework, which drives transaction velocity without compromising the depth or quality of our analysis. This systematic approach ensures that while we move quickly, we never sacrifice the financial, legal, and operational rigor that complex transactions demand.

    This responsiveness is particularly critical for owners pursuing private equity exit opportunities, where market windows can close rapidly and timing often correlates directly with value realization. Our direct partner involvement and efficient processes allow us to respond to these dynamics with the urgency they require. This structural speed also enables us to deliver a level of service intensity and personalization that more layered organizations find difficult to match.

    Agility here is not about cutting corners. It is the natural outcome of a flatter organizational design, empowered decision-makers, and a proprietary operating system purpose-built to optimize transaction timelines. This foundation of responsive execution supports the personalized and cost-effective approach that distinguishes true partnership in M&A advisory.

    5. Comprehensive Network Access and Deal Sourcing

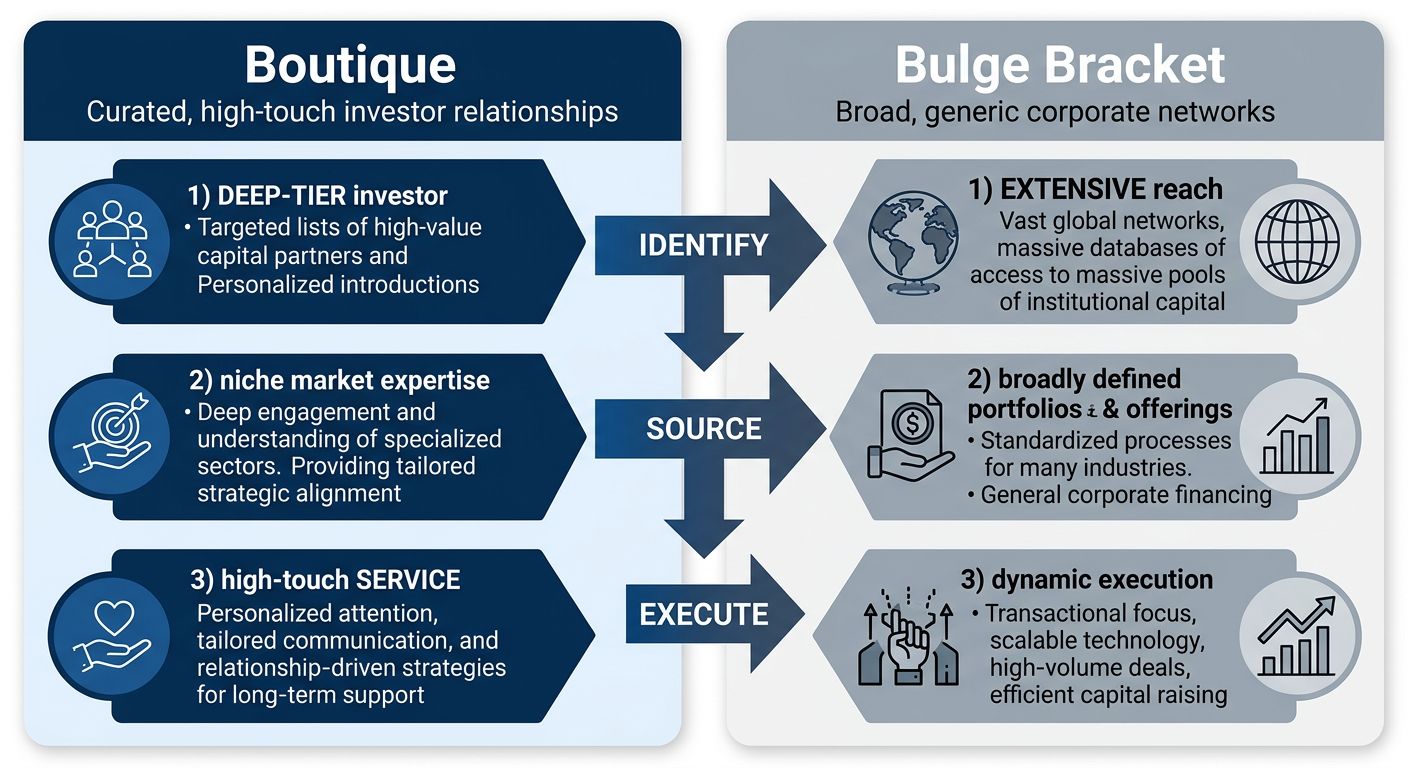
    Beyond our advisory capabilities, the real differentiator in the boutique vs bulge bracket investment banking landscape is the depth of our network. We connect clients with 4,000+ global investors and $15B+ in deployable capital, creating private equity exit opportunities that rival the largest institutions while maintaining the agility of a specialized boutique.

    Infographic comparing boutique M&A firm's high-touch investor network against bulge bracket's broad corporate network with deal sourcing funnel stages.
    Boutique vs. bulge bracket network access comparison at Zaidwood Capital.

    This integrated approach is powered by proprietary tools, including the Sovereign Data Nexus, Precision Catalyst, and Velocity Matrix, which sharpen deal sourcing and analysis. Our $24.4B+ aggregate transaction volume across full-cycle M&A, equity, and debt mandates confirms the scale we deliver. Exclusive access to Deal Vault and our curated Investor Rolodex further extends our partners’ reach. As our internal resources explain, these capabilities streamline the entire capital formation lifecycle, from LP placement and debt structuring to equity advisory.

    Whether you are evaluating private equity exit opportunities or structuring a capital raise, this institutional-grade infrastructure, delivered by a boutique firm, provides a clear advantage over traditional bulge bracket models. Our approach ensures you receive both the scale and the personalization that today’s complex deals demand. We’ll next explore how our fairness opinions and transaction advisory services add another layer of diligence.

    6. Cultural Alignment and Communication

    The choice in boutique vs bulge bracket investment banking extends beyond structure and into the softer, yet equally critical, dimensions of culture and communication. At Zaidwood Capital, we believe that a strong advisory relationship depends on transparency, trust and open dialogue — qualities that are built through consistent interaction rather than brand reputation alone. How a firm communicates directly shapes your experience during what is often the most consequential financial event in a company’s lifecycle.

    Communication style and responsiveness matter because M&A processes move quickly and demand real-time judgment. Boutique firms typically offer direct access to senior partners and a highly personalized cadence, while larger platforms operate through more structured teams and formalized reporting. Neither approach is inherently superior; the right fit depends on how you prefer to receive information, make decisions and manage pressure. Our internal resource on what M&A advisors do outlines how advisors facilitate fit assessments early in the process, helping clients evaluate both technical capability and interpersonal compatibility.

    Finding the right cultural fit also means considering how an advisor handles long-term strategic goals such as private equity exit opportunities or structuring investment banking compensation packages. These conversations require discretion, deep industry knowledge and a relationship grounded in mutual confidence. Full-Cycle M&A mandates succeed when the advisory team aligns with your organization’s values, communication norms and decision-making rhythm — a principle we prioritize through every phase of engagement.

    Streamlining Transactions depends as much on human chemistry as it does on financial engineering. In our experience, the most successful partnerships are those where both sides invest in candid, ongoing communication. The next section outlines practical steps you can take to evaluate and engage an advisor who fits your unique organizational culture.

    Making the Right Choice for Your M&A Needs

    Given the distinct advantages of each model, selecting the right advisor depends on your transaction size, industry focus, and desired level of partner attention. M&A advisors typically provide comprehensive support across buy-side and sell-side representation, valuation, due diligence, and deal negotiation. At Zaidwood Capital, we deliver Full-Cycle M&A and capital advisory that combines the personalized service of a boutique firm with access to over 4,000 institutional investors and $15B+ in deployable capital. Our approach ensures seamless execution from initial due diligence through final closing, backed by $24.4B+ in aggregate transaction volume. We encourage you to assess your specific requirements and book a call for tailored guidance on your M&A journey.

    Resources

  • AI Due Diligence in M&A: Complete Guide for Investors

    AI Due Diligence in M&A: Complete Guide for Investors

    Table of Contents

    The Growing Importance of AI Due Diligence in M&A

    Modern M&A deals generate data on an unprecedented scale, making manual due diligence increasingly insufficient. Integrating AI due diligence into our advisory work enables faster, more thorough analysis of financial, legal, and operational datasets. This technology uncovers risks and insights that traditional methods often miss.

    AI-driven due diligence is becoming a competitive necessity across the industry. At Zaidwood Capital, we incorporate AI-powered analytics into our Full-Cycle M&A and capital advisory process to strengthen decision-making. This approach supplements the expertise of our seasoned team, allowing us to deliver deeper intelligence for our clients. By surfacing critical patterns early, AI in due diligence is emerging as a key differentiator for achieving successful transaction outcomes. We combine machine-assisted analytics with human review to prioritize material issues and support more informed transaction decisions across complex portfolios.

    Before You Begin: Context for AI Due Diligence

    AI due diligence in M&A has rapidly moved from a niche concern to a cornerstone of informed transaction decisions. As AI systems permeate business models—from predictive analytics to autonomous decision-making—you must understand the unique technical and regulatory exposures these assets carry. A comprehensive AI review examines data governance and lineage, model explainability and bias, intellectual property ownership, and compliance with evolving U.S. regulations. Industry frameworks, such as those published by Legistify, underscore the importance of a structured approach to these areas.

    Unlike traditional financial or operational due diligence, AI-specific scrutiny uncovers hidden liabilities such as tainted training data, unlicensed third-party code, or algorithmic discrimination that can derail deal value or invite post-close literature. Because AI due diligence in M&A requires evaluating both technical and business risk, a cross-functional team is essential.

    Zaidwood Capital provides full-cycle mergers and acquisitions advisory that embeds AI due diligence into every phase—from initial screening to post-close integration planning. Our approach integrates these technical findings with commercial and legal analysis, giving you a clear picture of the target’s AI capability and risk profile.

    This guide is for informational purposes only and is not investment advice. In the sections ahead, we break down each pillar of AI due diligence—beginning with data and model risk assessment.

    Assess the Target’s AI Infrastructure

    Effective AI due diligence in M&A requires a meticulous technical review of the target’s AI infrastructure, moving beyond surface-level capabilities to evaluate the core assets underpinning its value. At Zaidwood Capital, our due diligence for AI infrastructure focuses on several critical dimensions. First, we map the compute architecture, determining the split between on-premise and cloud GPU resources and the capacity to scale. Second, we assess the maturity of data pipelines and quality frameworks, as model performance is entirely dependent on clean, well-governed data. Third, our AI due diligence process scrutinizes model governance, version control, and deployment protocols to identify hidden technical debt and key-person dependencies. This structured assessment, drawn from our full-cycle methodology, ensures the stack is resilient and scalable post-merger. By isolating these risks early, we pave the way for a seamless integration and set the stage for the subsequent phase of our review: data privacy and regulatory compliance. This technical foundation is a cornerstone of our broader capital advisory services.

    Evaluate AI Data Assets and Intellectual Property

    Building on AI’s expanding role in deal-making, this section narrows the focus to AI data assets and intellectual property evaluation—two of the most specialized areas of modern M&A. As a boutique M&A advisory firm, we recognize that AI due diligence in M&A must go beyond standard financial reviews to assess data provenance, licensing rights, and the competitive defensibility of proprietary algorithms.

    The complexity of AI asset valuation requires more than conventional checklists. Through our Sovereign Data Nexus and private server infrastructure, we apply an intensive data asset evaluation methodology that surfaces hidden value and flags risks such as regulatory exposure or unclear ownership structures. This approach reflects the IP due diligence discipline we have refined across $24.4 billion in aggregate transaction volume.

    When investors understand the quality and legal standing of a target’s data moat, they are better positioned to structure deals that protect long-term value. Our AI-driven M&A analysis transforms technical assets into clear negotiating inputs—setting a strong foundation for the deal structuring discussion that follows.

    Analyze the AI Technology Stack

    As AI due diligence in M&A transforms how transactions are evaluated, we at Zaidwood Capital focus on the underlying AI technology stack that powers this efficiency. Drawing from industry resources like Legistify, we see a multi-layered framework designed to augment our team’s expertise. This stack integrates machine learning models, natural language processing engines, and automation frameworks to provide a robust analytical backbone.

    The primary layers include a data ingestion module that connects to virtual data rooms and financial databases, a processing core using NLP and anomaly detection for contract and financial review, and a reporting output that surfaces critical risks. A key component is the use of pre-trained language models to summarize lengthy agreements and flag non-standard clauses, dramatically reducing manual review time.

    Crucially, this AI stack is a component of the broader category of legal technology software that supports, but does not supplant, human judgment. Legistify highlights how these technologies improve consistency without compromising the nuanced analysis our deal-makers provide. With the stack defined, we now turn to practical deployment considerations.

    Review AI Risks and Compliance

    As artificial intelligence becomes more embedded in transaction workflows, AI due diligence in M&A has evolved from a niche concern into a core component of deal preparedness. We recognize that AI-powered tools can accelerate target screening and financial analysis, yet they also introduce distinct risks that demand careful scrutiny. Integrating an AI compliance review early helps acquirers avoid post-close surprises that could erode deal value.

    Key risks we evaluate during an AI risk assessment in M&A include:

    • Data privacy vulnerabilities, particularly where models are trained on sensitive customer or employee information that may trigger GDPR or CCPA obligations.
    • Algorithmic bias embedded in valuation or credit-scoring models, which can produce materially skewed financial projections.
    • Regulatory uncertainty as lawmakers refine frameworks governing automated decision-making in financial services.

    According to the American Finance Association, academic research increasingly documents how AI-related financial risks can compound when left unexamined—reinforcing why transaction readiness must account for these exposures. Our approach aligns with that insight, treating AI due diligence in M&A not as a standalone checklist but as an integrated layer within standard operational, legal, and financial reviews. This foundation supports the mitigation strategies the next section explores.

    Assess AI Talent and Organizational Culture

    In any AI due diligence in M&A, human capital analysis is critical. The scarcity of skilled AI professionals directly influences deal valuation and post-merger integration success. Beyond technical skills, organizational culture compatibility is a key predictor of whether the combined entity will thrive.

    We incorporate AI talent and culture assessments into our full-cycle due diligence, recognizing that technology is only as strong as the teams that build and deploy it. Our process evaluates team depth, technical expertise, and cultural alignment alongside a company’s change readiness and leadership dynamics. This comprehensive view, supported by proprietary analytical tools like the Velocity Matrix, ensures our strategic advisory captures the full spectrum of integration risks and opportunities.

    As we progress, the next section will examine the technological and data-related components that must be evaluated alongside human and cultural factors.

    Model AI Value Creation in Valuation

    In the context of AI due diligence in M&A, AI value creation in valuation represents a paradigm shift, enhancing accuracy and the depth of analysis. By integrating machine learning and predictive analytics, we can process vast datasets beyond the scope of traditional discounted cash flow or comparable company models. This fusion enables real-time assimilation of market intelligence, reducing human bias and strengthening our analytical foundation.

    In the scope of AI due diligence in M&A, we employ AI-driven valuation leveraging techniques such as natural language processing to parse qualitative data from earnings calls and news. Academic research published by the American Finance Association in the Journal of Finance provides the theoretical underpinning for these advanced models. Our proprietary Sovereign Data Nexus feeds curated transactional data into our models, delivering nuanced insights that directly inform our next advisory stage, where AI applications extend into deal structuring and execution.

    Integrate AI Due Diligence into Transaction Structure

    Our Full-Cycle M&A and capital advisory process embeds AI due diligence in M&A directly into every phase of the transaction lifecycle. Rather than treating diligence as a disjointed checklist, we apply our proprietary Precision Catalyst and Velocity Matrix frameworks to integrate AI-powered analysis across financial, legal, operational, commercial, IT, and human capital domains from the very start.

    This continuous, AI-driven due diligence accelerates cycle times and reduces manual effort, feeding real-time insights into valuation, risk mitigation, and structuring decisions. By contrast, traditional fragmented approaches often delay critical findings until late-stage review, introducing uncertainty. Our integrated model ensures that every data point — from contract reviews to cultural alignment assessments — informs transaction architecture as it evolves.

    We use AI-driven due diligence to transform raw information into actionable intelligence, enabling more confident and timely deal execution. AI-powered transaction due diligence that lives within the deal flow from assessment to close is what differentiates high-velocity outcomes. This seamless integration of data and decision-making is central to Streamlining Transactions, paving the way for faster, more confident closure.

    Common Pitfalls and Troubleshooting in AI Due Diligence

    While AI accelerates deal evaluation, AI due diligence in M&A introduces hidden risks that demand careful navigation. We help clients recognize these challenges before they undermine transaction integrity.

    • Over-reliance on AI models without human oversight can miss nuanced risks.
    • Inadequate data validation leads to biased or inaccurate outputs, eroding trust.
    • Lack of explainability in AI-driven risk assessments obscures decision logic.
    • Data privacy and security gaps may expose sensitive IP or personal data.

    These pitfalls can derail an M&A process if left unchecked.

    Two-column infographic showing three AI due diligence pitfalls on the left and corresponding troubleshooting actions on the right, connected by arrows, using slate-blue and white colors.

    Common AI due diligence pitfalls and troubleshooting actions infographic.

    According to Dealroom’s analysis of AI-driven due diligence, common pitfalls include data quality and model interpretability challenges. As Zaidwood Capital advises on complex M&A transactions, we note that AI-driven due diligence requires human-in-the-loop validation. We conduct iterative model validation using real M&A data and request vendor documentation to ensure transparency. Aligning AI findings with financial, legal and operational due diligence prevents isolated decision-making.

    Zaidwood Capital’s FAQ on capital formation highlights that AI due diligence often surfaces questions around valuation of proprietary algorithms. By integrating AI insights with traditional due diligence, we deliver a holistic transaction view. The next section explores best practices for AI due diligence execution in today’s deal environment.

    Making AI Due Diligence a Strategic Advantage

    As the M&A landscape accelerates, AI due diligence in M&A has evolved from a competitive differentiator to a foundational capability. Dealroom research indicates that AI-driven due diligence can reduce manual review effort by up to 80%, allowing deal teams to shift focus from data gathering to strategic insight. This speed fundamentally changes the negotiation dynamic.

    By processing vast datasets in minutes, AI-powered due diligence analysis uncovers subtle risk patterns and hidden opportunities in financial, legal, and operational records that human reviewers often miss. The result is deeper, faster deal intelligence, enabling more informed decision-making under tight timelines.

    We integrate these capabilities directly into our Full-Cycle M&A process. Through proprietary infrastructure like our Sovereign Data Nexus and Precision Catalyst, we apply AI to streamline diligence without sacrificing rigor. This creates a strategic advantage — our clients gain the clarity to negotiate with confidence and structure deals more favorably, a theme we will explore further in the sections that follow.

    Resources

  • What Is NAV Financing in Private Equity? A Complete Guide

    What Is NAV Financing in Private Equity? A Complete Guide

    Table of Contents

    NAV financing in private equity represents a sophisticated form of fund-level leverage secured against the net asset value of a private equity fund’s portfolio of companies. Unlike traditional fund-level debt, which may rely on general partner or limited partner guarantees, these asset-backed credit facilities derive their security primarily from the underlying portfolio’s appraised worth. As leaders in Full-Cycle M&A and capital advisory, we at Zaidwood Capital structure these facilities to provide sponsors with a flexible, non-dilutive capital solution that aligns with the fund’s existing asset base while preserving its long-term investment strategy.

    This form of fund-level leverage has gained traction for several common applications. Sponsors frequently use NAV facilities to accelerate distributions to limited partners, avoiding the need for a full asset sale when liquidity is desired. They also serve as a bridge for follow-on investments, enabling a fund to support portfolio company add-on acquisitions between traditional capital calls. The Institutional Limited Partners Association (ILPA) has acknowledged the growing role of fund-level credit, emphasizing in its guidance that any such leverage must be aligned with fiduciary duties and transparent for LP stakeholders.

    Our firm’s capital advisory services encompass the entire lifecycle of NAV financing, from initial eligibility analysis and lender identification to term negotiation and closing. With access to extensive institutional networks and deep expertise in asset-backed structures, we help sponsors navigate the complexities of these loans.

    Fundamentals of NAV Financing and Fund-Level Leverage

    Building on the overview of fund capital strategies, we now examine two core forms of fund-level leverage: subscription lines and NAV financing. Fund-level leverage refers to the strategic use of debt by a fund itself, most commonly through subscription lines or NAV-based credit facilities.

    Comparison: Subscription Lines vs. NAV Financing Facilities

    The following table provides a direct comparison of these two prevalent forms of fund-level leverage:

    FeatureSubscription LineNAV Financing
    PurposeFund capital callsFund distributions and acquisitions
    CollateralUnfunded commitmentsPortfolio company value
    Typical Terms1-2 years3-5 years
    Two-column comparison infographic contrasting subscription line financing with NAV financing terms.

    Comparison of subscription line and NAV financing terms and features for fund-level leverage.

    The Mechanics of NAV Loans: Structure, Growth Drivers, and Key Terms

    Growth Drivers Behind NAV-Based Lending in 2026

    DriverImpact on DemandExample Scenario
    LP Distribution PressureGPs need to return capital without exiting positionsBridge distributions with NAV facility
    Dry Powder OverhangUninvested capital pushes GPs to seek leverageUse NAV to fund follow-on acquisitions
    Regulatory EvolutionBasel IV makes subscription lines less attractiveNAV lines offer off-balance-sheet treatment

    Structuring NAV Loan Facilities: Key Components

    The architecture of a typical NAV financing in private equity facility rests on a few core components. The borrowing base is derived from the aggregate NAV of the portfolio companies. Lenders then apply an advance rate, typically ranging between 10 and 20 percent of that NAV.

    How NAV Financing Creates Value for Private Equity Funds

    The strategic value of NAV financing extends beyond liquidity. By using NAV loans, GPs can smooth fund-level returns and avoid fire sales of portfolio assets during market dislocations. Specialized debt advisory services from firms like Zaidwood Capital help navigate these structures.

    How Private Equity Firms Use NAV Financing for Distributions and Growth

    Use CaseTypical Advance RateCollateral Pool
    LP Distribution10-15% of NAVPortfolio companies
    Follow-On Acquisition20-30% of NAVTarget + existing portfolio

    Distributing Returns to Limited Partners via NAV Facilities

    Rather than selling assets at a suboptimal time, sponsors borrow against the fund’s net asset value and distribute the proceeds to investors.

    Using NAV Financing for Follow-On Acquisitions

    GPs draw on pre-arranged NAV financing facilities to move immediately when an acquisition opportunity emerges.

    Practical Steps to Secure a NAV Loan Agreement

    Securing a NAV facility requires a structured approach. Our corporate advisory services team at Zaidwood Capital negotiates with a network of over 3,000 lenders.

    Advanced Considerations in NAV Financing: Risk Management and Best Practices

    Risk FactorDescriptionMitigation Strategy
    Portfolio OverleverageAdding debt at fund levelMaintain conservative LTV ratios
    Valuation VolatilityNAV fluctuations affect borrowingRegular mark-to-market

    Common Questions About NAV Financing in Private Equity

    What is NAV financing in private equity? It is a form of fund-level leverage secured against a portfolio’s net asset value.

    Maximizing Fund Returns with Strategic NAV Financing

    At Zaidwood Capital, our debt advisory and capital formation capabilities support general partners in designing tailored financing structures.

    Resources

  • Commercial and Industrial Loans: Complete Guide for Businesses

    Table of Contents

    Understanding Commercial and Industrial Loans

    Commercial and industrial loans — commonly referred to as C&I loans — are short-to-medium-term financing solutions designed to fund a company’s daily operations, working capital needs, or capital expenditures. These instruments form a core part of corporate debt financing, and businesses can access them on either a secured or unsecured basis.

    In practice, companies qualify for C&I loans through one of two primary frameworks: asset-based lending or cash flow financing. Asset-based lending centers on the quality of a borrower’s collateral, such as inventory, equipment, or accounts receivable. Cash flow financing, by contrast, emphasizes the strength of historical and projected revenue streams.

    According to Zaidwood Capital’s own advisory resources, institutional investors evaluate applicants using additional metrics — including a detailed business plan, audited financial statements, and multi-year cash flow projections — before matching a company with an appropriate lender. While banks have long dominated this space, a growing pool of institutional investors now provides business loans for commercial purposes, offering a viable alternative for mid-market and growth-stage firms.

    Zaidwood Capital’s Debt Advisory practice helps businesses navigate these two qualification models, acting as a bridge to institutional capital sources. Through its platform, Zaidwood Capital provides global lending services that connect companies with the right C&I lending partners, ensuring a structured and transparent path to financing.

    Commercial and Industrial Loans vs. Other Financing Options

    While the previous section outlined what C&I loans are, this section helps you distinguish them from other common financing products. Understanding the distinctions between commercial and industrial loans, commercial real estate loans, and equipment financing is essential for any business owner evaluating the right capital structure. Each product is designed to meet fundamentally different business needs, from funding day-to-day operations to acquiring major assets. At Zaidwood Capital, we help clients navigate this landscape, leveraging our advisory expertise and access to over 4,000 institutional investors to secure the right financing for their unique situation.

    C&I Loans vs. CRE vs. Equipment Financing
    FeatureCommercial & Industrial LoansCommercial Real Estate LoansEquipment Financing
    Primary Use CaseWorking capital, inventory, operational expensesAcquiring, developing, or refinancing real propertyPurchasing machinery, vehicles, or technology
    Collateral TypeReceivables, inventory, equipmentReal estate asset being financedEquipment being acquired
    Repayment TermShort to medium term (1–5 years)Long term (10–30 years)Medium term (3–10 years)
    Interest Rate TypeFixed or floating, tied to working capital cyclesFixed or floating, typically lower spreadsFixed or floating, often with equipment retention clauses

    The primary use case immediately highlights the distinct purpose for each loan. Commercial and industrial loans are the go-to solution for fueling organic growth, covering payroll, and managing seasonal inventory swings. In contrast, commercial real estate loans are structured for the long-term acquisition or development of property, reflecting the extended lifespan and stable value of real estate assets.

    When we look at collateral, C&I loans typically rely on a company’s assets like accounts receivable, inventory, and existing equipment. This differs significantly from CRE loans, where the property itself serves as collateral, and equipment financing, where the newly purchased machinery, vehicles, or technology secures the debt. This collateral structure directly influences the repayment term, where C&I loans often operate with shorter 1-5 year horizons aligned with operational cycles, whereas CRE loans can amortize over much longer periods of 10 to 30 years.

    These differences underscore why there is no single “best” option—only the right instrument for a specific business objective. Our advisory process, highlighted on our Raise platform, involves a detailed review of a company’s financial standing, cash flow projections, and strategic goals to match you with appropriate lending structures.

    Comparison of C&I loans, commercial real estate loans, and equipment financing options.

    Understanding these differences is the first step. The next section will walk you through the qualification process for a C&I loan. We encourage you to review the details carefully, and when you’re ready to explore how a tailored debt solution can support your growth, you can Book A Call with our team.

    This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to transact. This is not investment advice; please consult your legal, tax, and financial advisors before making decisions.

    Collateral, Eligibility, and Loan Structuring for C&I Lending

    Beyond the basic loan purpose, successful C&I financing depends on three pillars: collateral, borrower eligibility, and loan structure. For businesses seeking commercial and industrial loans, understanding how lenders assess each of these areas is essential to securing terms that align with operational needs and growth goals. Our advisory team at Zaidwood Capital helps companies navigate these criteria, drawing on institutional requirements to build a strong lending case.

    Types of Collateral in C&I Lending

    The collateral securing the facility is a primary driver of advance rates and overall credit appetite. Lenders evaluate asset quality, liquidity, and valuation risk to determine how much they are willing to advance against each class. The table below summarizes the most common collateral types accepted in C&I loans, alongside their typical advance ranges and how institutional lenders generally view each asset class.

    Accounts receivable financing consistently receives the most favorable treatment, with advance rates reaching 70 to 90 percent. Because these assets convert to cash relatively quickly, they represent the most liquid form of collateral in C&I lending. Inventory, by contrast, carries more uncertainty. Advance rates of 30 to 60 percent reflect obsolescence risk, shelf-life concerns, and the challenge of liquidation if a borrower defaults. Equipment and machinery can provide solid collateral support at 50 to 80 percent of appraised value, provided the assets are well-maintained and have a clear secondary market. Real estate, while strong, is often carved out for commercial real estate-specific products rather than traditional C&I lines.

    Lender Eligibility Criteria

    Institutional lenders apply a consistent set of financial metrics to gauge a borrower’s ability to service C&I obligations. Per Zaidwood Capital’s guidance on asset-based lending, a debt-service coverage ratio of 1.25x or higher is a typical baseline. This means the company’s operating cash flow should cover all scheduled debt payments with a comfortable margin. Lenders also examine liquidity through the current ratio, generally expecting it to remain above 1.0x, though stronger ratios improve negotiating power.

    Beyond ratios, the documentation package is critical. Institutional investors require audited financial statements covering at least the last three fiscal years, detailed accounts receivable aging reports, and third-party inventory or equipment appraisals. The U.S. Securities and Exchange Commission’s reporting standards underpin many of these requirements, ensuring that the financial information lenders rely on meets a recognized threshold of accuracy. Our role is to assemble and present this package in a format that aligns with how institutional credit committees evaluate risk.

    Loan Structuring: Rates and Terms

    Once collateral and eligibility are confirmed, the loan structure defines how the capital is priced and repaid. Interest rate choice is often the first decision point. Variable-rate loans are typically tied to the Secured Overnight Financing Rate, or SOFR, plus a spread that reflects the borrower’s credit profile and transaction size. While this structure can offer lower initial costs, payments fluctuate with market conditions. Fixed-rate loans carry a premium for the interest-rate certainty they provide, making them attractive for companies that prioritize predictable budgeting over potential savings in a declining rate environment.

    Repayment terms can be just as important as the rate itself. For businesses with uneven revenue cycles, seasonal or deferred payment structures are often built into the agreement. For capital-intensive purchases, equipment financing can be structured with seasonal or deferred payment plans, linking directly to our detailed FAQ. This flexibility allows borrowers to match debt service to cash generation, reducing strain during off-peak periods. With the collateral and structure defined, the next step is preparing a complete application package. To discuss how these terms can be tailored to your specific situation, we invite you to Book A Call for a custom quote.

    Strategic Uses of C&I Loans: Working Capital and Equipment Financing in Practice

    Now that we understand the broad benefits of C&I loans, let’s explore two of their most strategic applications in practice. Commercial and industrial loans provide the structured capital that businesses need for specific operational and growth objectives, from managing day-to-day cash flow to acquiring essential equipment. At Zaidwood Capital, our Debt Advisory team helps clients navigate these applications, structuring solutions that align with both immediate needs and long-term business plans.

    The following table matches common business needs to the appropriate loan structure, documentation requirements, and typical use cases.

    Common Collateral Types for C&I Loans
    Collateral TypeDescriptionTypical Advance RateLender Preference
    Accounts ReceivableInvoices from creditworthy customers70%–90%Highly preferred due to liquidity
    InventoryRaw materials, WIP, finished goods30%–60%Moderate; depends on obsolescence risk
    Equipment & MachineryFixed assets with appraised value50%–80%Good; stable collateral if well-maintained
    Real EstateCommercial or industrial property60%–75%Strong, but often used in CRE-specific products

    These three structures cover the most frequent strategic uses of C&I loans we encounter in our advisory work. Selecting the right one depends on your specific objective, the collateral available, and the documentation you can provide to support the request.

    Financing Working Capital with C&I Loans

    For businesses facing seasonal demand fluctuations or uneven cash flow cycles, working capital financing through an asset-based revolving line of credit offers a practical solution. This structure uses your company’s accounts receivable aging and inventory reports as collateral, creating a borrowing base that increases as your operational assets grow. Rather than waiting for customer payments to arrive, you draw against the value of outstanding invoices and on-hand inventory to cover immediate needs.

    Qualifying for this type of facility requires clear cash flow projections that demonstrate your ability to service the debt across different points in your business cycle. Lenders reviewing your application will want to see consistent patterns in your A/R aging, turnover rates on inventory, and realistic forward-looking projections that account for both peak and off-peak periods.

    A real-world example helps illustrate how this works in practice. Consider a wholesale distributor in Baltimore that experiences a predictable seasonal inventory buildup ahead of the summer months. To purchase stock and cover operating expenses during the slower winter period, the business establishes an asset-based line of credit secured by its receivables and inventory. This structure provides the liquidity needed to make supplier payments on time without depleting cash reserves, and the credit line contracts as receivables are collected, keeping the cost of capital aligned with actual usage.

    All documentation and loan structuring must comply with relevant securities regulation and investor protection standards where applicable. For the working capital example above, the key documents needed include:

    • Accounts receivable aging reports showing outstanding invoice balances and due dates
    • Inventory reports detailing stock levels, valuation, and turnover rates
    • Cash flow projections covering seasonal peaks and troughs

    Equipment Financing: A Practical Application

    Commercial and industrial loans also provide a structured path for acquiring machinery, vehicles, or IT infrastructure without depleting working capital. Equipment financing typically takes the form of a term loan secured by the purchased asset itself, meaning the equipment serves as collateral for the loan. This approach preserves liquidity while allowing the business to put the new asset to productive use immediately. According to internal resources from Zaidwood Capital, the process follows a clear, step-by-step sequence.

    Start by obtaining a professional equipment appraisal to establish the fair market value of the machinery you want to purchase. Next, secure a detailed invoice or purchase order from the vendor that specifies the equipment, pricing, and delivery terms. With these documents in hand, our Debt Advisory team can structure the term loan to match the useful life of the equipment, with repayment terms that align to your projected cash flow from using the asset.

    Businesses with seasonal revenue patterns can also benefit from structured flexibility in their equipment financing. In Baltimore, a company that generates the majority of its revenue during the summer tourism season can arrange a payment schedule with higher installments during peak months and reduced or skipped payments in the winter. This alignment ensures that debt service never outpaces available cash flow. Documentation best practices for equipment financing applications include:

    • Equipment appraisal establishing fair market value
    • Detailed invoice or purchase order from the vendor
    • Two to three years of business financial statements and tax returns
    • Business plan or statement outlining the intended use of the financed equipment

    With these structured applications in mind, we can now examine how businesses and advisors proceed through the full lifecycle of a C&I loan transaction.

    Optimizing Financial Health with Commercial and Industrial Loans

    A core component of debt advisory is helping companies optimize their financial health through commercial and industrial loans, a category of short-to-medium-term financing designed to fund day-to-day operations. C&I loans can be used for various purposes, from purchasing inventory and machinery to covering working capital needs. By strategically deploying these loans, businesses can maintain momentum without sacrificing equity. We work with our clients to structure C&I loans that enhance liquidity, building a stronger foundation for scalable growth.

    C&I loans are often structured as asset-based lending, secured by a company’s receivables or inventory. This approach unlocks capital tied up in current assets, improving cash flow without ownership dilution. For businesses with strong recurring revenue, cash flow financing serves as a complementary tool, allowing them to borrow based on their ability to generate predictable revenue streams. Institutional investors in our network, which comprises over 4,000 entities, can offer flexible terms that may not be available through traditional banks. According to our qualification framework, lenders evaluate collateral quality, EBITDA trends, and comprehensive business plans during the due diligence process.

    Our debt advisory team aligns each client’s C&I loan structure with its specific growth stage and operational cycles. By assessing financial statements, projected cash flows, and expansion plans, we match companies with institutional lenders whose investment criteria align with their sector and deal size. This tailored approach ensures that the resulting capital structure supports working capital efficiency and positions the business for future capital raises. Our team has successfully raised over $800 million in financing solutions, leveraging access to more than $5 billion in deployable debt.

    Proper structuring of C&I loans can strengthen a company’s balance sheet and credit profile, while adherence to financial industry regulation and investor education standards helps ensure transparency in C&I loan agreements. We encourage businesses to discuss their C&I loan structuring needs with our debt advisory team.

    Now let’s address some common questions businesses have about commercial and industrial loans. The regulatory landscape is shaped significantly by federal oversight, with the FTC consumer and business protection division playing a key role. Our team emphasizes that awareness of these protections is a fundamental step in responsible commercial and industrial financing.

    What is the FTC’s role in C&I lending?

    The Federal Trade Commission enforces truth-in-lending requirements and prohibits unfair or deceptive acts against businesses. This oversight creates a baseline of borrower protection for C&I loans, ensuring lenders provide transparent terms and cannot engage in predatory practices.

    How can businesses evaluate lender credibility?

    Business owners should verify lender registrations, review financing terms carefully, and consult the FTC’s business guidance on lending to identify red flags. We advise our clients to avoid any lender unwilling to disclose clear, written documentation.

    What should borrowers know about collateral and guarantees?

    Many commercial and industrial loans require collateral or personal guarantees. The FTC’s truth-in-lending standards mandate that these obligations be clearly disclosed upfront, helping borrowers make informed decisions without hidden risk.

    For more detailed guidance on securing C&I financing, our team can help.

    Partnering with a Capital Advisory Firm for C&I Financing

    Navigating the complexities of commercial and industrial loans demands more than a strong balance sheet—it requires a partner who understands institutional lending at scale. Zaidwood Capital’s debt advisory team evaluates a company’s financial position, cash flow profile, and collateral base to structure tailored C&I financing solutions. By leveraging a network of over 4,000 investors and more than $15 billion in deployable capital, we streamline the transaction process and connect businesses to the right capital partners. Through our Full-Cycle M&A and capital advisory approach, we guide clients from initial due diligence through closing, ensuring every phase moves with precision.

    Securities are offered through Finalis Securities LLC, a registered broker-dealer. Zaidwood Capital LLC is not a registered broker-dealer, and no content herein constitutes an offer or solicitation of securities. Investments involve risk, and past performance does not guarantee future outcomes.

    Resources

  • Best Asset Based Lending for 2026: Top Companies Compared

    Best Asset Based Lending for 2026: Top Companies Compared

    Table of Contents

    Asset-Based Lending as a Strategic Financing Tool

    Beyond traditional cash-flow loans, asset-based lending offers a strategic alternative for companies seeking flexible, secured financing against their balance-sheet assets. The U.S. Securities and Exchange Commission defines collateral as an asset a lender accepts as security for a loan, including real estate, equipment, inventory, and accounts receivable—precisely the assets that underpin asset-based lending structures.

    Through asset-based lending, businesses can often achieve higher leverage than unsecured debt and benefit from lower interest rates because the loan is backed by tangible collateral. This approach is especially valuable for companies with strong asset bases but uneven earnings, as the financing capacity is tied to asset values rather than cash-flow metrics alone.

    Qualifying typically requires a disciplined institutional process. As outlined in our FAQ, investors commonly look for collateral coverage ratios—often 1.5x to 2.0x advance rates—together with audited historical financials, minimum EBITDA thresholds, and thorough asset-quality audits. These benchmarks help our team identify the right institutional match from a network of over 4,000 investors, including banks, credit funds, and specialty finance firms.

    Unlike cash-flow financing, which depends heavily on EBITDA, asset-based lending unlocks liquidity directly from receivables, inventory, equipment, or real estate. Many companies use both structures concurrently, blending them to optimize cost of capital and funding flexibility. Through our global lending services, we connect clients with institutional investors specializing in asset-based lending and other secured debt structures.

    Asset-based lending can fund acquisitions, bridge equity gaps, or provide seasonal working capital—but outcomes are not guaranteed and depend on asset quality and deal structure. While many companies qualify, each transaction is subject to investor approval and due diligence.

    In the following section, we explore how ABL can be structured alongside equity financing to maximize transaction efficiency.

    This is not an offer or solicitation; consult your advisor.

    Understanding Asset-Based Lending Fundamentals

    Having defined asset-based lending, let us examine its core mechanics and how it compares with traditional financing. Asset based lending is a secured financing facility where the borrowing amount is determined by the value of specific pledged assets rather than primarily by cash flow or credit history. This type of secured lending relies on four main asset classes: accounts receivable, inventory, equipment, and real estate, each valued with distinct advance rates that reflect their liquidity and liquidation potential.

    The following table highlights the key differences between asset-based lending and a traditional bank line of credit.

    Asset-Based Lending vs. Traditional Bank Line of Credit
    DimensionAsset-Based LendingTraditional Bank Line of Credit
    Collateral RequirementSecured by specific assets (AR, inventory, equipment, real estate)Often unsecured or blanket lien; may require personal guarantees
    Underwriting FocusAsset quality and liquidation value; less emphasis on cash flowCash flow, credit history, and overall financial health
    Funding SpeedTypically 2–4 weeks; faster for revolving facilitiesCan take 4–8 weeks or longer for approval and funding
    FlexibilityHighly flexible; borrowing base adjusts with asset levelsFixed credit limit; less responsive to asset fluctuations
    CovenantsFewer financial covenants; focus on asset reportingStrict financial covenants (debt service coverage, leverage ratios)

    An ABL facility emphasizes the quality and liquidation value of collateral, with fewer financial covenants and a borrowing base that flexes alongside asset levels. For businesses with strong collateral but variable cash flow, such as manufacturers, wholesalers, or distributors, secured asset lending often provides faster access to capital and greater responsiveness to seasonal or growth-driven asset fluctuations.

    Comparison infographic of asset-based lending versus traditional bank line of credit highlighting differences in security, funding timeline, and flexibility
    Comparing asset-based lending and traditional bank line of credit

    Underwriting in asset-backed financing concentrates on the quality, liquidity, and liquidation value of the pledged collateral. Advance rates vary by asset class, with accounts receivable typically commanding higher advance rates than inventory or equipment. This approach shifts reporting toward asset monitoring rather than strict debt service coverage ratios, making ABL accessible to companies that may not meet conventional bank criteria. For a broader perspective on financing options, our coverage of global lending services alternatives provides key considerations for borrowers comparing ABL with other structures.

    Deep Dive into Asset-Based Lending Structures and Collateral Types

    To understand how asset based lending works, it is essential to examine the four primary collateral types that underpin every ABL structure. Each asset class carries distinct risk profiles, valuation methodologies, and advance rate ranges that directly influence the amount of capital a business can access and the speed at which funds become available.

    Primary Collateral Categories and Their Characteristics

    In asset based lending, collateral types determine both eligibility and borrowing capacity. The U.S. Securities and Exchange Commission defines collateral broadly as assets pledged to secure a loan, and within ABL structures, lenders focus on four principal categories based on their liquidity and ease of valuation.

    Accounts receivable represent the most liquid and preferred collateral class. Lenders evaluate AR through aging reports that identify overdue invoices, dilution analysis that measures returns and allowances against gross sales, and concentration limits that cap exposure to any single debtor. Because receivables convert to cash through normal collection cycles, they carry the highest advance rates and fastest funding timelines.

    Inventory serves as a common but more complex collateral type. Valuation requires third-party appraisal that accounts for obsolescence risk, seasonal demand patterns, and turnover velocity. Finished goods ready for sale command stronger valuations than raw materials or work-in-progress, which have limited liquidation markets.

    Equipment and real estate round out the primary categories, with valuations based on orderly liquidation value and professional appraisal, respectively. Equipment financing benchmarks indicate ABL structures typically extend 50 to 80 percent of orderly liquidation value depending on age, condition, and secondary market demand. Real estate requires the most extensive due diligence, including title searches and environmental assessments.

    Loan-to-Value Determinants and Advance Rate Mechanics

    Loan-to-value ratios in asset based lending emerge from a lender’s assessment of advance rates, eligibility criteria, and concentration limits applied to each asset class. The LTV is not a fixed percentage but a calculated figure reflecting the lender’s confidence in recovering principal through liquidation of the pledged collateral.

    Collateral Types and Advance Rates in Asset-Based Lending
    Asset TypeTypical Advance RateValuation MethodLiquidity / Speed of Funding
    Accounts Receivable70–90% of eligible ARAging reports, dilution analysis, concentration limitsFast; funds available within days of invoice submission
    Inventory40–60% of appraised valueAppraisal by third-party; considers obsolescence and turnoverModerate; requires field exam and appraisal
    Equipment50–80% of orderly liquidation valueAppraisal based on age, condition, and secondary marketModerate; appraisal and documentation needed
    Real Estate60–75% of appraised valueProfessional appraisal, title search, environmental assessmentSlower; due diligence and legal process required

    Advance rates represent the percentage of an asset’s appraised or eligible value that a lender will fund. Accounts receivable command the highest rates at 70 to 90 percent of eligible receivables because they self-liquidate through customer payments. Inventory advance rates sit lower at 40 to 60 percent, reflecting the inherent risk of physical goods degradation and market fluctuation.

    Funding Speed and the Asset-Based Lending Process

    The timeline from application to funding in asset based lending varies considerably by asset type and the intensity of due diligence required. Borrowers who prepare documentation thoroughly and understand lender expectations can materially compress the timeline.

    The ABL due diligence process typically begins with a field exam, where auditors physically inspect assets, verify accounting systems, and test the accuracy of borrowing base reports. For AR-heavy structures, this involves confirming invoice validity and analyzing customer payment patterns. Businesses exploring global lending services alternatives can compare ABL timelines against other capital sources to determine the optimal structure.

    Practical Guide to Securing Asset-Based Lending for Growth and Acquisitions

    Now that you understand the fundamental structure and purpose of asset-based lending, it’s time to explore a practical guide for securing this flexible financing tool. For companies with strong balance sheets but uneven cash flow, asset-based lending provides a tactical pathway to fund growth initiatives and execute acquisitions.

    Preparing Your Business for an Asset-Based Lending Application

    • Compile Detailed Financial Statements: Gather at least three years of audited financial statements, including balance sheets, income statements, and cash flow reports.
    • Prepare Precise Asset Schedules: Create comprehensive, up-to-date schedules for all assets that will serve as collateral, including accounts receivable aging reports and inventory listings.
    • Assemble Due Diligence Materials: Organize corporate documents, tax returns, customer and supplier contracts, and legal records.

    Using Asset-Based Lending for Acquisitions and Growth

    Asset-based lending is a powerful engine for mergers and acquisitions, offering flexible structures that traditional cash-flow loans often cannot match. We consistently see clients use ABL facilities in three principal ways during M&A: Leveraged Buyouts, Post-Acquisition Working Capital, and Bridge Financing.

    Advantages of Asset-Based Lending for Corporate Growth

    For asset-rich companies, the strategic advantages of asset-based lending are significant and multifaceted. The structure is designed to support rapid scaling and operational flexibility, which is why it is often recommended for companies navigating high-growth phases.

    Asset-Based Lending vs. Alternative Debt Structures
    Debt StructureCollateral FocusTypical Cost (Interest + Fees)Best For
    Asset-Based LendingSpecific assets (AR, inventory, equipment, real estate)LIBOR/SOFR + 3–6%Working capital, growth, acquisitions with asset-rich borrowers
    Cash-Flow LoanGeneral business assets / blanket lienPrime + 2–5%Established companies with strong cash flow and credit history
    Mezzanine DebtSubordinated; often unsecured with equity warrants12–20% (including equity upside)Growth capital, acquisitions, buyouts for mid-market companies
    Equipment FinancingSpecific equipment being purchased6–12%Capital-intensive businesses acquiring machinery or vehicles

    This website is for informational purposes only and is not an offer, solicitation, or commitment to transact. It is not investment advice. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Advanced Considerations in Asset-Based Lending for M&A and Complex Transactions

    While ABL is versatile for general purposes, its application becomes more nuanced in M&A and complex deals. In an acquisition context, asset based lending serves as a senior secured facility, often structured to support working capital, bridge financing, or leveraged buyout (LBO) debt.

    Asset-Based Lending vs. Mezzanine Debt vs. Equity for M&A
    Financing TypeCost RangeDilution / ControlBest Use in M&A
    Asset-Based LendingSOFR + 3–6%No dilution; lender has lien on assetsSenior secured facility for working capital, bridge financing, or LBO debt
    Mezzanine Debt12–20% (including warrants)Minimal dilution; warrants may give equity upsideSubordinated layer to fill gap between senior debt and equity
    Equity Financing15–30%+ expected returnSignificant dilution; investors gain ownership and control rightsGrowth equity, buyouts, or when debt capacity is limited

    Frequently Asked Questions About Asset-Based Lending

    Q: What is asset based lending? Asset based lending is a secured financing structure where a business pledges balance-sheet assets such as accounts receivable, inventory, or equipment as collateral. Unlike traditional cash-flow lending that emphasizes credit scores and profitability, ABL focuses on the liquidation value of the pledged assets.

    Q: How does collateral work in an asset-based loan? Collateral is property offered to secure a loan—the U.S. Securities and Exchange Commission defines it as something a lender can seize if the borrower defaults. In asset-based lending, lenders first appraise the pledged assets and then set a borrowing base that reflects their realizable market value.

    Q: What are typical advance rates for asset-based loans? Advance rates vary by asset quality, but receivables commonly qualify for 70–85 percent and inventory for 50–60 percent of the appraised value.

    Leveraging Asset-Based Lending with Zaidwood Capital’s Debt Advisory Expertise

    Asset based lending uses a company’s receivables, inventory, and equipment as collateral, unlocking more flexible capital than unsecured debt. Our debt advisory team structures ABL facilities around your cash flow and collateral profile, connecting you to over 4,000 institutional investors and more than $15 billion in deployable capital. We engineer tailored terms that deliver higher leverage and greater flexibility than conventional bank loans—especially for growing or cyclical businesses.

    Resources

  • Supply Chain Management: Complete Guide to Visibility and Integration

    Table of Contents

    Supply Chain Management as a Strategic Asset

    Supply chain management is the coordinated network of activities that moves materials from raw sourcing all the way to final delivery — and when executed well, it directly reduces operating costs while strengthening customer satisfaction. In our work with growth-stage manufacturers, we see that organizations with mature SCM capabilities consistently respond faster to demand shifts and maintain healthier working capital positions.

    Core Concepts of Supply Chain Management

    To understand how SCM drives value, we first explore its foundational components.

    Supply Chain Visibility

    At the heart of modern supply chain management is visibility: the real-time tracking of inventory positions, shipment milestones, and production status across every node of the chain. When decision-makers can monitor material flow as it happens, they move from reactive to proactive operations. Strong supply chain visibility reduces lead-time uncertainty, flags supplier disruptions before they cascade, and gives procurement teams the intelligence to negotiate from fact rather than assumption.

    Supply Chain Integration

    Equally critical is supply chain integration, which synchronizes data across enterprise resource planning (ERP) systems, warehouse management systems (WMS), and supplier platforms. Without integration, even the best demand forecasts break down when execution data stays locked inside department silos. Connected architectures allow planning, purchasing, and logistics teams to share a single version of the truth, eliminating the reconciliation delays that slow decision-making in many mid-market manufacturing environments.

    Software Categories Supporting SCM

    Organizations approaching supply chain digitization encounter three broad software categories. Basic tracking solutions deliver real-time shipment visibility through standalone portals or APIs, while integration middleware layers data synchronization between core business systems and supplier networks. At the enterprise end, full-suite SCM platforms wrap planning, execution, and analytics into one end-to-end supply chain environment. For organizations embarking on supply chain digitization, partnering with a top manufacturing consulting firm can provide the necessary expertise. Our internal research, which catalogues leading manufacturing consultants, confirms that external advisors frequently accelerate software selection and cut implementation risk.

    The table below highlights key differences between common SCM software categories.

    Comparison of Supply Chain Management Software Categories
    FeatureBasic TrackingIntegration MiddlewareFull-Suite SCM
    Core FunctionalityReal-time shipment trackingData synchronization between ERP, WMS, and suppliersEnd-to-end planning, execution, and analytics
    Inventory VisibilityLimited to inbound/outbound statusMulti-location inventory snapshotsReal-time, multi-echelon visibility
    Implementation ComplexityLow – standalone API or portalMedium – requires IT coordinationHigh – enterprise-wide deployment

    Advancing Supply Chain Visibility and Integration

    While supply chain finance can unlock working capital, full value creation depends on advancing visibility and integration across the supply chain. In the context of full-cycle M&A and capital advisory, understanding how target companies manage these operational dimensions is essential for accurate valuation and synergy modeling.

    Understanding Supply Chain Visibility

    Supply chain visibility is the capability to track physical goods, information flows, and financial transactions across every tier of a supply network in real time. In M&A due diligence, this transparency is critical because it allows deal teams to detect disruptions, supplier concentration, and working capital inefficiencies before they become post-closing liabilities. Without adequate visibility, material risks—such as a Tier-2 supplier insolvency or logistics bottleneck—can remain concealed behind aggregated procurement reports.

    Supply Chain Integration in M&A Due Diligence

    Supply chain integration involves connecting suppliers, systems, and processes to create a unified operating model that drives working capital efficiency and post-merger synergy realization. In a transaction context, the depth of integration directly impacts valuation because optimized supplier collaboration and streamlined data flows reduce the cash-to-cash cycle—a key input in discounted cash flow analysis.

    Supply Chain Integration States in Due Diligence
    AspectPre-Integration StatePost-Integration State
    Data SharingManual spreadsheets and email updatesReal-time APIs and shared dashboards
    Supplier CollaborationReactive order managementJoint demand forecasting and VMI
    Risk VisibilityIsolated silos, delayed alertsEnd-to-end traceability and predictive alerts
    Working Capital ImpactHigher safety stock, longer cash-to-cash cyclesOptimized inventory, faster receivable turnover

    The transformation from manual data sharing to integrated systems directly affects transaction pricing. For example, when a target company operates with higher safety stock and extended cash-to-cash cycles, the acquiring entity must discount its valuation to account for trapped working capital. Conversely, a post-integration state with optimized inventory and faster receivable turnover—often achieved through supply chain finance programs—can justify a premium valuation. Acquirers must consult SEC investor resources to ensure that material supply chain risks and integration plans are properly disclosed in regulatory filings.

    How to Improve Supply Chain Management Skills

    Developing robust supply chain management skills requires a blend of formal certification, cross-functional fluency, and data literacy. For professionals conducting due diligence or integration planning, the Certified Supply Chain Professional (CSCP) designation provides a structured foundation in end-to-end supply chain operations and risk management frameworks. Proficiency in data analytics platforms such as Power BI and Tableau empowers teams to build real-time dashboards that monitor supplier health, inventory turns, and lead-time variability. For a tailored assessment of your target’s supply chain readiness, Book A Call with our advisory team.

    Building a Career in Supply Chain Management

    Understanding how supply chain financing works is valuable, but building a career in supply chain management requires deliberate steps. We at Zaidwood Capital have observed that the professionals who accelerate their career trajectories are those who combine operational expertise with financial acumen.

    How to Start a Career in Supply Chain Management

    Entering the supply chain profession begins with a strong educational foundation. A bachelor’s degree in business, supply chain management, or data analytics provides the essential knowledge base for entry-level roles. Earning credentials such as the Certified Supply Chain Professional (CSCP) from ASCM or the Certified Professional in Supply Management (CPSM) from ISM signals to employers that you possess validated expertise.

    Why Supply Chain Management Is a Good Career Path

    Supply chain management offers exceptional career prospects driven by strong demand and competitive compensation. The Bureau of Labor Statistics projects 30% growth for logisticians through 2030, far outpacing the average for all occupations. Professionals who understand supply chain financing are increasingly valued for their ability to manage working capital and strengthen supplier relationships.

    Learning Pathways for Supply Chain Professionals

    Supply chain professionals have multiple avenues to build and deepen their expertise. Formal degree programs—Bachelor of Business Administration or Master of Business Administration with supply chain concentrations—provide structured academic foundations. For those seeking flexibility, online platforms like Coursera, edX, and LinkedIn Learning offer courses in supply chain visibility tools and integration techniques.

    Supply Chain Finance and Capital Strategy

    For companies operating in supply chain management, aligning financial strategy with operational goals is essential for sustainable growth. Supply chain finance encompasses solutions like reverse factoring and dynamic discounting that improve working capital while strengthening supplier relationships.

    Working Capital Optimization

    Optimizing working capital begins with understanding the cash conversion cycle and identifying structural inefficiencies. Supply chain finance programs allow buyers to extend payment terms without penalizing suppliers, effectively freeing trapped cash for reinvestment.

    Frequently Asked Questions About Supply Chain Management

    What is supply chain integration? We see supply chain integration as the process of connecting systems and workflows across organizations. This alignment supports smoother post-merger consolidation and unlocks cost synergies essential to Full-Cycle M&A and capital advisory.

    How does supply chain visibility affect M&A due diligence? Investors must assess supplier risk, inventory transparency, and regulatory compliance. The U.S. Securities and Exchange Commission requires public companies to disclose material supply chain risks, making visibility central to thorough due diligence.

    Transforming Supply Chain Management into Strategic Value

    While many organizations still view supply chain management as a narrow cost-containment function, forward-thinking leaders treat it as a driver of durable competitive advantage. In M&A and capital transactions, supply chain visibility reveals hidden risks and operational upside that financial statements alone often miss. Similarly, intentional supply chain integration—both internally and across entities—unlocks the synergies that define successful post-merger outcomes.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis. Investments involve risk; investors may lose all or part of their investment. Past performance does not guarantee future results.

    Resources