Category: Debt Advisory

  • Direct Lending Market Comparison: Top Private Capital Strategies

    Direct Lending Market Comparison: Top Private Capital Strategies

    Table of Contents

    Direct Lending Market: A Competitive Capital Source for Middle-Market Companies

    Middle-market firms facing rigid bank underwriting increasingly turn to the direct lending market for speed and flexibility. Unlike traditional bank loans, direct lending—provided by non-bank institutions—offers faster execution, covenant-light structures, and reduced regulatory hurdles. Our firm’s research confirms that borrowers value this private credit market for its ability to close deals swiftly.

    Current U.S. direct lending spreads remain competitive, attracting middle-market companies away from syndicated loans. Zaidwood Capital’s market intelligence shows direct lending integrates with broader private capital raising strategies, including GP-led secondary transactions that provide liquidity. Companies pursuing emerging markets M&A also benefit from direct lending’s speed and flexibility. In the following section, we outline how our team structures these customized solutions.

    1. Competitive Interest Rate Spreads

    In the U.S. direct lending market, borrowers seek competitive pricing amid tightening spreads. According to Zaidwood Capital’s market analysis, current all-in yields reflect the following typical ranges in basis points (bps):

    • Senior secured direct loans for mid-market transactions: SOFR + 400–600 bps.
    • Unitranche structures for high-quality sponsors: SOFR + 350–500 bps, while smaller or riskier borrowers may see spreads of +600–800 bps.
    • Second-lien or mezzanine tranches: SOFR + 800–1,200 bps.

    Spread compression over the past year has been driven by heightened competition among direct lenders, a trend we also observe in private capital raising strategies and GP-led secondary transactions. Deal size, credit quality, and leverage shape pricing, and our network enables us to secure competitive terms in the U.S. direct lending market. While spreads remain competitive, sponsors pursuing emerging markets M&A often face wider spreads due to higher perceived risk. These benchmarks directly influence the cost of capital across deal structures, a dynamic we navigate for every mandate.

    2. Flexible Financing Structures

    Beyond standard capital raising, we offer flexible financing structures that leverage the direct lending market to deliver faster execution and custom terms compared to traditional bank loans. As our internal FAQ on direct lending explains, this alternative to bank financing bridges gaps where conventional credit often falls short, especially for mid-market transactions.

    Our tailored solutions encompass mezzanine debt, venture debt, equipment financing, and asset-based lending. Each instrument is custom-quoted to the client’s specific transaction, ensuring the right capital structure for growth, acquisitions, or liquidity. By operating in the direct lending market, we can craft flexible covenants and amortization schedules that align with your cash-flow profile. These structures support private capital raising strategies that go beyond one-size-fits-all bank terms.
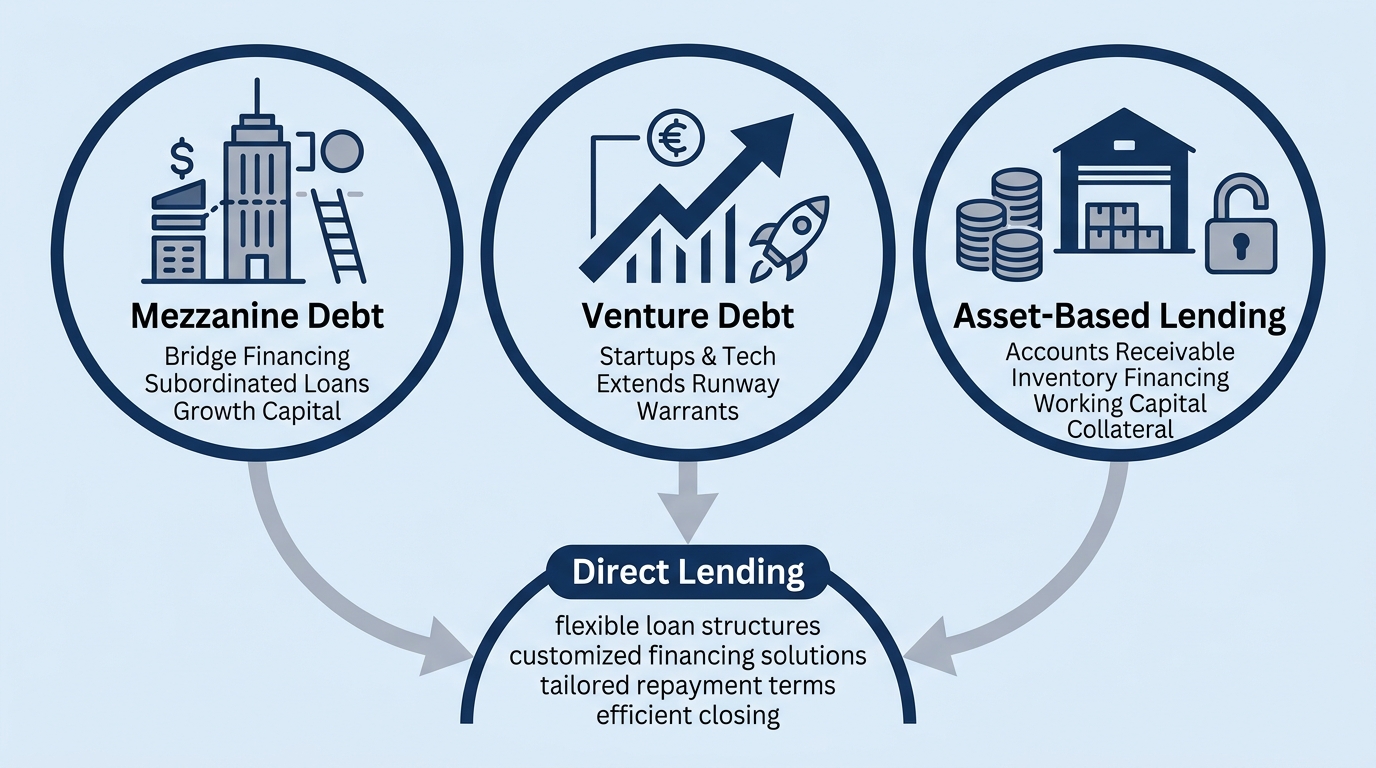
    Infographic showing three flexible financing structures: mezzanine debt, venture debt, and asset-based lending connected to a direct lending hub.

    Flexible financing structures connected to direct lending.

    This flexible financing approach is designed to reinforce your buy-side M&A strategies with speed and precision, complementing our Full-Cycle M&A and capital advisory. To explore a custom-quote structure for your next transaction, Book A Call. This is not an offer or commitment; all financing is subject to due diligence and final documentation.

    3. Speed and Certainty of Execution

    In today’s direct lending market, speed and certainty of execution are decisive advantages for businesses evaluating private capital raising strategies.

    Traditional syndicated bank loans demand months of negotiation among multiple syndicate tiers and require extensive regulatory filings under SEC capital raising regulations; in stark contrast, direct lenders issue committed capital letters upfront and close in weeks, with fewer parties, less documentation, and a near-certain funding outcome.

    Zaidwood Capital’s proprietary market intelligence shows that current U.S. direct lending interest rate spreads remain favorable for borrowers, indicating that institutional lenders are actively seeking to deploy capital and can move swiftly when opportunities arise.

    Our approach to Streamlining Transactions shortens the search and negotiation cycle, and with a global network of over 4,000 investors, we accelerate execution for transactions ranging from corporate debt to GP-led secondary transactions, reducing opportunity cost and securing better terms.

    This speed and certainty, combined with Zaidwood Capital’s full-cycle advisory platform, streamlines access to substantial institutional capital for businesses pursuing growth.

    4. Middle-Market Capital Access

    Middle-market companies with revenues between $10 million and $1 billion frequently encounter a capital gap that traditional bank loans cannot fill, making access to capital in the direct lending market a vital alternative. As our FAQ notes, direct lending transactions close weeks faster than bank loans, with fewer covenants and flexible terms that adapt to a company’s cash flows rather than rigid formulas. Post-2008 regulatory changes constrained traditional bank lending, cementing the direct lending market as the core funding channel for mid-size firms. We help middle-market firms structure direct lending opportunities through our network of over 4,000 institutional investors and $15 billion in deployable capital, accelerating execution and reducing time-to-close. Beyond direct lending, our team deploys wider private capital raising strategies, including GP-led secondary transactions, to meet each company’s unique capital needs. Because direct lending operates under FINRA regulation direct lending, all participants must ensure strict compliance. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.

    5. Private Equity Buyout Support

    The direct lending market has become a cornerstone of private equity buyouts as firms seek speed and flexibility beyond traditional bank leverage loans. We at Zaidwood Capital see direct lender financing offering bespoke terms that align with the specific cash flow profiles of portfolio companies. This private credit approach sidesteps the rigid syndication processes of conventional banks, enabling faster closings and more creative capital structures. GP-led secondary transactions further illustrate how direct lending injects liquidity, allowing general partners to hold assets longer while offering LPs partial exits. Our private capital raising strategies incorporate direct lending solutions to support full-cycle buyout execution from acquisition through value creation. Direct lending also complements traditional bank financing by filling gaps where syndicated markets retreat, a dynamic we harness in our advisory work. As deal complexity grows, we view direct lending not as a niche instrument but as an enabling component driving the next phase of transaction structuring and capital deployment.

    6. Regulatory Landscape and Liquidity

    The direct lending market has experienced profound changes as regulatory oversight intensifies. Heightened scrutiny from the SEC and evolving risk-retention rules have dampened risk appetite among lenders, tightening liquidity dynamics across the sector. This shift is reshaping how capital flows into private credit.

    As bank-led lending retrenches, institutional capital increasingly pivots toward the direct lending sector. Stringent regulatory frameworks—including enhanced disclosure requirements and capital adequacy standards—drive allocators to reassess exposure. Our own analysis confirms that the regulatory environment compels investors to seek more resilient structures and transparency.

    These pressures have accelerated the adoption of private capital raising strategies and GP-led secondary transactions. By facilitating liquidity through secondary market solutions, managers can mitigate the constraints imposed by today’s regulatory landscape.

    Navigating this complexity demands deep market intelligence. Our firm leverages a network of over 4,000 institutional investors and $24.4B+ in aggregate transaction volume to help clients secure capital formation and liquidity in regulated markets. We help lenders and sponsors adapt their strategies, ensuring they remain positioned for success.

    7. Private Capital Raising Strategies

    For middle-market firms, private capital raising strategies offer an alternative to public markets, with the direct lending market serving as a vital source of flexible financing. These approaches enable capital formation for acquisitions, recapitalizations, and liquidity events while avoiding the regulatory complexities of an IPO.

    We help clients evaluate several private capital raising strategies:

    • Equity financing
    • Debt financing
    • Mezzanine debt
    • Direct lending
    • GP-led secondary transactions

    Direct lending, from non-bank institutional lenders, provides tailored capital complementing traditional bank loans. GP-led secondary transactions provide liquidity for limited partners while general partners can continue managing assets. At Zaidwood Capital, we design and execute these capital raises using our network of over 4,000 institutional investors and $15B+ in deployable capital, tailoring solutions to each firm’s profile. We integrate rigorous due diligence as part of our full-cycle M&A and capital advisory approach to ensure a seamless path from strategy to close.

    This site is for informational purposes only. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a broker-dealer.

    8. GP-Led Secondary Transactions

    In a GP-led secondary transaction, the general partner sells a portfolio company into a newly formed continuation fund backed by both existing and new limited partners. This approach, part of broader private capital raising strategies, provides early liquidity to LPs while allowing the GP to retain the asset and pursue additional value creation over a longer horizon. For careful LPs, these transactions offer a path to realize returns before a traditional exit; for GPs, they preserve management continuity and extend the runway for further growth.

    At Zaidwood Capital, we advise GPs on structuring these deals, securing institutional capital through our network of over 4,000 investors, and managing execution from start to finish. Our equity advisory and liquidity solutions practice ensures that each transaction is tailored to the fund’s objectives, streamlining transactions within our full-cycle M&A and capital advisory framework. Beyond GP-led secondaries, we support a spectrum of liquidity and capital formation strategies, including our broader equity advisory and debt advisory capabilities, positioned to serve mid-market funds across changing market cycles.

    Evaluating Direct Lending for Your Capital Strategy

    When evaluating the direct lending market, we recognize it as a private credit solution where institutional lenders provide capital directly to companies, bypassing traditional bank intermediaries.

    Direct lenders typically deliver faster execution, fewer covenants, and more flexible terms than banks—a key advantage when evaluating the direct lending market for companies with strong fundamentals seeking growth capital or acquisition financing without dilutive equity. Through direct lending, we streamline transactions, providing faster access to institutional capital. To determine fit, we assess the lender’s track record, deal flow, and alignment with your capital structure goals.

    As part of a broader set of private capital raising strategies, direct lending can complement other financing tools. GP-led secondary transactions frequently employ direct lending structures to facilitate liquidity or recapitalization.

    Resources

  • Asset-Based Lending for Corporate Expansion: Fast Capital

    Asset-Based Lending for Corporate Expansion: Fast Capital

    Table of Contents

    Funding Corporate Growth with Asset-Based Lending

    While many companies look to traditional bank loans, asset-based lending (ABL) provides a more flexible funding path. Using your accounts receivable, inventory, and equipment as collateral, asset-based lending for corporate expansion gives you faster access to capital—often without diluting equity. Institutional investors focus on asset quality rather than just credit scores, making ABL accessible to asset-rich companies poised for growth. Whether funding an acquisition, bridging working capital gaps, or expanding operations, collateral-based business funding offers a reliable capital solution.

    • Support ABL for growth initiatives without selling equity
    • Fund acquisitions with collateral-based business funding
    • Bridge working capital gaps using receivables and inventory

    Zaidwood Capital’s team of advisors streamlines the process, connecting you to institutional investors through our global lending services. To discuss asset-based financing for expansion that matches your growth plan, Book A Call today.

    Preparing Your Business for Asset-Based Financing

    After clarifying what asset-based financing entails, the next step is preparing your business for asset-based lending for corporate expansion. This involves assembling a detailed inventory of your accounts receivable, equipment, and inventory. Updated financial statements and cash flow projections are critical, as lenders assess collateral coverage and quality to determine borrowing capacity.

    For businesses exploring alternative lending marketplaces, Zaidwood Capital’s research highlights global lending services as one example of asset-based solutions. Our debt advisory team helps you navigate these options and prepare a competitive application. Partnering with an advisor can reduce common pitfalls such as incomplete asset schedules or outdated financials that delay approval.

    Begin your preparation with these essential steps:

    • Assemble a detailed asset inventory listing all accounts receivable, equipment, and inventory with current valuations.
    • Update financial statements and project cash flows for at least 12–24 months.
    • Calculate your collateral coverage ratio and address any shortfalls by adjusting asset schedules or obtaining additional guarantees.
    • Consult our debt advisory team to align your documentation with lender standards and strengthen your application.

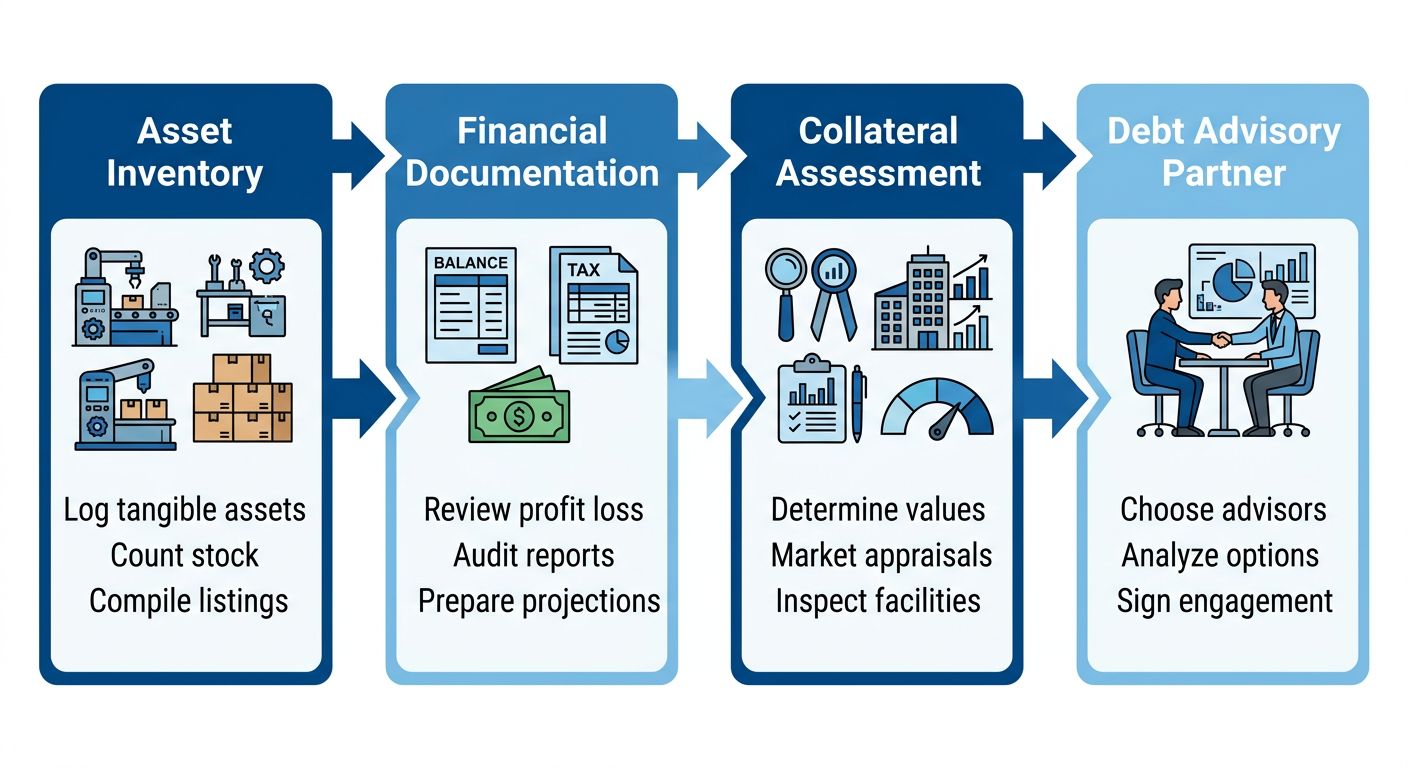
    The four key stages—asset inventory, financial documentation, collateral assessment, and partnering with a debt advisor—are illustrated below. A thorough preparation typically takes four to six weeks, but our streamlined process can accelerate timelines.

    Diagram of four stages for preparing asset-based financing: Asset Inventory, Financial Documentation, Collateral Assessment, and Debt Advisory Partner

    Four-stage process for asset-based financing preparation

    Securing asset-based lending for corporate expansion ultimately depends on presenting a clear, lender-ready financial picture. Once your documentation is complete and your collateral position is clear, evaluating the right lender or loan structure becomes the next critical step. Our team can help you explore options and expedite your timeline—book a call to discuss your situation.

    Assessing Your Collateral Base for Maximum Borrowing Capacity

    With capital options spanning equity to structured debt, the next step is to assess your collateral base—the set of assets you can pledge to secure financing. In asset-based lending for corporate expansion, a well-documented collateral position directly strengthens your borrowing capacity.

    Common qualifying assets include accounts receivable, inventory, equipment, commercial real estate, and intellectual property. Lenders then apply valuation haircuts based on asset liquidity and risk to determine your borrowing base, the maximum amount available. A stronger collateral base not only boosts borrowing capacity but can also improve loan terms.

    Regular audits and accurate documentation are essential, as lenders value assets only to the extent they can be verified. This discipline is especially critical when financing emerging markets M&A, where robust collateral valuation mitigates cross‑border risk. A thorough collateral assessment is the first step toward a compelling loan application. Our advisory team leverages a network of over 4,000 institutional investors and access to $15B+ in capital to help you structure corporate expansion financing that fits your objectives. Book A Call to begin.

    Evaluating Your Financial Profile and Creditworthiness

    Securing asset-based lending for corporate expansion begins with a thorough evaluation of your company’s financial profile. We assess creditworthiness through detailed analysis of cash flow stability, collateral quality, and debt service capacity, examining both historical performance and forward-looking projections. This foundational step is critical to building a credible case for lenders and aligning your capital raising strategy with market expectations.

    Our full-cycle due diligence integrates financial, operational, and legal review to build a comprehensive credit profile that meets rigorous capital market standards. Unlike traditional lending, this approach prioritizes the intrinsic value of your company’s assets and recurring revenue, providing a more flexible path to growth capital.

    We look beyond conventional credit scores to evaluate asset liquidity, industry trends, and management experience, strengthening your credit narrative for expansion financing. This evaluation directly shapes the structure of debt solutions tailored to your objectives. By understanding your unique financial position, we help you access the capital needed to scale with confidence and transparency.

    Structuring the Asset-Based Debt for Your Expansion Goals

    Asset-based debt — asset-based lending for corporate expansion — unlocks liquidity by tying credit capacity to your company’s accounts receivable, inventory, and equipment. Drawing on our acquisition financing framework, we help you structure the borrowing base, where advance rates per asset class determine how much capital you can draw. Typically, receivables command higher advance rates than inventory, and equipment may be financed under a separate term component.

    Depending on whether you need flexible working capital for day-to-day operations or a dedicated term loan to fund capital expenditures, we tailor the structure to align with your specific expansion timeline and cash flow profile.

    Our Full-Cycle M&A and capital advisory expertise encompasses regulatory compliance, so your facility aligns with SEC market oversight and manages risk effectively. By partnering with us, you gain access to customized capital solutions that streamline the entire transaction. Book A Call to discuss how we will design your expansion financing.

    Gathering Documentation for the Application Process

    Once you understand the advantages of asset-based lending for corporate expansion, the next step is gathering the required documentation. We typically ask clients to prepare the following: balance sheet, income statement, cash flow statement, accounts receivable aging reports, inventory reports, accounts payable details, and a current business plan. Accurate, up-to-date financial data accelerates our due diligence and helps secure favorable terms from institutional lenders. Our advisory team, leveraging the proprietary Velocity Matrix, assists in organizing and presenting these materials as part of our Full-Cycle M&A and capital advisory services. Securing an asset-based loan for corporate growth financing demands thorough preparation. Our proactive document review, a core tenet of our Streamlining Transactions philosophy, simplifies the paperwork and keeps your transaction on track for secured lending for business expansion. Ensuring all documentation meets applicable disclosure standards is essential; as a capital advisory firm, we are not a registered broker-dealer and securities offerings are placed through Finalis Securities LLC, which adheres to FINRA securities regulation. For a comprehensive checklist tailored to asset-based lending deals, visit our internal Documentation Requirements page. With your documentation ready, Zaidwood Capital’s team will initiate a streamlined due diligence and review, covered in the next section.

    Engaging a Debt Advisory Partner to Secure Optimal Rates

    Asset-based lending for corporate expansion offers a direct path to scale, but securing optimal rates requires deep market access. Zaidwood Capital’s debt advisory team leverages relationships with over 4,000 institutional investors to negotiate competitive terms, and our proprietary Velocity Matrix analytics ensure each debt structure is tailored to your growth objectives.

    Our full-cycle support includes comprehensive due diligence, documentation, and seamless integration with our broader capital formation capabilities—from mezzanine and venture debt to equipment financing. In every transaction involving asset-based lending for corporate expansion, our $24.4 billion aggregate volume and 4,000+ investor network give clients a decisive edge.

    To discuss how our debt advisory can structure your next expansion, Book A Call for a confidential consultation. This communication does not constitute investment advice; please consult your own legal and financial advisors. Securities are offered through Finalis Securities LLC. Zaidwood Capital is not a registered broker-dealer.

    When you evaluate asset-based lending for corporate expansion, we initiate the institutional due diligence process — a structured assessment of financial, operational, legal and strategic factors. This systematic review draws on industry benchmarks such as the ICMA Capital Market Standards to ensure every assumption is tested.

    Our due diligence unfolds through three distinct stages: initial review, detailed analysis, and final validation. At each step, we scrutinize collateral quality, cash‑flow projections and covenant frameworks critical to asset‑based financing transactions. Following ICMA-aligned practices, we assess operational resilience and strategic fit, providing you with a comprehensive decision-making framework.

    Once you have completed a robust due diligence cycle, you can move into the final structuring and closing phase with confidence. Our integrated approach ensures that no material detail is overlooked, positioning your company for a successful execution. With Zaidwood Capital’s full‑cycle advisory, you gain the clarity needed to negotiate favorable terms and accelerate growth.

    Closing the Facility and Deploying Capital

    Once a business has evaluated its financing alternatives, closing an asset-based lending facility marks the final step before accessing expansion funding. This phase requires finalizing loan documentation and satisfying all conditions precedent, which our team coordinates to keep the transaction moving efficiently and effectively. The U.S. Securities and Exchange Commission provides regulatory oversight for capital deployment, and private offerings must align with its disclosure framework. Through our Full‑Cycle M&A and capital advisory framework, we structure the release of corporate expansion capital based on milestones, acquisition tranches, or working‑capital draws that match the company’s growth plan.

    Nothing in this section guarantees specific outcomes or constitutes a solicitation or commitment to transact. Parties should consult their own legal, tax, and financial advisors before proceeding. This content is for informational purposes only and does not represent investment advice. Zaidwood Capital is not a registered broker‑dealer.

    Overcoming Common Obstacles in Asset-Based Lending

    Overcoming common obstacles in asset-based lending for corporate expansion requires a strategic approach. While asset-backed funding for growth initiatives offers clear advantages, businesses often encounter hurdles that can slow momentum or create deal friction. We help our clients navigate these challenges efficiently.

    For instance, valuation disagreements between borrowers and lenders can stall negotiations. We resolve this by coordinating independent third-party appraisals and ensuring audited asset schedules are prepared well in advance, aligning expectations before formal discussions begin. Another challenge involves strict collateral eligibility criteria and conservative advance rates. To address this, we negotiate floating advance rates tied directly to asset quality, ensuring that the borrowing base reflects the true value of receivables, inventory, and equipment.

    Time-intensive documentation and approval cycles represent a third obstacle. Through our Full-Cycle M&A and capital advisory model, we leverage a pre-vetted network of institutional investors to dramatically compress timelines. Our streamlined due diligence process, covering financial, legal, and operational dimensions, reduces institutional friction and accelerates underwriting. By connecting the right assets to the right capital sources, we remove bottlenecks that often derail corporate expansion plans.

    Yet these challenges are manageable with the right partner. We invite you to Book A Call for a personalized assessment and to learn how we can structure a funding solution that supports your growth trajectory. We prioritize pragmatic structuring and rapid execution to maintain momentum, preserve cash flow, and protect operations.

    Accelerating Your Corporate Expansion Journey

    Beyond traditional financing, asset-based lending for corporate expansion offers a direct path to fund growth by leveraging your company’s receivables, inventory, and equipment as collateral. Institutional investors typically look for stable cash flows, strong asset quality, and a clearly defined use of funds—criteria designed to ensure alignment between your expansion objectives and investor mandates, as detailed in our advisory resources.

    At Zaidwood Capital, we connect businesses with our network of over 4,000 institutional investors and provide full-cycle advisory to streamline the funding process from qualification through closing. Asset-based lending to fund growth often delivers faster, more flexible capital compared to conventional bank loans, enabling you to seize market opportunities without the extended timelines traditional routes demand. To explore how your company qualifies for corporate expansion through asset-backed financing, book a consultation with our team or continue to the next section for a deeper look at the qualification framework.

    Resources

  • Family Office Liquidity Management Strategies: Essential Guide

    Family Office Liquidity Management Strategies: Essential Guide

    Table of Contents

    The Foundations of Family Office Liquidity Management

    Effective family office liquidity management strategies ensure that sufficient cash and near-cash assets are available to meet obligations—capital calls, operating expenses, and strategic investments—without disrupting long-term portfolio allocations. This foundational discipline balances near-term liquidity needs with the family’s overarching wealth preservation goals.

    Capital call liquidity management is a critical concern, given that private equity and venture funds require sudden capital injections. At the same time, uneven cash flows from operating businesses underscore the need for disciplined family office treasury management to maintain adequate buffers without sacrificing returns.

    Institutional-grade advisory services, such as debt advisory and equity liquidity solutions, help family offices optimize their liquidity position. We draw on $24.4B+ in aggregate transaction volume and a network of over 4,000 global investors, aligned with ICMA guidelines, to provide solutions like global lending services. In the sections that follow, we’ll explore how these strategies are structured to meet the unique demands of family offices.

    1. Tiered Liquidity Buckets for Stability

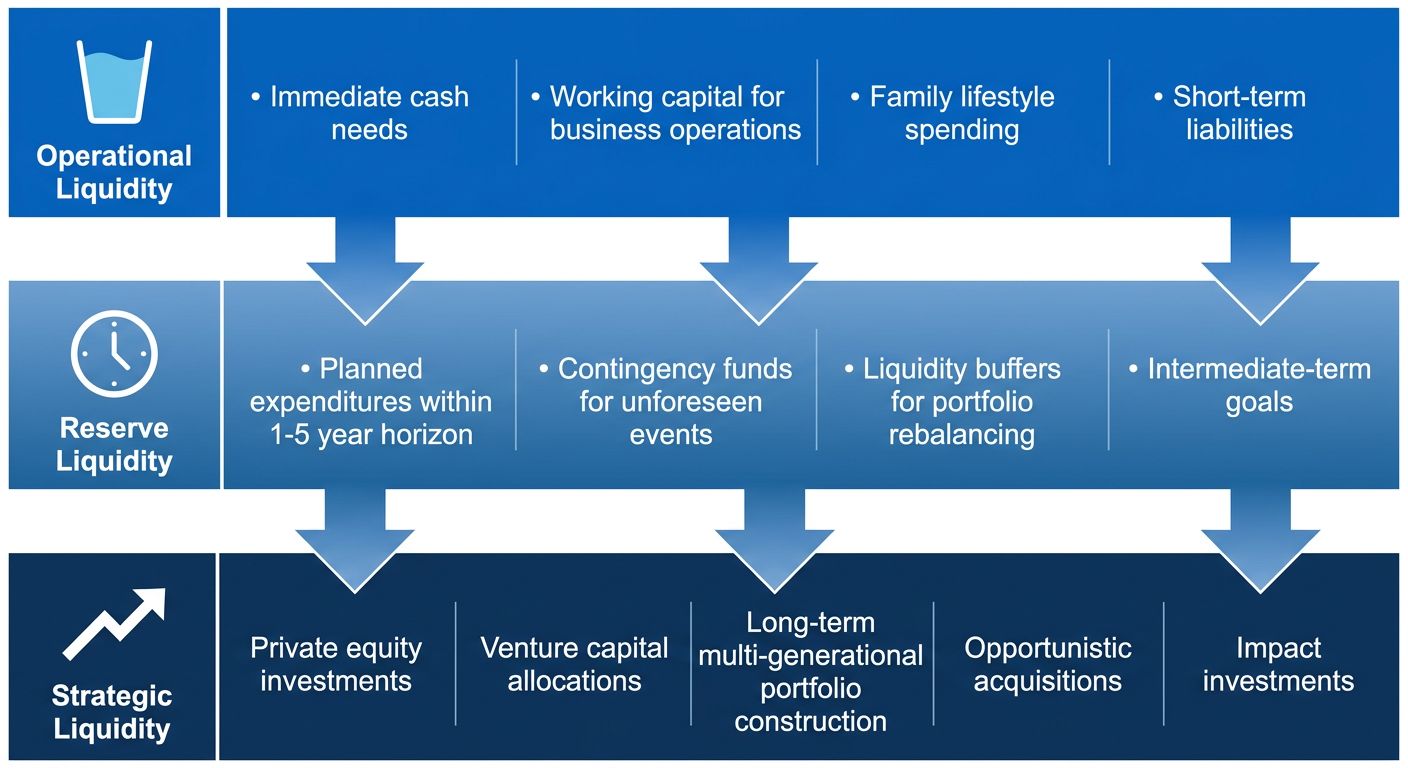
    In family office liquidity management strategies, we define tiered liquidity buckets as a framework that segments assets by accessibility, ensuring that near-term obligations can be met without liquidating long-term holdings.

    • Operational: immediate access cash for expenses and capital calls.
    • Reserve: 30- to 90-day instruments, such as commercial paper.
    • Strategic: longer-term investments for planned growth.

    This structure anchors capital call liquidity management by pre-positioning funds before drawdowns occur. Family office treasury management relies on cash flow forecasting to calibrate each bucket, mitigating forced liquidation risk. As Zaidwood Capital’s educational materials note, commercial and industrial loans are a prime example of a short-term vehicle that fits naturally within the reserve tier, offering working-capital support while protecting longer-horizon assets.

    Three-tiered liquidity structure infographic showing operational, reserve, and strategic liquidity buckets with blue gradient arrows

    Tiered liquidity buckets for family office stability

    Ultimately, robust family office liquidity management strategies align each bucket with anticipated calls and contingencies — a principle Zaidwood Capital’s liquidity management best practices reinforce. In the next section, we detail the asset classes assigned to each tier.

    2. Private Equity Liquidity Solutions

    Building on our advisory platform, private equity liquidity solutions help investors access capital without selling assets. They are essential in family office liquidity management strategies, where preserving long-term investments during short-term cash needs is critical.

    A key driver of private equity liquidity strategies for family offices is capital call liquidity management. When a general partner calls capital, limited partners must fund commitments promptly. Liquidity demands also arise in other scenarios:

    • Addressing uneven cash flows
    • Funding opportunistic co-investments
    • Covering tax or estate obligations
    • Rebalancing portfolios without disruption

    Through our Equity Advisory practice, we leverage the Velocity Matrix and our network of over 4,000 institutional investors with $15 billion in available capital to source liquidity solutions tailored to specific needs. Our full-cycle M&A and capital formation expertise allows us to design facilities that meet family office treasury management objectives, providing cash when required without disrupting strategic portfolios. Every engagement is custom-quoted, and no outcome is guaranteed.

    This integrated approach to liquidity sets the stage for our debt advisory services, which provide the leverage for growth. This discussion is for informational purposes only and is not investment advice. Securities are offered through Finalis Securities LLC.

    3. Managing Illiquidity Premiums Effectively

    Effective family office liquidity management strategies begin with a clear understanding of what an illiquidity premium represents — the additional return investors demand for holding assets that cannot be quickly converted to cash without meaningful price concessions. At Zaidwood Capital, we emphasize that capturing this premium requires deliberate planning rather than passive acceptance. Successful liquidity management for family offices involves constructing portfolios with calibrated exposure across liquidity tiers, ensuring that long-duration commitments are matched with patient capital and clearly defined holding periods.

    We recommend rigorous assessment of illiquidity premiums through historical data analysis and liquidity discount models, which help quantify the expected compensation for reduced marketability. A disciplined approach to family office treasury management incorporates capital call liquidity reserves — cash or near-cash allocations specifically designated to meet drawdown requests from private investment commitments. This capital call liquidity management framework protects portfolios from forced selling and preserves the integrity of the long-term investment strategy.

    Industry best practices established by the International Capital Market Association provide valuable guidance on bond market liquidity and transparency standards. We incorporate these principles when advising on portfolio construction, recognizing that liquidity conditions evolve across market cycles. Educating stakeholders about the relationship between illiquidity and expected returns, and maintaining adequate liquidity buffers for capital calls, positions family offices to earn meaningful premiums while sustaining operational flexibility across full-cycle market environments.

    4. Capital Call Liquidity Management

    Effective capital call liquidity management is a cornerstone of capital call liquidity management for family offices and institutional investors. A capital call is a formal request from a fund manager requiring investors to fulfill their committed capital obligations. Our role is to help clients meet these requests on time without disrupting cash flow or long-term investment returns.

    We approach capital call liquidity strategies with three primary tools: maintaining a dedicated cash buffer, arranging a capital call line of credit, and structuring committed capital facilities. At Zaidwood Capital, our capital call financing solutions are specifically designed for family offices and private investors, as detailed in our Capital Call Financing FAQ. Unlike standard commercial and industrial loans—which are typically used for operating expenses or expansion and rely on asset-based or cash-flow lending—capital call financing is purpose-built for short-term bridging until called capital is distributed.

    This disciplined approach to family office treasury management helps investors avoid forced asset sales, default penalties, and missed opportunities. In the next section, we examine practical steps to implement these liquidity safeguards.

    5. Dividend Recapitalization for Diversification

    Family office liquidity management strategies often incorporate dividend recapitalization, a transaction where a company borrows to pay a dividend to its owners. This provides partial liquidity, letting family offices meet capital call liquidity management requirements or implement family office treasury management initiatives without selling underlying holdings. Freeing up capital in this way enables reinvestment across new asset classes, enhancing portfolio diversification and resilience.

    We also weigh the illiquidity premium inherent in private market investments. Zaidwood Capital’s FAQ highlights that limited partners demand a premium for reduced liquidity, shaping how we approach recapitalizations. Funding can come from sources like commercial and industrial loans, distinguishing this method from a full exit or secondary sale. By preserving ownership while accessing capital, family offices maintain ongoing alignment with management and redeploy proceeds strategically. This technique is one of several recapitalization tools we use to balance liquidity with long-term portfolio objectives.

    6. Treasury Management Best Practices

    To move from theory to practice, family offices should adopt proven family office liquidity management strategies, as outlined in our treasury management resources.

    • Prioritize cash flow forecasting with a rolling six-month horizon and monthly updates to anticipate liquidity needs, proactively manage upcoming capital calls, and avoid unexpected funding gaps.
    • Diversify counterparty risk by maintaining banking relationships with at least three independent institutions, reducing concentration risk and ensuring access to liquidity during market disruptions.
    • Develop a formal family office treasury management policy that includes liquidity stress testing under multiple market scenarios, such as interest rate spikes or capital call surges.
    • Use capital call liquidity management as a strategic tool to cover short-term funding gaps without forced asset sales, preserving long-term portfolio value.
    • Leverage treasury management software or real-time dashboards for consolidated visibility into cash positions, portfolio liquidity, and committed capital calls.

    These practices build a resilient liquidity framework; the next section explores advanced treasury technology solutions.

    7. Optimizing Private Equity Allocations

    Optimizing private equity allocations requires robust family office liquidity management strategies that balance the pursuit of the illiquidity premium with the need for accessible capital. At Zaidwood Capital, we see the illiquidity premium adding 2–3% to long-term returns, but it demands careful liquidity planning. Private equity commitments inherently involve multi-year lock-ups and unpredictable capital calls, so families must develop a clear liquidity strategy for family offices. Effective capital call liquidity management involves forecasting cash outflows and maintaining dedicated reserves to meet drawdowns without disrupting operating budgets or forcing premature asset sales.

    In our experience at Zaidwood Capital, family office treasury management plays a central role in ensuring that PE commitments align with overall portfolio liquidity. Diversifying commitments across vintage years and fund strategies mitigates concentration risk and smooths cash flow demands. We advise family offices to set allocation targets based on their investment horizon and liquidity constraints, not solely on return expectations. With these optimization principles, family offices can move to execute their private equity strategy confidently.

    8. Leveraging Capital Advisory Expertise

    Given these complexities, leveraging our Full-Cycle M&A and capital advisory expertise becomes essential. When designing in family office liquidity management strategies, we assess asset composition and cash flow profiles to select appropriate financing instruments.

    Through our full-cycle advisory process, we help family offices and companies prepare for the rigorous institutional qualification procedures associated with asset-based lending and cash flow financing. As outlined in our internal FAQ, this includes compiling audited financials, three-to-five-year cash flow projections, and detailed business plans that demonstrate creditworthiness. For capital call liquidity management, such financing can provide committed credit lines that support fund contributions without forcing asset sales.

    Our treasury management advisory, grounded in the best practices shared in our Treasury Management FAQ, strengthens family office treasury management by introducing disciplined cash flow forecasting, efficient working capital management, and strategic deployment of liquidity reserves. We work to ensure that surplus cash is invested in line with the family office’s risk tolerance and near-term cash needs.

    Zaidwood Capital’s institutional network—connecting to over 4,000 investors with more than $15 billion in deployable capital—can be structured to support both capital call liquidity management and ongoing treasury requirements.

    With this advisory support, family offices can build resilient liquidity strategies aligned with long-term objectives.

    Building a Resilient Liquidity Framework for Your Family Office

    To address capital efficiency challenges in family office liquidity management strategies, we recommend structuring a resilience framework across distinct tiers. Begin by segregating operational, reserve, and growth liquidity to align cash flows with investment horizons. A disciplined treasury function underpins effective capital call liquidity management, ensuring obligations are met without forced asset disposals.

    • Maintain a contingency reserve equal to 10–15% of committed capital to cover unexpected drawdowns.
    • Embed SEC regulatory updates into risk assessments, staying current with evolving compliance expectations.
    • Use capital call financing as a bridge, preserving invested assets during liquidity events.
    • Benchmark your approach against international wealth management firms to refine family office treasury management protocols.

    A robust framework transforms liquidity from a constraint into a strategic advantage for multi-generational wealth stewardship.

    Resources

  • Get Venture Debt for Scaleups 2026: Fast Non-Dilutive Capital

    Get Venture Debt for Scaleups 2026: Fast Non-Dilutive Capital

    Table of Contents

    Venture Debt Opportunities for Scaleups in 2026

    Beyond general capital formation, a particularly compelling path for venture debt for scaleups in 2026 is the strategic use of non-dilutive growth capital. This form of debt capital allows companies to extend their cash runway and fund critical growth milestones without further eroding founder and investor ownership. By prioritizing growth metrics over traditional cash-flow underwriting, venture debt stands apart from conventional bank loans.

    Current market conditions make this window especially relevant. Reduced venture equity availability, coupled with favorable debt terms for well-performing companies, means debt financing serves as a powerful tool between equity rounds. In our debt advisory practice, we connect growth-stage companies with appropriate capital partners, leveraging our access to over 4,000 global investors and $15B+ in deployable capital. Understanding the opportunity is the first step; the next section outlines how we structure and execute these engagements.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. Book A Call for a custom venture debt consultation.

    Preparing for Your Venture Debt Strategy

    Now that you understand the advantages of venture debt, proper preparation is critical to securing favorable terms. For companies exploring in venture debt for scaleups 2026, readiness separates those who negotiate from a position of strength from those who accept whatever terms are offered. Thorough preparation signals to lenders that your business is a calculated risk, not a speculative one.

    We recommend our clients prepare the following key financial documents before approaching any lender:

    • Audited financials covering the last two fiscal years to demonstrate historical performance and accounting rigor
    • Twelve-month cash flow projections showing precisely how the debt will accelerate growth and when repayment capacity materializes
    • A clean, fully diluted cap table reflecting all equity rounds, option pools, and convertible instruments
    • A detailed use-of-funds memo tying every dollar to a specific growth milestone, whether a product launch or market expansion

    Lenders evaluate your application through specific metrics: annual recurring revenue (ARR), gross margin stability, monthly cash burn rate, and debt-service-coverage ratio (DSCR). According to Silicon Valley Bank services benchmarks, strong performance across these indicators often correlates with more flexible term structures. International Capital Market Association (ICMA) guidelines further emphasize the importance of transparent documentation in private debt placements.

    Venture debt functions as non-dilutive growth capital, allowing you to extend runway without surrendering equity. Unlike revenue-based financing, which ties repayments to top-line fluctuations, venture debt typically includes interest-only periods and may carry warrant coverage as standard structuring tools—not guarantees, but negotiable components.

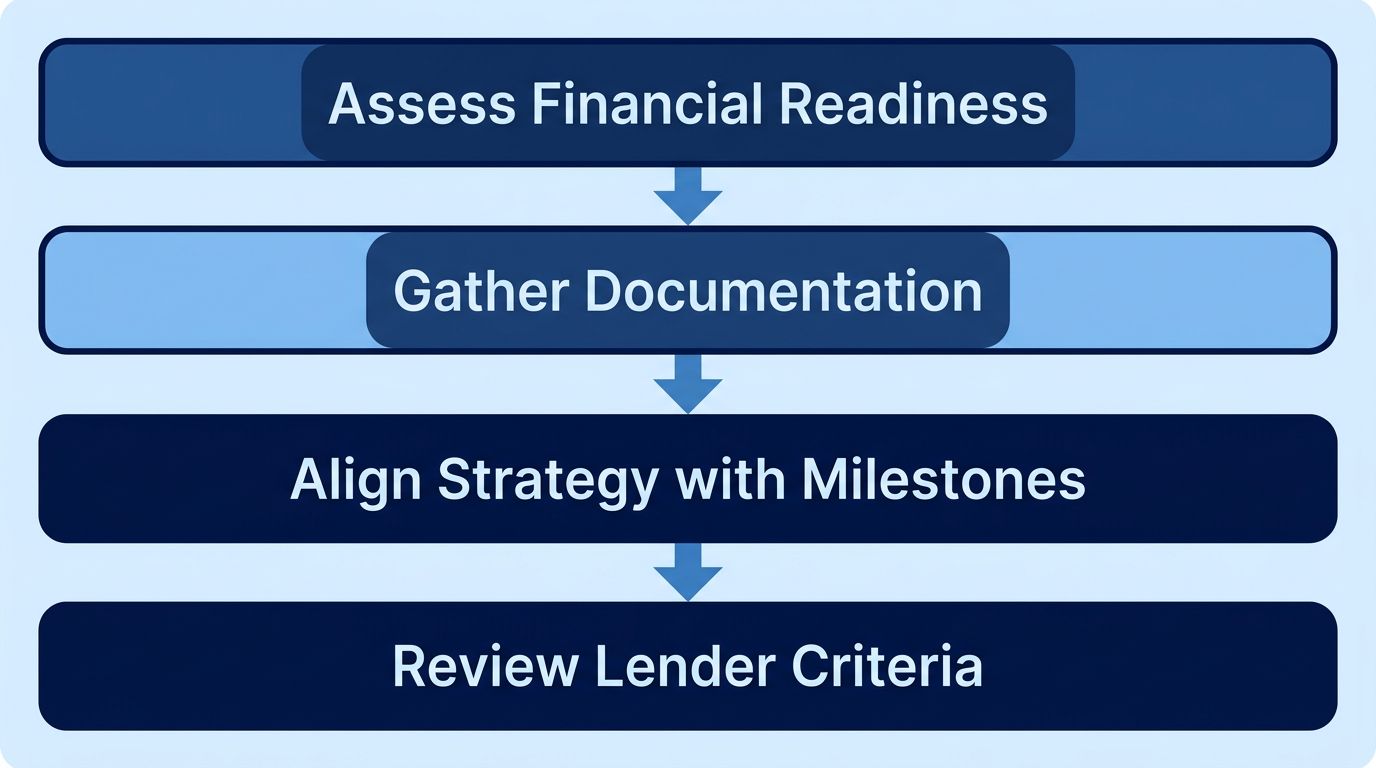
    Vertical process flow diagram showing four steps for preparing a venture debt strategy: assess financial readiness, gather documentation, align strategy with milestones, and review lender criteria.

    Four-step venture debt preparation process flow

    Align your debt strategy with board-approved growth milestones and involve your CFO early. At Zaidwood Capital, our Debt Advisory team helps clients benchmark lender terms against current market standards, ensuring you approach conversations with the confidence that preparation provides. Once your strategy is fully prepared, the next step is approaching lenders with a compelling, data-backed narrative.

    Assess Your Capital Structure Needs

    Now that you understand the basics of capital structure, it’s time to assess your specific needs. How do you determine the right mix of debt and equity for your company? For scale-ups evaluating venture debt for scaleups in 2026, a structured self-assessment is the critical first step toward identifying the most suitable financing path.

    We guide founders through evaluating several key factors to build a coherent capital strategy:

    • Current debt-to-equity ratio: Understanding your existing leverage and its impact on future borrowing capacity
    • Projected cash flow: Assessing whether revenue streams can comfortably service debt obligations
    • Growth stage: Distinguishing between early-stage, scale-up, and mature company dynamics, each with distinct risk profiles and capital access
    • Purpose of capital: Clarifying whether funds are needed for working capital, an acquisition, or expansion initiatives

    Exploring non-dilutive growth capital options such as revenue-based financing can preserve ownership while funding growth. Engaging experienced venture capital consultants helps interpret these factors and design a structure aligned with your objectives.

    With your needs assessed, the next section explores the specific capital solutions that match your profile.

    Identify Leading Venture Debt Lenders

    To identify the right partner, scaleups should evaluate leading venture debt lenders based on their track record, industry expertise, and loan terms. For companies seeking venture debt for scaleups 2026, understanding the lender landscape is essential. Non-dilutive growth capital preserves equity while funding expansion, and revenue-based financing offers flexible repayment structures aligned with business performance.

    According to Zaidwood Capital, notable lenders include:

    • Silicon Valley Bank – Provides venture debt and banking services to technology and life sciences companies at all stages.
    • Hercules Capital – Specializes in growth-stage technology and life sciences companies with flexible financing solutions.
    • TriplePoint Capital – Offers debt financing and leasing to venture capital-backed companies across diverse sectors.
    • Western Technology Investment – Focuses on early to mid-stage technology and life sciences companies.
    • Oxford Finance – Provides senior secured loans to healthcare and life sciences firms.

    When evaluating lenders, scaleups should assess loan size range, interest rate benchmarks, warrant coverage, and repayment flexibility. At Zaidwood Capital, our network includes access to many of these lenders, and we can help match companies to the right partner. Once you have identified potential lenders, the next step is to prepare your approach.

    Prepare Your Financial Documentation

    Once you understand the types of capital available, preparing your financial documentation is essential when seeking venture debt for scaleups 2026. The following documents are critical:

    • Audited Financial Statements (last 3 fiscal years) demonstrate revenue stability and profitability trends.
    • Detailed Cash Flow Projections (12–24 months), especially for non-dilutive growth capital and revenue-based financing.
    • Corporate Tax Returns (last 2 years) validate financial health.
    • Current Debt Schedule (if applicable) lists existing loans or convertible notes.
    • Pro Forma Financials model the new venture debt’s impact on cash flow and leverage ratios.
    • Virtual Data Room with clear folder labels organizes all files for submission.

    For documentation standards, the International Capital Market Association provides a useful framework. Having these documents ready will streamline your capital raise. This information does not constitute investment advice. With your documents organized, you are ready to proceed with the application process.

    Structure the Deal Terms and Warrant Coverage

    Moving from an overview of venture debt, we now focus on the specific components that define a term sheet. When structuring venture debt for scaleups 2026, our team at Zaidwood Capital tailors each deal to the company’s stage and growth trajectory. A typical term sheet includes a maturity period of 3 to 5 years, an interest rate composed of a cash component plus payment-in-kind (PIK), and an upfront fee that covers due diligence and administrative costs.

    Warrant coverage — often ranging from 5% to 20% of the loan principal — provides the lender with equity participation without immediate founder dilution. We negotiate the strike price (typically set at the current preferred round price), the warrant term (commonly 5-7 years), and exercise rights to align incentives. This structure offers lenders upside while preserving non-dilutive growth capital for the company.

    Terms are calibrated to a company’s credit profile, revenue projections, and market stage; for instance, revenue-based financing considerations can influence the repayment schedule. Our full-cycle M&A and capital advisory approach ensures each element supports long-term scalability, which we will explore further in the next section covering the application process.

    Negotiate Covenants and Closing Conditions

    With your term sheet structured, the focus shifts to covenants and closing conditions — the final hurdles before funding. For a growth capital debt financing round, these terms define your operational boundaries and the prerequisites to access capital. In the 2026 landscape, venture debt for scaleups 2026 is an increasingly popular tool for companies seeking non-dilutive growth capital, but the protective mechanisms lenders require can significantly impact your financial flexibility.

    Covenants are contractual promises you make to the lender. They broadly fall into three categories:

    • Affirmative covenants: Actions you must take, like maintaining insurance or providing audited financials.
    • Negative covenants: Actions you cannot take without lender consent, such as incurring additional senior debt or selling key assets.
    • Financial covenants: Specific metrics you must meet, often a minimum cash balance or an EBITDA target.

    For a company using revenue-based financing, the financial covenants are typically tied to recurring revenue growth rather than static balance-sheet ratios. Zaidwood Capital’s advisory approach emphasizes aligning these tests with your realistic operating model. Closing conditions are the prerequisites you must satisfy before the initial draw. These can include a satisfactory legal due diligence review, board approval of the transaction, and delivery of a final legal opinion — standard steps that verify your company’s readiness for a full-cycle advisory engagement.

    We guide our clients to negotiate these terms with a pragmatic lens: insist on covenants that reflect your business’s actual trajectory, and build closing condition checklists with achievable timelines. Documenting all agreed terms in a commitment letter before moving to definitive documentation is a critical step. To discuss how we can help tailor these terms for your specific raise, we invite you to Book A Call with our team.

    Complete Full-Cycle Due Diligence

    As a prerequisite for securing non-dilutive growth capital such as venture debt for scaleups in 2026, we conduct full-cycle due diligence that serves as the intelligence backbone of every transaction. Our process is a comprehensive, integrated assessment spanning six core domains: financial, legal, operational, commercial, IT, and human capital.

    This approach identifies risks and uncovers hidden opportunities across the entire deal lifecycle. We tailor our methodology precisely to your transaction type—whether it is a buy-side M&A mandate, a sell-side divestiture, or a capital raise involving revenue-based financing. By leveraging our proprietary Sovereign Data Nexus, we enhance commercial and operational assessments with real-time market intelligence, positioning your company for stronger, more informed negotiations.

    Our full-cycle process is engineered to compress timelines and reduce transactional uncertainty, ensuring that every facet of the business is scrutinized before approaching our network of over 4,000 institutional investors. This diligence forms the foundation upon which we structure optimal deal terms, seamlessly connecting strategic insight with execution.

    Finalize Capital Deployment and Monitor

    Once capital is secured, the next critical phase is deploying those funds effectively. For clients utilizing venture debt for scaleups 2026, this means executing tailored agreements. We finalize the deployment process through precise document execution, coordinated fund transfers and direct alignment with the portfolio company’s treasury team. Whether the capital is structured as non-dilutive growth capital or revenue-based financing, our team manages the closing mechanics to ensure a seamless transition from commitment to working funds.

    Following deployment, our full-cycle mandate continues through a structured monitoring framework. We provide periodic performance reporting, access to our proprietary Deal Vault for real-time document review and regular strategic check-ins. Our oversight is powered by proprietary tools like the Sovereign Data Nexus—our integrated intelligence infrastructure—and the Velocity Matrix, which tracks transaction momentum. This commitment ensures we remain a long-term strategic partner, delivering tailored advisory long after the transaction closes. Our approach is a hallmark of our Full-Cycle M&A and capital advisory, streamlining transactions through Financial Services 3.0 efficiencies. Past performance does not guarantee future results.

    Overcoming Common Venture Debt Hurdles

    Securing venture debt for scaleups 2026 presents unique challenges, from stringent qualification requirements to complex term negotiations. We understand that navigating these obstacles can feel overwhelming, particularly when founders are focused on preserving equity and maintaining operational momentum.

    Qualification and Positioning

    A primary hurdle is demonstrating the revenue predictability and capital efficiency that lenders require. Many scaleups mistakenly apply before achieving the necessary financial milestones. To overcome this, companies must present clear growth metrics and a defensible business model. Accessing non-dilutive growth capital demands a narrative that aligns scalable unit economics with a realistic path to profitability, a positioning we help our clients refine.

    Term Negotiations and Structure

    Misunderstanding repayment structures is a common pitfall. We often see companies over-leverage by focusing solely on the headline amount rather than the amortization schedule and covenant package. This misalignment can strain cash flows at critical growth junctures. Revenue-based financing is one flexible alternative, but it requires careful modeling against projections to ensure it complements, rather than constrains, your growth trajectory. A successful strategy involves mapping debt service to specific, value-creating milestones to avoid triggering restrictive covenants.

    After securing growth capital, many firms look toward global expansion, pursuing emerging markets M&A as a subsequent step in their scaling journey.

    Our advisory approach at Zaidwood Capital, grounded in extensive institutional knowledge, directly mitigates these risks. We guide clients through due diligence, leveraging our network to secure terms that support rather than hinder growth. Unlike equity financing, venture debt is fundamentally a non-dilutive tool designed to extend your runway while preserving ownership. We invite you to Book A Call to discuss how we can structure a solution tailored to your specific growth milestones.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis.

    Launch Your Venture Debt Journey with Confidence

    For scaleups evaluating venture debt for scaleups 2026, a new strategic path is emerging that protects your equity while fueling expansion. Venture debt is a form of non-dilutive growth capital designed to complement your existing equity rounds. Rather than trading away additional ownership, this approach offers revenue-based financing that aligns repayment with your company’s growth trajectory—giving you the resources to scale without surrendering control.

    At Zaidwood Capital, we structure this journey with precision. Through our Debt Advisory service and a global network of over 4,000 institutional investors, we help founders access the right capital for their stage. We tailor terms to each stage and leverage market insights from emerging markets and fintech trends strategically to align capital with your growth objectives. Book A Call to explore how venture debt can move your business forward.

    Resources

  • What Is NAV Financing in Private Equity? A Complete Guide

    What Is NAV Financing in Private Equity? A Complete Guide

    Table of Contents

    NAV financing in private equity represents a sophisticated form of fund-level leverage secured against the net asset value of a private equity fund’s portfolio of companies. Unlike traditional fund-level debt, which may rely on general partner or limited partner guarantees, these asset-backed credit facilities derive their security primarily from the underlying portfolio’s appraised worth. As leaders in Full-Cycle M&A and capital advisory, we at Zaidwood Capital structure these facilities to provide sponsors with a flexible, non-dilutive capital solution that aligns with the fund’s existing asset base while preserving its long-term investment strategy.

    This form of fund-level leverage has gained traction for several common applications. Sponsors frequently use NAV facilities to accelerate distributions to limited partners, avoiding the need for a full asset sale when liquidity is desired. They also serve as a bridge for follow-on investments, enabling a fund to support portfolio company add-on acquisitions between traditional capital calls. The Institutional Limited Partners Association (ILPA) has acknowledged the growing role of fund-level credit, emphasizing in its guidance that any such leverage must be aligned with fiduciary duties and transparent for LP stakeholders.

    Our firm’s capital advisory services encompass the entire lifecycle of NAV financing, from initial eligibility analysis and lender identification to term negotiation and closing. With access to extensive institutional networks and deep expertise in asset-backed structures, we help sponsors navigate the complexities of these loans.

    Fundamentals of NAV Financing and Fund-Level Leverage

    Building on the overview of fund capital strategies, we now examine two core forms of fund-level leverage: subscription lines and NAV financing. Fund-level leverage refers to the strategic use of debt by a fund itself, most commonly through subscription lines or NAV-based credit facilities.

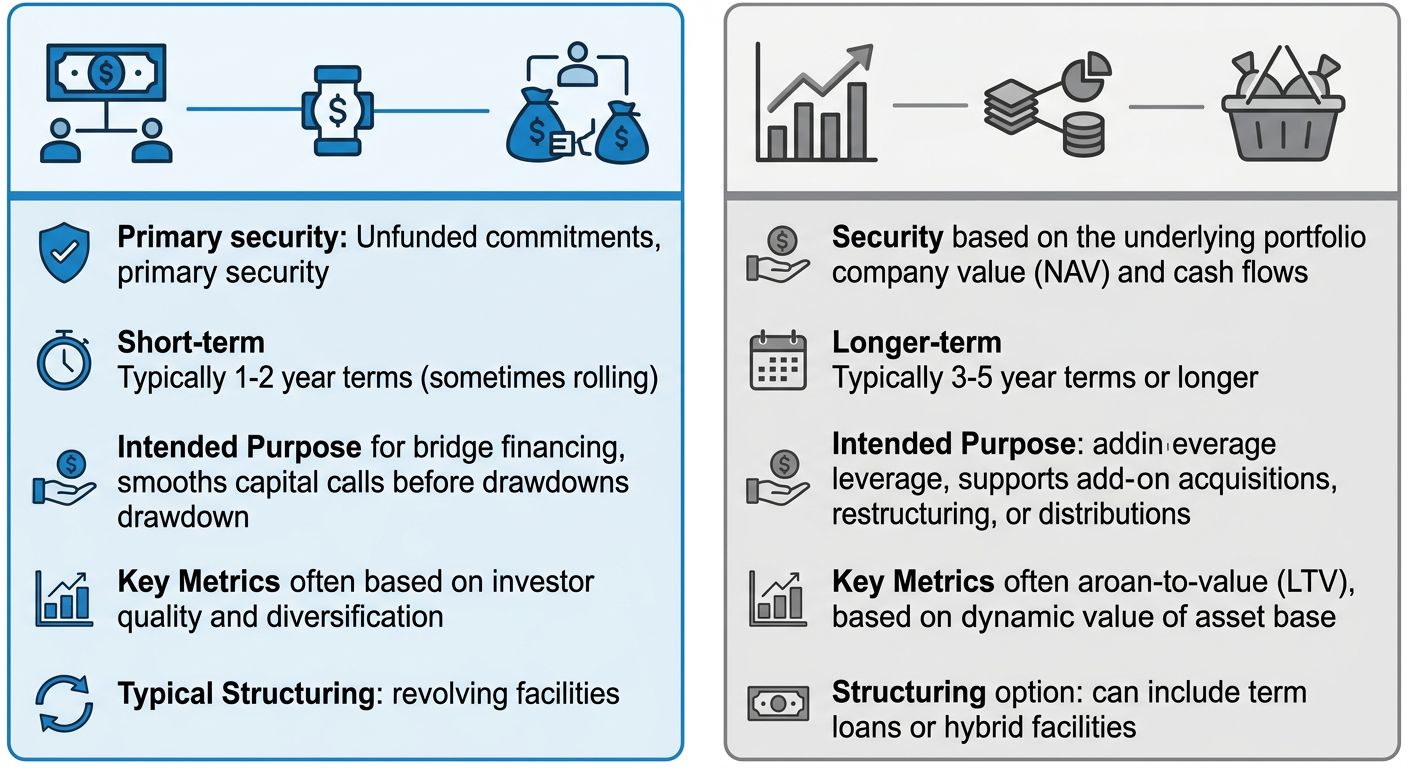
    Comparison: Subscription Lines vs. NAV Financing Facilities

    The following table provides a direct comparison of these two prevalent forms of fund-level leverage:

    FeatureSubscription LineNAV Financing
    PurposeFund capital callsFund distributions and acquisitions
    CollateralUnfunded commitmentsPortfolio company value
    Typical Terms1-2 years3-5 years
    Two-column comparison infographic contrasting subscription line financing with NAV financing terms.

    Comparison of subscription line and NAV financing terms and features for fund-level leverage.

    The Mechanics of NAV Loans: Structure, Growth Drivers, and Key Terms

    Growth Drivers Behind NAV-Based Lending in 2026

    DriverImpact on DemandExample Scenario
    LP Distribution PressureGPs need to return capital without exiting positionsBridge distributions with NAV facility
    Dry Powder OverhangUninvested capital pushes GPs to seek leverageUse NAV to fund follow-on acquisitions
    Regulatory EvolutionBasel IV makes subscription lines less attractiveNAV lines offer off-balance-sheet treatment

    Structuring NAV Loan Facilities: Key Components

    The architecture of a typical NAV financing in private equity facility rests on a few core components. The borrowing base is derived from the aggregate NAV of the portfolio companies. Lenders then apply an advance rate, typically ranging between 10 and 20 percent of that NAV.

    How NAV Financing Creates Value for Private Equity Funds

    The strategic value of NAV financing extends beyond liquidity. By using NAV loans, GPs can smooth fund-level returns and avoid fire sales of portfolio assets during market dislocations. Specialized debt advisory services from firms like Zaidwood Capital help navigate these structures.

    How Private Equity Firms Use NAV Financing for Distributions and Growth

    Use CaseTypical Advance RateCollateral Pool
    LP Distribution10-15% of NAVPortfolio companies
    Follow-On Acquisition20-30% of NAVTarget + existing portfolio

    Distributing Returns to Limited Partners via NAV Facilities

    Rather than selling assets at a suboptimal time, sponsors borrow against the fund’s net asset value and distribute the proceeds to investors.

    Using NAV Financing for Follow-On Acquisitions

    GPs draw on pre-arranged NAV financing facilities to move immediately when an acquisition opportunity emerges.

    Practical Steps to Secure a NAV Loan Agreement

    Securing a NAV facility requires a structured approach. Our corporate advisory services team at Zaidwood Capital negotiates with a network of over 3,000 lenders.

    Advanced Considerations in NAV Financing: Risk Management and Best Practices

    Risk FactorDescriptionMitigation Strategy
    Portfolio OverleverageAdding debt at fund levelMaintain conservative LTV ratios
    Valuation VolatilityNAV fluctuations affect borrowingRegular mark-to-market

    Common Questions About NAV Financing in Private Equity

    What is NAV financing in private equity? It is a form of fund-level leverage secured against a portfolio’s net asset value.

    Maximizing Fund Returns with Strategic NAV Financing

    At Zaidwood Capital, our debt advisory and capital formation capabilities support general partners in designing tailored financing structures.

    Resources

  • Commercial and Industrial Loans: Complete Guide for Businesses

    Table of Contents

    Understanding Commercial and Industrial Loans

    Commercial and industrial loans — commonly referred to as C&I loans — are short-to-medium-term financing solutions designed to fund a company’s daily operations, working capital needs, or capital expenditures. These instruments form a core part of corporate debt financing, and businesses can access them on either a secured or unsecured basis.

    In practice, companies qualify for C&I loans through one of two primary frameworks: asset-based lending or cash flow financing. Asset-based lending centers on the quality of a borrower’s collateral, such as inventory, equipment, or accounts receivable. Cash flow financing, by contrast, emphasizes the strength of historical and projected revenue streams.

    According to Zaidwood Capital’s own advisory resources, institutional investors evaluate applicants using additional metrics — including a detailed business plan, audited financial statements, and multi-year cash flow projections — before matching a company with an appropriate lender. While banks have long dominated this space, a growing pool of institutional investors now provides business loans for commercial purposes, offering a viable alternative for mid-market and growth-stage firms.

    Zaidwood Capital’s Debt Advisory practice helps businesses navigate these two qualification models, acting as a bridge to institutional capital sources. Through its platform, Zaidwood Capital provides global lending services that connect companies with the right C&I lending partners, ensuring a structured and transparent path to financing.

    Commercial and Industrial Loans vs. Other Financing Options

    While the previous section outlined what C&I loans are, this section helps you distinguish them from other common financing products. Understanding the distinctions between commercial and industrial loans, commercial real estate loans, and equipment financing is essential for any business owner evaluating the right capital structure. Each product is designed to meet fundamentally different business needs, from funding day-to-day operations to acquiring major assets. At Zaidwood Capital, we help clients navigate this landscape, leveraging our advisory expertise and access to over 4,000 institutional investors to secure the right financing for their unique situation.

    C&I Loans vs. CRE vs. Equipment Financing
    FeatureCommercial & Industrial LoansCommercial Real Estate LoansEquipment Financing
    Primary Use CaseWorking capital, inventory, operational expensesAcquiring, developing, or refinancing real propertyPurchasing machinery, vehicles, or technology
    Collateral TypeReceivables, inventory, equipmentReal estate asset being financedEquipment being acquired
    Repayment TermShort to medium term (1–5 years)Long term (10–30 years)Medium term (3–10 years)
    Interest Rate TypeFixed or floating, tied to working capital cyclesFixed or floating, typically lower spreadsFixed or floating, often with equipment retention clauses

    The primary use case immediately highlights the distinct purpose for each loan. Commercial and industrial loans are the go-to solution for fueling organic growth, covering payroll, and managing seasonal inventory swings. In contrast, commercial real estate loans are structured for the long-term acquisition or development of property, reflecting the extended lifespan and stable value of real estate assets.

    When we look at collateral, C&I loans typically rely on a company’s assets like accounts receivable, inventory, and existing equipment. This differs significantly from CRE loans, where the property itself serves as collateral, and equipment financing, where the newly purchased machinery, vehicles, or technology secures the debt. This collateral structure directly influences the repayment term, where C&I loans often operate with shorter 1-5 year horizons aligned with operational cycles, whereas CRE loans can amortize over much longer periods of 10 to 30 years.

    These differences underscore why there is no single “best” option—only the right instrument for a specific business objective. Our advisory process, highlighted on our Raise platform, involves a detailed review of a company’s financial standing, cash flow projections, and strategic goals to match you with appropriate lending structures.

    Comparison of C&I loans, commercial real estate loans, and equipment financing options.

    Understanding these differences is the first step. The next section will walk you through the qualification process for a C&I loan. We encourage you to review the details carefully, and when you’re ready to explore how a tailored debt solution can support your growth, you can Book A Call with our team.

    This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to transact. This is not investment advice; please consult your legal, tax, and financial advisors before making decisions.

    Collateral, Eligibility, and Loan Structuring for C&I Lending

    Beyond the basic loan purpose, successful C&I financing depends on three pillars: collateral, borrower eligibility, and loan structure. For businesses seeking commercial and industrial loans, understanding how lenders assess each of these areas is essential to securing terms that align with operational needs and growth goals. Our advisory team at Zaidwood Capital helps companies navigate these criteria, drawing on institutional requirements to build a strong lending case.

    Types of Collateral in C&I Lending

    The collateral securing the facility is a primary driver of advance rates and overall credit appetite. Lenders evaluate asset quality, liquidity, and valuation risk to determine how much they are willing to advance against each class. The table below summarizes the most common collateral types accepted in C&I loans, alongside their typical advance ranges and how institutional lenders generally view each asset class.

    Accounts receivable financing consistently receives the most favorable treatment, with advance rates reaching 70 to 90 percent. Because these assets convert to cash relatively quickly, they represent the most liquid form of collateral in C&I lending. Inventory, by contrast, carries more uncertainty. Advance rates of 30 to 60 percent reflect obsolescence risk, shelf-life concerns, and the challenge of liquidation if a borrower defaults. Equipment and machinery can provide solid collateral support at 50 to 80 percent of appraised value, provided the assets are well-maintained and have a clear secondary market. Real estate, while strong, is often carved out for commercial real estate-specific products rather than traditional C&I lines.

    Lender Eligibility Criteria

    Institutional lenders apply a consistent set of financial metrics to gauge a borrower’s ability to service C&I obligations. Per Zaidwood Capital’s guidance on asset-based lending, a debt-service coverage ratio of 1.25x or higher is a typical baseline. This means the company’s operating cash flow should cover all scheduled debt payments with a comfortable margin. Lenders also examine liquidity through the current ratio, generally expecting it to remain above 1.0x, though stronger ratios improve negotiating power.

    Beyond ratios, the documentation package is critical. Institutional investors require audited financial statements covering at least the last three fiscal years, detailed accounts receivable aging reports, and third-party inventory or equipment appraisals. The U.S. Securities and Exchange Commission’s reporting standards underpin many of these requirements, ensuring that the financial information lenders rely on meets a recognized threshold of accuracy. Our role is to assemble and present this package in a format that aligns with how institutional credit committees evaluate risk.

    Loan Structuring: Rates and Terms

    Once collateral and eligibility are confirmed, the loan structure defines how the capital is priced and repaid. Interest rate choice is often the first decision point. Variable-rate loans are typically tied to the Secured Overnight Financing Rate, or SOFR, plus a spread that reflects the borrower’s credit profile and transaction size. While this structure can offer lower initial costs, payments fluctuate with market conditions. Fixed-rate loans carry a premium for the interest-rate certainty they provide, making them attractive for companies that prioritize predictable budgeting over potential savings in a declining rate environment.

    Repayment terms can be just as important as the rate itself. For businesses with uneven revenue cycles, seasonal or deferred payment structures are often built into the agreement. For capital-intensive purchases, equipment financing can be structured with seasonal or deferred payment plans, linking directly to our detailed FAQ. This flexibility allows borrowers to match debt service to cash generation, reducing strain during off-peak periods. With the collateral and structure defined, the next step is preparing a complete application package. To discuss how these terms can be tailored to your specific situation, we invite you to Book A Call for a custom quote.

    Strategic Uses of C&I Loans: Working Capital and Equipment Financing in Practice

    Now that we understand the broad benefits of C&I loans, let’s explore two of their most strategic applications in practice. Commercial and industrial loans provide the structured capital that businesses need for specific operational and growth objectives, from managing day-to-day cash flow to acquiring essential equipment. At Zaidwood Capital, our Debt Advisory team helps clients navigate these applications, structuring solutions that align with both immediate needs and long-term business plans.

    The following table matches common business needs to the appropriate loan structure, documentation requirements, and typical use cases.

    Common Collateral Types for C&I Loans
    Collateral TypeDescriptionTypical Advance RateLender Preference
    Accounts ReceivableInvoices from creditworthy customers70%–90%Highly preferred due to liquidity
    InventoryRaw materials, WIP, finished goods30%–60%Moderate; depends on obsolescence risk
    Equipment & MachineryFixed assets with appraised value50%–80%Good; stable collateral if well-maintained
    Real EstateCommercial or industrial property60%–75%Strong, but often used in CRE-specific products

    These three structures cover the most frequent strategic uses of C&I loans we encounter in our advisory work. Selecting the right one depends on your specific objective, the collateral available, and the documentation you can provide to support the request.

    Financing Working Capital with C&I Loans

    For businesses facing seasonal demand fluctuations or uneven cash flow cycles, working capital financing through an asset-based revolving line of credit offers a practical solution. This structure uses your company’s accounts receivable aging and inventory reports as collateral, creating a borrowing base that increases as your operational assets grow. Rather than waiting for customer payments to arrive, you draw against the value of outstanding invoices and on-hand inventory to cover immediate needs.

    Qualifying for this type of facility requires clear cash flow projections that demonstrate your ability to service the debt across different points in your business cycle. Lenders reviewing your application will want to see consistent patterns in your A/R aging, turnover rates on inventory, and realistic forward-looking projections that account for both peak and off-peak periods.

    A real-world example helps illustrate how this works in practice. Consider a wholesale distributor in Baltimore that experiences a predictable seasonal inventory buildup ahead of the summer months. To purchase stock and cover operating expenses during the slower winter period, the business establishes an asset-based line of credit secured by its receivables and inventory. This structure provides the liquidity needed to make supplier payments on time without depleting cash reserves, and the credit line contracts as receivables are collected, keeping the cost of capital aligned with actual usage.

    All documentation and loan structuring must comply with relevant securities regulation and investor protection standards where applicable. For the working capital example above, the key documents needed include:

    • Accounts receivable aging reports showing outstanding invoice balances and due dates
    • Inventory reports detailing stock levels, valuation, and turnover rates
    • Cash flow projections covering seasonal peaks and troughs

    Equipment Financing: A Practical Application

    Commercial and industrial loans also provide a structured path for acquiring machinery, vehicles, or IT infrastructure without depleting working capital. Equipment financing typically takes the form of a term loan secured by the purchased asset itself, meaning the equipment serves as collateral for the loan. This approach preserves liquidity while allowing the business to put the new asset to productive use immediately. According to internal resources from Zaidwood Capital, the process follows a clear, step-by-step sequence.

    Start by obtaining a professional equipment appraisal to establish the fair market value of the machinery you want to purchase. Next, secure a detailed invoice or purchase order from the vendor that specifies the equipment, pricing, and delivery terms. With these documents in hand, our Debt Advisory team can structure the term loan to match the useful life of the equipment, with repayment terms that align to your projected cash flow from using the asset.

    Businesses with seasonal revenue patterns can also benefit from structured flexibility in their equipment financing. In Baltimore, a company that generates the majority of its revenue during the summer tourism season can arrange a payment schedule with higher installments during peak months and reduced or skipped payments in the winter. This alignment ensures that debt service never outpaces available cash flow. Documentation best practices for equipment financing applications include:

    • Equipment appraisal establishing fair market value
    • Detailed invoice or purchase order from the vendor
    • Two to three years of business financial statements and tax returns
    • Business plan or statement outlining the intended use of the financed equipment

    With these structured applications in mind, we can now examine how businesses and advisors proceed through the full lifecycle of a C&I loan transaction.

    Optimizing Financial Health with Commercial and Industrial Loans

    A core component of debt advisory is helping companies optimize their financial health through commercial and industrial loans, a category of short-to-medium-term financing designed to fund day-to-day operations. C&I loans can be used for various purposes, from purchasing inventory and machinery to covering working capital needs. By strategically deploying these loans, businesses can maintain momentum without sacrificing equity. We work with our clients to structure C&I loans that enhance liquidity, building a stronger foundation for scalable growth.

    C&I loans are often structured as asset-based lending, secured by a company’s receivables or inventory. This approach unlocks capital tied up in current assets, improving cash flow without ownership dilution. For businesses with strong recurring revenue, cash flow financing serves as a complementary tool, allowing them to borrow based on their ability to generate predictable revenue streams. Institutional investors in our network, which comprises over 4,000 entities, can offer flexible terms that may not be available through traditional banks. According to our qualification framework, lenders evaluate collateral quality, EBITDA trends, and comprehensive business plans during the due diligence process.

    Our debt advisory team aligns each client’s C&I loan structure with its specific growth stage and operational cycles. By assessing financial statements, projected cash flows, and expansion plans, we match companies with institutional lenders whose investment criteria align with their sector and deal size. This tailored approach ensures that the resulting capital structure supports working capital efficiency and positions the business for future capital raises. Our team has successfully raised over $800 million in financing solutions, leveraging access to more than $5 billion in deployable debt.

    Proper structuring of C&I loans can strengthen a company’s balance sheet and credit profile, while adherence to financial industry regulation and investor education standards helps ensure transparency in C&I loan agreements. We encourage businesses to discuss their C&I loan structuring needs with our debt advisory team.

    Now let’s address some common questions businesses have about commercial and industrial loans. The regulatory landscape is shaped significantly by federal oversight, with the FTC consumer and business protection division playing a key role. Our team emphasizes that awareness of these protections is a fundamental step in responsible commercial and industrial financing.

    What is the FTC’s role in C&I lending?

    The Federal Trade Commission enforces truth-in-lending requirements and prohibits unfair or deceptive acts against businesses. This oversight creates a baseline of borrower protection for C&I loans, ensuring lenders provide transparent terms and cannot engage in predatory practices.

    How can businesses evaluate lender credibility?

    Business owners should verify lender registrations, review financing terms carefully, and consult the FTC’s business guidance on lending to identify red flags. We advise our clients to avoid any lender unwilling to disclose clear, written documentation.

    What should borrowers know about collateral and guarantees?

    Many commercial and industrial loans require collateral or personal guarantees. The FTC’s truth-in-lending standards mandate that these obligations be clearly disclosed upfront, helping borrowers make informed decisions without hidden risk.

    For more detailed guidance on securing C&I financing, our team can help.

    Partnering with a Capital Advisory Firm for C&I Financing

    Navigating the complexities of commercial and industrial loans demands more than a strong balance sheet—it requires a partner who understands institutional lending at scale. Zaidwood Capital’s debt advisory team evaluates a company’s financial position, cash flow profile, and collateral base to structure tailored C&I financing solutions. By leveraging a network of over 4,000 investors and more than $15 billion in deployable capital, we streamline the transaction process and connect businesses to the right capital partners. Through our Full-Cycle M&A and capital advisory approach, we guide clients from initial due diligence through closing, ensuring every phase moves with precision.

    Securities are offered through Finalis Securities LLC, a registered broker-dealer. Zaidwood Capital LLC is not a registered broker-dealer, and no content herein constitutes an offer or solicitation of securities. Investments involve risk, and past performance does not guarantee future outcomes.

    Resources

  • Best Asset Based Lending for 2026: Top Companies Compared

    Best Asset Based Lending for 2026: Top Companies Compared

    Table of Contents

    Asset-Based Lending as a Strategic Financing Tool

    Beyond traditional cash-flow loans, asset-based lending offers a strategic alternative for companies seeking flexible, secured financing against their balance-sheet assets. The U.S. Securities and Exchange Commission defines collateral as an asset a lender accepts as security for a loan, including real estate, equipment, inventory, and accounts receivable—precisely the assets that underpin asset-based lending structures.

    Through asset-based lending, businesses can often achieve higher leverage than unsecured debt and benefit from lower interest rates because the loan is backed by tangible collateral. This approach is especially valuable for companies with strong asset bases but uneven earnings, as the financing capacity is tied to asset values rather than cash-flow metrics alone.

    Qualifying typically requires a disciplined institutional process. As outlined in our FAQ, investors commonly look for collateral coverage ratios—often 1.5x to 2.0x advance rates—together with audited historical financials, minimum EBITDA thresholds, and thorough asset-quality audits. These benchmarks help our team identify the right institutional match from a network of over 4,000 investors, including banks, credit funds, and specialty finance firms.

    Unlike cash-flow financing, which depends heavily on EBITDA, asset-based lending unlocks liquidity directly from receivables, inventory, equipment, or real estate. Many companies use both structures concurrently, blending them to optimize cost of capital and funding flexibility. Through our global lending services, we connect clients with institutional investors specializing in asset-based lending and other secured debt structures.

    Asset-based lending can fund acquisitions, bridge equity gaps, or provide seasonal working capital—but outcomes are not guaranteed and depend on asset quality and deal structure. While many companies qualify, each transaction is subject to investor approval and due diligence.

    In the following section, we explore how ABL can be structured alongside equity financing to maximize transaction efficiency.

    This is not an offer or solicitation; consult your advisor.

    Understanding Asset-Based Lending Fundamentals

    Having defined asset-based lending, let us examine its core mechanics and how it compares with traditional financing. Asset based lending is a secured financing facility where the borrowing amount is determined by the value of specific pledged assets rather than primarily by cash flow or credit history. This type of secured lending relies on four main asset classes: accounts receivable, inventory, equipment, and real estate, each valued with distinct advance rates that reflect their liquidity and liquidation potential.

    The following table highlights the key differences between asset-based lending and a traditional bank line of credit.

    Asset-Based Lending vs. Traditional Bank Line of Credit
    DimensionAsset-Based LendingTraditional Bank Line of Credit
    Collateral RequirementSecured by specific assets (AR, inventory, equipment, real estate)Often unsecured or blanket lien; may require personal guarantees
    Underwriting FocusAsset quality and liquidation value; less emphasis on cash flowCash flow, credit history, and overall financial health
    Funding SpeedTypically 2–4 weeks; faster for revolving facilitiesCan take 4–8 weeks or longer for approval and funding
    FlexibilityHighly flexible; borrowing base adjusts with asset levelsFixed credit limit; less responsive to asset fluctuations
    CovenantsFewer financial covenants; focus on asset reportingStrict financial covenants (debt service coverage, leverage ratios)

    An ABL facility emphasizes the quality and liquidation value of collateral, with fewer financial covenants and a borrowing base that flexes alongside asset levels. For businesses with strong collateral but variable cash flow, such as manufacturers, wholesalers, or distributors, secured asset lending often provides faster access to capital and greater responsiveness to seasonal or growth-driven asset fluctuations.

    Comparison infographic of asset-based lending versus traditional bank line of credit highlighting differences in security, funding timeline, and flexibility
    Comparing asset-based lending and traditional bank line of credit

    Underwriting in asset-backed financing concentrates on the quality, liquidity, and liquidation value of the pledged collateral. Advance rates vary by asset class, with accounts receivable typically commanding higher advance rates than inventory or equipment. This approach shifts reporting toward asset monitoring rather than strict debt service coverage ratios, making ABL accessible to companies that may not meet conventional bank criteria. For a broader perspective on financing options, our coverage of global lending services alternatives provides key considerations for borrowers comparing ABL with other structures.

    Deep Dive into Asset-Based Lending Structures and Collateral Types

    To understand how asset based lending works, it is essential to examine the four primary collateral types that underpin every ABL structure. Each asset class carries distinct risk profiles, valuation methodologies, and advance rate ranges that directly influence the amount of capital a business can access and the speed at which funds become available.

    Primary Collateral Categories and Their Characteristics

    In asset based lending, collateral types determine both eligibility and borrowing capacity. The U.S. Securities and Exchange Commission defines collateral broadly as assets pledged to secure a loan, and within ABL structures, lenders focus on four principal categories based on their liquidity and ease of valuation.

    Accounts receivable represent the most liquid and preferred collateral class. Lenders evaluate AR through aging reports that identify overdue invoices, dilution analysis that measures returns and allowances against gross sales, and concentration limits that cap exposure to any single debtor. Because receivables convert to cash through normal collection cycles, they carry the highest advance rates and fastest funding timelines.

    Inventory serves as a common but more complex collateral type. Valuation requires third-party appraisal that accounts for obsolescence risk, seasonal demand patterns, and turnover velocity. Finished goods ready for sale command stronger valuations than raw materials or work-in-progress, which have limited liquidation markets.

    Equipment and real estate round out the primary categories, with valuations based on orderly liquidation value and professional appraisal, respectively. Equipment financing benchmarks indicate ABL structures typically extend 50 to 80 percent of orderly liquidation value depending on age, condition, and secondary market demand. Real estate requires the most extensive due diligence, including title searches and environmental assessments.

    Loan-to-Value Determinants and Advance Rate Mechanics

    Loan-to-value ratios in asset based lending emerge from a lender’s assessment of advance rates, eligibility criteria, and concentration limits applied to each asset class. The LTV is not a fixed percentage but a calculated figure reflecting the lender’s confidence in recovering principal through liquidation of the pledged collateral.

    Collateral Types and Advance Rates in Asset-Based Lending
    Asset TypeTypical Advance RateValuation MethodLiquidity / Speed of Funding
    Accounts Receivable70–90% of eligible ARAging reports, dilution analysis, concentration limitsFast; funds available within days of invoice submission
    Inventory40–60% of appraised valueAppraisal by third-party; considers obsolescence and turnoverModerate; requires field exam and appraisal
    Equipment50–80% of orderly liquidation valueAppraisal based on age, condition, and secondary marketModerate; appraisal and documentation needed
    Real Estate60–75% of appraised valueProfessional appraisal, title search, environmental assessmentSlower; due diligence and legal process required

    Advance rates represent the percentage of an asset’s appraised or eligible value that a lender will fund. Accounts receivable command the highest rates at 70 to 90 percent of eligible receivables because they self-liquidate through customer payments. Inventory advance rates sit lower at 40 to 60 percent, reflecting the inherent risk of physical goods degradation and market fluctuation.

    Funding Speed and the Asset-Based Lending Process

    The timeline from application to funding in asset based lending varies considerably by asset type and the intensity of due diligence required. Borrowers who prepare documentation thoroughly and understand lender expectations can materially compress the timeline.

    The ABL due diligence process typically begins with a field exam, where auditors physically inspect assets, verify accounting systems, and test the accuracy of borrowing base reports. For AR-heavy structures, this involves confirming invoice validity and analyzing customer payment patterns. Businesses exploring global lending services alternatives can compare ABL timelines against other capital sources to determine the optimal structure.

    Practical Guide to Securing Asset-Based Lending for Growth and Acquisitions

    Now that you understand the fundamental structure and purpose of asset-based lending, it’s time to explore a practical guide for securing this flexible financing tool. For companies with strong balance sheets but uneven cash flow, asset-based lending provides a tactical pathway to fund growth initiatives and execute acquisitions.

    Preparing Your Business for an Asset-Based Lending Application

    • Compile Detailed Financial Statements: Gather at least three years of audited financial statements, including balance sheets, income statements, and cash flow reports.
    • Prepare Precise Asset Schedules: Create comprehensive, up-to-date schedules for all assets that will serve as collateral, including accounts receivable aging reports and inventory listings.
    • Assemble Due Diligence Materials: Organize corporate documents, tax returns, customer and supplier contracts, and legal records.

    Using Asset-Based Lending for Acquisitions and Growth

    Asset-based lending is a powerful engine for mergers and acquisitions, offering flexible structures that traditional cash-flow loans often cannot match. We consistently see clients use ABL facilities in three principal ways during M&A: Leveraged Buyouts, Post-Acquisition Working Capital, and Bridge Financing.

    Advantages of Asset-Based Lending for Corporate Growth

    For asset-rich companies, the strategic advantages of asset-based lending are significant and multifaceted. The structure is designed to support rapid scaling and operational flexibility, which is why it is often recommended for companies navigating high-growth phases.

    Asset-Based Lending vs. Alternative Debt Structures
    Debt StructureCollateral FocusTypical Cost (Interest + Fees)Best For
    Asset-Based LendingSpecific assets (AR, inventory, equipment, real estate)LIBOR/SOFR + 3–6%Working capital, growth, acquisitions with asset-rich borrowers
    Cash-Flow LoanGeneral business assets / blanket lienPrime + 2–5%Established companies with strong cash flow and credit history
    Mezzanine DebtSubordinated; often unsecured with equity warrants12–20% (including equity upside)Growth capital, acquisitions, buyouts for mid-market companies
    Equipment FinancingSpecific equipment being purchased6–12%Capital-intensive businesses acquiring machinery or vehicles

    This website is for informational purposes only and is not an offer, solicitation, or commitment to transact. It is not investment advice. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Advanced Considerations in Asset-Based Lending for M&A and Complex Transactions

    While ABL is versatile for general purposes, its application becomes more nuanced in M&A and complex deals. In an acquisition context, asset based lending serves as a senior secured facility, often structured to support working capital, bridge financing, or leveraged buyout (LBO) debt.

    Asset-Based Lending vs. Mezzanine Debt vs. Equity for M&A
    Financing TypeCost RangeDilution / ControlBest Use in M&A
    Asset-Based LendingSOFR + 3–6%No dilution; lender has lien on assetsSenior secured facility for working capital, bridge financing, or LBO debt
    Mezzanine Debt12–20% (including warrants)Minimal dilution; warrants may give equity upsideSubordinated layer to fill gap between senior debt and equity
    Equity Financing15–30%+ expected returnSignificant dilution; investors gain ownership and control rightsGrowth equity, buyouts, or when debt capacity is limited

    Frequently Asked Questions About Asset-Based Lending

    Q: What is asset based lending? Asset based lending is a secured financing structure where a business pledges balance-sheet assets such as accounts receivable, inventory, or equipment as collateral. Unlike traditional cash-flow lending that emphasizes credit scores and profitability, ABL focuses on the liquidation value of the pledged assets.

    Q: How does collateral work in an asset-based loan? Collateral is property offered to secure a loan—the U.S. Securities and Exchange Commission defines it as something a lender can seize if the borrower defaults. In asset-based lending, lenders first appraise the pledged assets and then set a borrowing base that reflects their realizable market value.

    Q: What are typical advance rates for asset-based loans? Advance rates vary by asset quality, but receivables commonly qualify for 70–85 percent and inventory for 50–60 percent of the appraised value.

    Leveraging Asset-Based Lending with Zaidwood Capital’s Debt Advisory Expertise

    Asset based lending uses a company’s receivables, inventory, and equipment as collateral, unlocking more flexible capital than unsecured debt. Our debt advisory team structures ABL facilities around your cash flow and collateral profile, connecting you to over 4,000 institutional investors and more than $15 billion in deployable capital. We engineer tailored terms that deliver higher leverage and greater flexibility than conventional bank loans—especially for growing or cyclical businesses.

    Resources

  • Asset-Based Lending: Complete Guide for Businesses

    Asset-Based Lending: Complete Guide for Businesses

    Table of Contents

    Asset-Based Lending: A Strategic Financing Option for Growth

    Asset-based lending (ABL) is a form of financing secured by a company’s assets, typically accounts receivable, inventory, equipment, or real estate. Unlike cash-flow-based loans that rely on credit history, ABL focuses on the collateral’s value, making it accessible even for businesses with limited operating history. Advance rates vary: receivables often command 80–90%, while inventory may secure 50–70% of its appraised value.

    ABL provides liquidity and flexibility through revolving credit lines that expand as your asset base grows, supporting working capital and growth initiatives. With faster funding than traditional loans, ABL helps companies seize opportunities without delay. At Zaidwood Capital, we leverage our network of 4,000+ institutional investors and access to over $15 billion in deployable capital to structure tailored ABL facilities. As a full-cycle M&A and capital advisory firm, we streamline the process from due diligence to closing. Our advisory team helps you evaluate asset eligibility and structure a facility that aligns with your strategic goals. By unlocking the value of your balance-sheet assets, ABL provides the working capital necessary for expansion, acquisitions, or seasonal cash-flow management.

    For companies exploring complementary solutions, we also facilitate venture debt to support growth. Contact us to Book A Call and discover how ABL can fuel your business expansion.

    Revolving Credit Facility (ABL)

    A Revolving Credit Facility (ABL) is an asset-based lending structure providing a secured line of credit backed by accounts receivable, inventory, and sometimes equipment. We use these facilities to supply working capital for seasonal inventory builds and growth initiatives. The borrowing base is recalculated monthly against pledged receivables and inventory to reflect current collateral. Companies with a PEO often combine it with an ABL facility for cash management.

    Inventory Financing

    Inventory financing is a type of short-term, asset-based lending that uses a company’s existing inventory as collateral to secure working capital. Businesses typically use it to purchase additional stock, bridge cash flow gaps, or capitalize on seasonal demand surges. Lenders advance a percentage of the inventory’s value—often 50% to 80%—and repayment occurs as the goods are sold. Through our global lending services debt advisory, we structure these inventory-secured arrangements to secure optimal advance rates and covenants for your business.

    Accounts Receivable Financing

    Accounts receivable financing, a form of asset-based lending, lets businesses borrow against unpaid invoices rather than waiting 30 to 90 days for payment. Companies sell or collateralize receivables to receive a percentage of the invoice value upfront. This asset-backed solution suits B2B firms, manufacturers, and wholesalers with extended cycles. Underwriting hinges on payer creditworthiness, not the borrower, and we help clients unlock this flexible path to improved working capital.

    Equipment Financing

    Within our debt advisory practice, we offer specialized equipment financing solutions. Equipment financing is a common form of asset-based lending where the equipment itself serves as collateral, enabling businesses to acquire needed assets. Structures include loans for ownership or leases for usage rights, applicable to machinery, vehicles, technology, and medical equipment. We advise on structuring and connect clients with appropriate capital sources, and all terms are custom-quoted based on credit, equipment type, and market conditions. Book A Call for a personalized consultation.

    Asset-Based Term Loan

    Within asset-based lending, an asset-based term loan is a single-draw, asset-backed loan commonly used for business acquisitions, capital expenditures, and debt refinancing. Unlike a revolving line, it provides a lump sum with a fixed repayment schedule. Loan amounts are based on collateral values, typically 70–85% of accounts receivable and 50–70% of equipment appraisals. At Zaidwood Capital, we structure these solutions by leveraging our institutional network.

    Purchase Order Financing

    Purchase Order Financing helps businesses fulfill large orders when working capital is tight. A lender pays the supplier, and the business repays after the customer invoice is settled. Unlike traditional loans, approval depends on the purchase order’s value, not credit history. We offer it through our debt advisory network, alongside asset-based lending and tailored structured solutions. Contact us to discuss how we can bridge your cash-flow gaps.

    Warehouse Lending

    Warehouse lending is a specialized form of asset-based lending—a short-term revolving facility that funds asset accumulation, such as loan origination, before permanent takeout financing is arranged. Through our Debt Advisory practice, we assist clients in structuring and sourcing these collateralized facilities. Leveraging our network of over 4,000 institutional investors, we identify appropriate warehouse lending partners. This solution focuses on liquidity and speed, not long-term capital, and is one of several debt options we help clients evaluate.

    Bridge Loan (Secured by Assets)

    A bridge loan is a short-term, asset-backed financing solution that helps you bridge a funding gap, secured by collateral like real estate, inventory, or receivables. Common uses include M&A, recapitalizations, and pending asset sales. At Zaidwood Capital, we provide bridge loan advisory as part of our debt advisory services, within asset-based lending. We leverage our network and expertise to structure flexible, fast-execution financings, streamlining transactions.

    Structured Asset-Based Finance

    Structured asset-based finance is a form of asset-based lending secured by assets like accounts receivable, inventory, equipment, or real estate. It delivers working capital and liquidity without requiring asset sales or equity dilution. As a full-cycle M&A and capital advisory firm, we facilitate structured asset-based finance through our network of over 4,000 institutional investors, enabling companies to unlock capital while preserving ownership.

    Special Situations ABL

    Beyond standard asset-based lending, we also advise on special situations that demand tailored debt solutions:

    • Turnaround and distressed scenarios where collateral is impaired or operations are restructuring
    • Cross-border structures involving multiple jurisdictions and currency considerations
    • Growth-stage transactions where companies hold unconventional asset bases such as intellectual property or receivables
    • Time-sensitive acquisition or bridge financing needs

    These mandates reflect our Full-Cycle M&A and capital advisory approach.

    Asset-Based Lending Options at a Glance

    To help you compare options at a glance, we’ve summarized key asset-based lending tools:

    Comparison of Asset-Based Lending Tools
    Asset TypeAdvance RateBest ForTypical Term
    Accounts Receivable, InventoryUp to 85% on AR, 50-65% on InventoryWorking capital needsRevolving
    Inventory50-65%Seasonal inventory buildup6-12 months
    Accounts ReceivableUp to 85%Cash flow accelerationRevolving
    Equipment70-80% of appraised valueCapital equipment purchases3-7 years
    Multiple asset classesVariesLarger, more complex facilities2-5 years
    Purchase ordersUp to 100% of PO valueFulfilling large ordersShort-term
    Residential mortgage loansVariesMortgage lendersShort-term
    Real estate, receivables, other assetsVariesBridge financing gaps6-24 months
    Diverse asset poolsCustomComplex capital structures1-5 years
    Distressed or unique assetsNegotiatedRestructuring or special situationsShort-to-medium term

    Please note that the advance rates shown are typical market ranges; actual terms depend on the specific lender, your financial profile, and asset quality. At Zaidwood Capital, we work with you to structure the right facility, using our experience with over 300 deals and a network of 4,000+ investors. The following sections provide a detailed look at each asset-based lending option.

    Grid of 10 minimalist icons representing asset-based lending options including revolving credit, inventory financing, and equipment financing, each with a short label, on a blue and gray background.

    At-a-glance overview of asset-based lending options across 10 financing types.

    Unlocking Growth with Asset-Based Lending

    Asset-based lending (ABL) allows companies to secure financing using hard assets — receivables, inventory, or equipment — as collateral. Unlike conventional unsecured loans, ABL focuses on the tangible value of the assets rather than solely on credit history. By unlocking embedded balance-sheet value, ABL can provide faster access to capital than traditional underwriting processes.

    Typical use cases encompass working capital smoothing, growth financing, refinancing, and acquisition support. Eligible collateral often includes accounts receivable, inventory, machinery, and real estate. This structure benefits companies with solid asset bases even when cash flow metrics do not meet conventional bank standards. This flexibility makes ABL an attractive option for companies in transition or experiencing rapid expansion.

    At Zaidwood Capital, we design custom ABL facilities as part of our debt advisory offering. Drawing on a network of over 4,000 investors and $15 billion in available capital, we aim to secure competitive, tailored terms for each engagement. Our full-cycle M&A and capital advisory platform ensures that asset-based lending serves as a strategic growth lever, and we can help you explore how ABL complements equity, mezzanine, or other debt instruments in your capital stack.

    Resources

  • Commercial Lending: Complete Guide for 2026

    Commercial Lending: Complete Guide for 2026

    Table of Contents

    Understanding Commercial Lending Options for Business Growth

    Building on our full-cycle M&A and capital advisory capabilities, commercial lending through our debt advisory practice connects businesses with tailored financing solutions. We offer a comprehensive suite of debt financing options, including mezzanine debt, venture debt, equipment financing, and asset-based lending, each designed to support distinct growth objectives. As part of our global lending services, we leverage proprietary data access through our Sovereign Data Nexus and the Velocity Matrix to match clients with the right institutional capital from a network exceeding 4,000 investors with over $15 billion in deployable capital.

    Our debt advisory team structures each business lending solution to fit specific use cases: mezzanine debt for growth capital and acquisitions, venture debt for startups seeking non-dilutive runway, equipment financing for asset purchases without large upfront costs, and asset-based lending for working capital secured by receivables or inventory. We do not lend directly; rather, we serve as a debt advisor, facilitating access to customized capital access strategies through our Precision Catalyst approach. Beyond debt, our equity advisory services offer additional growth pathways for companies exploring minority or majority investment structures.

    Traditional Banks vs Private Commercial Lenders

    Businesses exploring financing quickly encounter two distinct paths: traditional banks and private commercial lenders. While both provide capital, their processes and priorities differ significantly. Banks rely heavily on personal credit scores, debt-service coverage ratios, and a multi-year operating history. Their underwriting is methodical, often taking months to close, and personal guarantees are typically required.

    In contrast, private commercial lenders prioritize the value of your assets and the strength of your cash flow over rigid credit metrics. This allows them to structure asset-based lending and cash-flow financing with greater speed—often delivering capital in weeks rather than months. Terms can be tailored with flexible features like interest-only periods or balloon payments, and covenants are aligned with business performance rather than static ratios. Through our institutional network, we connect companies to lenders offering global lending services that span multiple industries and jurisdictions, typically requiring fewer personal guarantees.

    For growing businesses, private lending offers a viable alternative when traditional bank criteria feel restrictive. Rather than a one-size-fits-all approach, we match firms with institutional investors who understand their unique story. In the next section, we’ll walk through the straightforward application process to access this network.

    Comparing Lending Features: Banks, Private Lenders, and Advisory Firms

    The world of commercial lending offers businesses more choices than many realize, extending well beyond the traditional bank loan. While banks remain a cornerstone for many, private lenders and boutique advisory firms have carved out distinct roles that accommodate diverse funding needs and timelines. Our internal research at Zaidwood Capital LLC provides a clear framework for understanding these differences.

    The following table offers a side-by-side comparison of key features that matter most when evaluating a lending partner.

    Commercial Lending Channel Comparison

    Commercial Lending Channel Comparison
    FeatureTraditional BanksPrivate LendersBoutique Advisory Firm (Zaidwood Capital)
    Eligibility CriteriaStrict credit history, collateral, cash flowMore flexible, emphasis on asset qualityAdvisory-based; connects to suitable institutional lenders
    Speed of FundingWeeks to monthsDays to weeksExpedited through network of 4,000+ investors
    Documentation RequiredExtensive financial statements, tax returns, business plansModerate documentation, focus on asset valuationAdvisor guides documentation preparation
    Collateral RequirementsTypically secured; unsecured options limitedOften asset-backed; flexible structuresHelps identify optimal collateral structure
    CustomizationStandardized loan productsCustomizable termsTailored advisory for each engagement
    Access to CapitalLimited to bank’s balance sheetFund size depends on investor poolAccess to $15B+ deployable capital network

    Eligibility Criteria diverges sharply across these channels. Banks enforce rigid standards around credit scores, cash flow history, and asset coverage, which can often exclude even profitable companies in growth phases. Private lenders pivot the focus toward asset quality, creating a pathway for Asset-Based Lending that uses your company’s own holdings as the primary qualifier. As a boutique firm, Zaidwood Capital advisory bridges these worlds by connecting businesses with institutional lenders whose criteria align with the client’s specific profile, rather than forcing a square peg into a round hole.

    Speed of Funding is often the deciding factor in choosing a commercial loans provider. A traditional bank’s timeline, stretching from weeks to months, can cause companies to miss strategic windows. Private lenders compress this to a matter of days by streamlining their evaluation. We expedite this further by leveraging our network of over 4,000 investors, targeting a closing in under 60 days for mid-market transactions. This velocity can be a competitive advantage in time-sensitive scenarios.

    Three-column comparison infographic showing six lending features across Traditional Banks, Private Lenders, and Boutique Advisory Firms, using blue, green, and orange icon-cards.

    Comparison of lending features across bank, private, and advisory lending options.

    The Documentation Required scales dramatically depending on the source. Banks require a deep dive into comprehensive financial statements, tax returns, and detailed business plans. Private lenders reduce the burden, zeroing in primarily on asset valuation and condition. Our role in the advisory process shifts this burden from the borrower to us: we guide the preparation and assembly of all necessary documentation, ensuring it meets the exacting standards of institutional finance and facilitating a smoother due diligence cycle.

    Key differentiators in the business lending landscape can be summed up in three points: the speed of execution, the flexibility of the structure, and the depth of the capital pool. We provide advisory solutions that are fully tailored, helping to construct an optimal collateral package rather than presenting a one-size-fits-all mandate. With access to over $15 billion in deployable capital, our clients are not limited to a single balance sheet. In the next section, we’ll explore how to determine which of these channels best fits your company’s specific strategic and financial goals.

    This content is for informational purposes only and is not an offer, solicitation, or investment advice. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC.

    Pricing Structures in Commercial Lending

    Pricing in commercial lending is highly structured and reflects a combination of market benchmarks, credit risk, and transaction complexity. We at Zaidwood Capital approach every engagement with a custom-quote philosophy, recognizing that no two capital structures are identical. The core components include an interest rate basis, which may be fixed-rate for the full term or floating-rate tied to a benchmark like SOFR, plus a margin spread that compensates the lender for the specific risk profile of the borrower.

    Beyond the interest component, business lending arrangements typically carry a schedule of fees. These can include upfront arrangement or commitment fees, legal and due diligence costs, and ongoing service or agency charges. The overall debt pricing structure is influenced by the quality of collateral, loan tenor, and prevailing market conditions. Senior secured facilities generally command the tightest margins, while mezzanine and venture debt tranches incorporate higher spreads to reflect their subordinated or cash-flow-dependent nature.

    Our process ensures that commercial loan pricing parameters are calibrated to your specific situation. According to the firm’s FAQ, we require audited financials, multi-year projections, and a detailed business plan to begin a pricing discussion. This thorough due diligence lets us model appropriate capital structures before delivering a tailored quote. All engagements start with a confidential consultation where we outline preliminary pricing frameworks and the path forward.

    This is for informational purposes only and does not constitute an offer or commitment to lend. Consult your advisors.

    Choosing the Right Commercial Lending Path for Your Business

    Choosing the right commercial lending path can determine the success of your growth plans. The main structures — term loans, lines of credit, equipment financing, and asset-based lending — each serve distinct purposes.

    A term loan provides a fixed amount with scheduled repayments, while a line of credit offers flexible working capital. Equipment financing ties repayment to the asset’s life, and asset-based lending uses receivables or inventory as security. Each option balances liquidity, predictability, and asset utilization.

    Your decision should hinge on your business stage, cash flow stability, available collateral, and growth outlook. Early-stage firms may explore venture debt; mature companies often use term loans or credit lines.

    We help you navigate these choices through debt advisory services, including mezzanine, venture debt, equipment financing, and asset-based lending. With access to 4,000+ investors and $15B+ in capital, we provide objective guidance — but we never guarantee specific outcomes or rates. Our team evaluates your capital needs, repayment capacity, and collateral profile to recommend structures that suit operational realities.

    Book a call to discuss your commercial lending strategy with our team.

    Taking the Next Step in Your Commercial Lending Journey

    In commercial lending, the right advisory partner makes all the difference. Zaidwood Capital’s full‑cycle M&A and capital advisory services provide a clear path through complex financing landscapes. Our team leverages a network of 4,000+ institutional investors and an aggregate transaction volume of $24.4B+ to connect businesses with optimal lending solutions.

    We work closely with clients to navigate debt and equity options, backed by comprehensive due diligence and strategic documentation. Whether you’re exploring commercial financing or need to raise capital, we provide the clarity and execution speed you need. With over 80 years of collective experience, our team brings deep market insight to every engagement.

    Ready to move forward? Book A Call today to discuss your unique goals and discover how our advisory services can support your business growth.

    Resources

  • Choosing the Right Mezzanine Debt Structures: Key Considerations

    Choosing the Right Mezzanine Debt Structures: Key Considerations

    Table of Contents

    Understanding Mezzanine Debt Structures

    Mezzanine debt structures are hybrid financing instruments that sit between senior secured debt and common equity in a company’s capital stack. Often viewed as junior capital, mezzanine debt fills the gap when conventional senior loans reach their capacity. This content is for informational purposes only and is not an offer, solicitation, or investment advice. Zaidwood Capital LLC is not a registered broker-dealer.

    Mezzanine debt is a form of subordinated debt financing that typically does not require hard collateral. Instead, lenders are compensated with a higher interest rate and an equity kicker—often warrants or conversion rights—which provides upside participation in the borrower’s success. This combination of debt and equity features makes it a flexible tool for companies needing capital beyond what senior lenders will provide. By taking a junior position, mezzanine lenders assume greater risk but also capture more of the company’s value creation.

    Mezzanine debt structures commonly bridge funding gaps in leveraged buyouts, acquisitions, and growth capital transactions where senior debt limits are reached but equity dilution is undesirable. Unlike unitranche debt, which combines senior and mezzanine layers into a single facility, traditional mezzanine structures remain clearly subordinated and offer lenders deeper equity participation.

    Engaging a debt advisor can simplify the sourcing and negotiation of mezzanine terms. At Zaidwood Capital we connect clients to a network of over 4,000 institutional and private investors with more than $15 billion of deployable capital, streamlining the process. Zaidwood Capital’s global lending services provide access to institutional investors and specialized debt funds that may not be reachable through conventional banking channels. This access is critical for firms that lack existing relationships with mezzanine providers.

    Of course, every transaction depends on the company’s specific situation, and no outcome is guaranteed. Our role is to present options, not promise particular results.

    Mezzanine Debt in the Capital Stack: Position, Pricing, and Purpose

    Within this layered structure, mezzanine debt occupies a distinctive position as the bridge between senior secured loans and pure equity. We view mezzanine debt structures as a flexible layer that is structurally subordinated to senior lenders but holds priority over equity holders in repayment and asset claims. This middle placement means mezzanine investors take on a moderate-to-high risk profile, reflecting the fact that they are repaid only after senior obligations are satisfied, yet before any residual value flows to equity.

    The following comparison table highlights how mezzanine fits within the capital stack alongside senior debt and equity:

    Mezzanine vs Senior Debt vs Equity in the Capital Stack
    AttributeSenior DebtMezzanine DebtEquity
    Position in StackFirst claim on assets and cash flowSubordinated to senior, senior to equityLowest priority, residual claim
    Risk LevelLowModerate to highHighest
    Typical ReturnLIBOR + 200-400 bps10-20% blendedVariable, target IRR 20%+
    Control RightsCovenants onlyMay include warrants or conversionVoting rights and board seats

    Senior debt holds the first claim on cash and assets; equity sits at the bottom targeting 20%+ IRRs and holding voting control. Mezzanine debt sits between them, subordinated to senior but senior to equity, typically offering a 10–20% blended return through interest, PIK, and equity-linked features such as warrants or conversion rights. Its control rights can include board observation or conversion triggers, providing a middle path.

    The 10–20% blended return commonly seen in mezzanine debt structures arises from a mix of contractual interest payments, payment-in-kind (PIK) accruals, and equity upside through warrants or conversion rights. Because mezzanine sits below senior debt in the capital stack, its risk profile is elevated; investors accept that they will be repaid only after all senior obligations are met. For this reason, mezzanine debt is often categorized as subordinated debt financing. In certain transactions, lenders may combine the senior and mezzanine layers into a single unitranche debt facility, streamlining documentation and reducing execution complexity. At Zaidwood Capital, we evaluate these structures against a company’s cash flow projections and strategic ambitions to build capital stacks that align risk and return profiles with long-term objectives.

    Mezzanine financing is most frequently used when a company’s senior debt capacity is exhausted, yet equity dilution is undesirable. Typical use cases include growth capital for expansion, acquisition financing, leveraged buyouts, and recapitalizations where flexible capital bridges the gap between senior debt and equity without ceding control. At Zaidwood Capital, our global lending services encompass mezzanine debt as a core component of the capital solutions we design—integrating subordinated debt financing and, where appropriate, unitranche debt structures that combine senior and mezzanine layers to streamline execution. This approach allows us to tailor risk-return profiles that match a company’s cash flow dynamics and strategic goals.

    While senior debt offers security and equity captures upside, mezzanine debt bridges the two with a balanced risk-return profile, providing essential flexibility for growing companies.

    This website is for informational purposes only and is not investment advice.

    Structuring Mezzanine Debt for Acquisitions and Growth

    As we move from senior to mezzanine structures, the role of hybrid capital becomes central to bridging funding gaps in complex transactions. Mezzanine debt structures occupy a unique position in the capital stack, sitting below senior obligations but above equity. At Zaidwood Capital, we structure these instruments as part of our full-cycle debt advisory, delivering flexible junior capital solutions for acquisitions and growth. While we leverage our network of over 4,000 institutional investors to source capital, we are not a registered broker-dealer and do not offer investment advice — please consult your own advisors before making financing decisions.

    The following table compares three common junior capital solutions used in acquisition financing:

    Mezzanine vs Unitranche vs Subordinated Debt
    FeatureMezzanine DebtUnitranche DebtSubordinated Debt
    StructureTwo-tranche (senior + sub) or standaloneSingle blended loan (senior + mezzanine combined)Strictly junior to senior debt
    Pricing10-18% all-inLIBOR + 500-800 bpsLIBOR + 600-900 bps
    CovenantsIncurrence-based, may include equity kickerMaintenance covenants typicalLess restrictive than senior
    Best Use CaseAcquisition financing with hybrid return profileMid-market borrowers seeking simplified documentationBridge financing or recapitalizations

    Each solution serves a distinct purpose, and the choice depends on the sponsor’s appetite for complexity, covenant flexibility, and return targets.

    Typical Interest Rates and Terms in 2026

    Current market conditions make mezzanine financing particularly relevant, with all-in pricing typically ranging from 10% to 18%. This spread includes a cash pay component tied to benchmark rates — often LIBOR-based — plus payment-in-kind interest and an equity kicker in the form of warrants. According to Zaidwood Capital’s internal CADE FAQ, the precise split between cash and PIK depends on transaction risk, while the warrants enhance the lender’s yield to compensate for junior security. Upfront fees, prepayment penalties, and structuring charges are also common, and we work with borrowers to model these layers so the total cost of capital remains transparent. In 2026, sustained demand from private equity firms and family offices continues to support a borrower-friendly but disciplined underwriting environment.

    The Role of Mezzanine in Buy-Side Transactions

    Mezzanine debt structures shine in leveraged buyouts and growth-capital raises where senior debt capacity alone falls short of the required enterprise value. By layering a junior tranche, sponsors can increase total leverage without ceding control — an approach we use frequently when advising on buy-side mandates. For emerging markets m&a acquisitions, where projected transaction volumes may surge 15% annually, mezzanine provides a flexible bridge that absorbs country and currency risks while preserving equity upside. The equity kicker aligns lender and sponsor incentives, allowing the financing to behave almost as quasi-equity, which is valuable in high-growth sectors like fintech or renewables. Our debt advisory team draws on the firm’s CADE FAQ and transaction experience to calibrate the right mix of senior debt, mezzanine, and equity for each acquisition.

    Integrating with Unitranche and Subordinated Debt

    In more complex capital structures, mezzanine debt is often combined with unitranche debt or subordinated debt financing to optimize the cost and documentation burden. Unitranche — a single blended loan — appeals to mid-market sponsors with its simplicity and maintenance covenants, but it may lack the return-enhancing features of a standalone mezzanine piece. When we integrate mezzanine with subordinated debt financing, the subordinated layer acts as a bridge facility or recapitalization tool sitting just above equity, while the mezzanine tranche retains its hybrid character. This layered approach can lower the weighted-average cost of capital and satisfy both covenant-light investors and lenders seeking higher yields. Zaidwood Capital’s internal CADE FAQ highlights that such integrated structures are especially common in emerging-market M&A and resource-intensive sectors, where bespoke terms and patient capital are essential. Our role is to design the sequencing — senior, unitranche, mezzanine, subordinated — so that the overall package meets the client’s strategic and liquidity objectives.

    Practical Framework for Evaluating Mezzanine Financing Options

    With a clear understanding of mezzanine basics, we now present a practical evaluation framework. For executives and private equity sponsors, selecting the right financing structure is critical to maximizing returns and minimizing risk. Our advisory team at Zaidwood Capital has developed this decision-focused guide to help you assess whether mezzanine debt structures align with your acquisition strategy and capital stack requirements.

    When to Choose Mezzanine Over Senior Debt

    Senior debt typically reaches its limit at 3-4x EBITDA, constrained by collateral coverage and maintenance covenant requirements. When additional capital is needed to close a transaction or fund growth initiatives, but further senior lien capacity is exhausted, mezzanine financing becomes a strategic solution. Unlike senior lenders who require secured collateral, mezzanine providers accept an unsecured or subordinated position, relying on cash flow analysis rather than hard asset coverage. This flexibility proves essential when the target company has limited fixed assets but strong, predictable free cash flow.

    In our experience, the decision often comes down to a trade-off between cost and flexibility. While unitranche debt can offer a simpler, single-document structure that blends senior and subordinated tranches, it typically provides less flexibility than a bifurcated capital structure. A unitranche facility may restrict prepayment options and lack the warrant overlay that aligns mezzanine investors with equity upside. We recommend evaluating your specific covenant tolerance and exit horizon before choosing between these subordinated alternatives.

    Step-by-Step Structuring for Private Equity Deals

    Structuring mezzanine financing requires a methodical approach to balance the interests of sponsors, senior lenders, and subordinated investors. Our framework follows a five-stage process refined through over 300 completed transactions.

    Diagram showing five stages of a mezzanine financing evaluation process from initial mandate to post-closing monitoring with downward arrows connecting each stage

    Five-stage mezzanine financing evaluation process flow diagram

    The process begins with the initial mandate and underwriting phase, where we assess the target company’s credit profile, historical cash flows, and projected debt service capacity. This determines the appropriate sizing of the subordinated debt financing tranche, typically targeting a total leverage level of five to seven times EBITDA inclusive of senior debt.

    Next, term sheet negotiation addresses the critical economic and control terms. Warrant coverage—the equity kicker that enhances investor returns—is negotiated alongside the cash coupon and any payment-in-kind (PIK) toggle features. When negotiating warrant terms, it is important to ensure alignment with global capital market standards to maintain market conformity and facilitate syndication if needed. The amortization schedule for mezzanine is often back-end loaded, with minimal principal payments during the early years to preserve portfolio company cash flow. Legal documentation and the intercreditor agreement then codify the relative rights of senior and subordinated lenders, followed by closing, funding, and post-closing covenant monitoring.

    Benefits of Mezzanine in Acquisition Financing

    Mezzanine financing offers distinct advantages that make it a powerful tool in acquisition capital structures. Based on our proprietary benefit analysis, the most compelling attribute is its function as a bridge to equity without immediate dilution. Existing shareholders retain full ownership and control, while any equity participation via warrants is deferred and typically limited in scope. Unlike equity investors, mezzanine providers generally do not require board seats, preserving operational control for management.

    From a cost perspective, mezzanine debt structures carry an all-in cost of 10 to 18 percent, and critically, the cash interest component is tax-deductible. This contrasts sharply with equity financing, where investors target a 20 to 30 percent internal rate of return through capital appreciation and dividends that are not deductible to the company. The effective after-tax cost advantage makes mezzanine an efficient instrument for bridging valuation gaps in competitive auction processes.

    The following matrix helps executives compare mezzanine debt and equity on key decision criteria.

    Mezzanine Debt vs Equity: Decision Matrix for Acquisition Financing
    CriteriaMezzanine DebtEquity Financing
    DilutionMinimal (via warrants or conversion on limited basis)Full dilution of existing shareholders
    Cost of Capital10-18% all-in (tax-deductible interest)Target IRR 20-30% (higher required return)
    ControlNo board seats typically; covenants onlyInvestors often receive board representation
    FlexibilityPrepayment options vary, call protection commonExit required for liquidity; no redemption schedule
    Best ForCompanies with stable cash flow seeking bridge capitalHigh-growth companies needing strategic guidance and long-term capital

    This framework, informed by industry benchmarks and Zaidwood Capital case studies, provides a practical lens for evaluating trade-offs. The choice between subordinated debt and equity ultimately depends on your liquidity horizon, control preferences, and the underlying predictability of portfolio company earnings. To see how these structures work in practice, refer to our case studies below. This is for informational purposes only; consult your financial advisor before making financing decisions.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis. Past performance does not guarantee future results.

    Advanced Considerations: Risk Allocation, Leverage Ratios, and Investor Alignment

    Building on our earlier discussion of baseline financing options, we now turn to the sophisticated structural elements that define effective mezzanine debt structures. For sponsors and companies evaluating growth capital, understanding risk allocation, leverage benchmarks and alignment mechanisms separates a well-structured transaction from one that introduces unintended friction. We focus here on the analytical framework Zaidwood Capital applies when advising clients through these complex capital stack decisions.

    Risk Allocation and Intercreditor Dynamics

    Risk allocation in mezzanine financing centers on contractual subordination and the intercreditor agreement. This agreement governs the relationship between senior and mezzanine lenders, defining payment waterfalls, standstill periods and remedies upon default. Because mezzanine debt sits behind senior obligations, recovery in a downside scenario depends heavily on how these provisions are drafted. We structure intercreditor terms that preserve mezzanine lender rights while respecting senior creditor priority, ensuring each party understands its position before capital is deployed.

    Leverage Ratio Benchmarks Across the Capital Structure

    Leverage ratios, typically expressed as Debt/EBITDA, provide a common yardstick for assessing financial risk. The table below summarizes the benchmarks we observe across Zaidwood Capital transactions and broader industry data:

    Leverage Ratio Benchmarks by Debt Type
    Debt TypeLeverage Ratio (Debt/EBITDA)Typical Uses
    Senior Debt2.5x – 4.0xRevolving credit, term loans
    Mezzanine Debt0.5x – 2.0x (on top of senior)Acquisition bridge, growth capital
    Unitranche Debt3.5x – 5.5x (combined)Mid-market leveraged buyouts
    Subordinated Debt1.0x – 2.5xRecapitalizations, rescue financing

    These ranges illustrate how each debt layer contributes to total leverage. Senior debt anchors the structure, while mezzanine facilities layer on additional capacity, typically 0.5x to 2.0x above the senior component. For unitranche debt, the combined ratio reaches materially higher levels, creating a different risk-return profile for investors.

    Higher leverage amplifies equity returns but also increases vulnerability to earnings volatility. Recent SEC regulatory updates reinforce the need for transparent leverage disclosure and risk retention compliance, particularly for structures that push total leverage beyond historical norms. We monitor these regulatory developments closely, as they directly influence structuring options and documentation standards for mezzanine and subordinated debt financing.

    Investor Alignment Mechanisms

    Aligning interests between debt holders and equity sponsors requires deliberate structural features. Beyond the base coupon, we often incorporate PIK interest components that preserve cash flow for operational needs while compounding value for lenders. Warrants or equity co-investment rights give mezzanine investors participation in upside, matching their risk exposure with potential reward. Board observer rights provide visibility into strategic decisions without impairing management autonomy, and change-of-control provisions ensure lenders are protected — or compensated — if ownership transitions occur.

    These mechanisms transform a simple debt instrument into a partnership-oriented capital solution. Sponsors benefit from flexible financing terms while investors gain safeguards and upside exposure that senior creditors typically do not receive.

    In the next section we explore how these structural considerations feed into the due diligence process and real-world case examples.

    This content is for informational purposes only and does not constitute investment advice. Readers should consult their own legal, tax and financial advisors before making any decisions.

    Frequently Asked Questions About Mezzanine Debt Structures

    What Are Mezzanine Debt Structures?

    Mezzanine debt structures sit between senior secured debt and equity in a company’s capital hierarchy. This financing is typically unsecured and subordinated to first-lien lenders, meaning it carries higher risk but also commands higher returns. A key feature of mezzanine financing is its equity participation component — often through warrants or conversion rights — which gives lenders upside potential beyond fixed interest payments.

    How Does Mezzanine Financing Compare to Unitranche Debt?

    While both are flexible capital solutions, unitranche debt blends senior and subordinated tranches into a single facility with one blended interest rate. In a mezzanine debt structure, the layers remain distinct: a senior lender holds first priority, and the mezzanine provider sits behind them. Unitranche simplifies administration but may limit the equity upside that defines mezzanine financing.

    What Are the Typical Uses for Mezzanine Debt?

    Companies commonly use subordinated debt to fund acquisitions, support growth capital initiatives, and execute recapitalizations. Because mezzanine financing does not require hard asset collateral, it is especially useful for businesses whose value lies in cash flows or intellectual property rather than physical assets. This flexibility makes it a go-to tool for middle-market transactions and sponsor-backed deals.

    How Does Mezzanine Debt Relate to Subordinated Debt Financing?

    Mezzanine debt is a form of subordinated debt financing, distinguished by its equity-linked features. All mezzanine instruments rank below senior obligations, but not all subordinated debt includes warrants or conversion rights. The additional return potential compensates mezzanine providers for their deeper position in the repayment waterfall.

    What Are the Main Risks of Mezzanine Financing?

    Because mezzanine debt is unsecured and junior to senior loans, recovery in a default scenario can be significantly lower. The higher interest cost also increases the financial burden on the borrower. However, for companies with stable cash flows and strong growth trajectories, the risk-return trade-off of a mezzanine debt structure can be strategically sound. Please note that all investments involve risk, and past performance does not guarantee future results; you should consult your legal, tax, and financial advisors before making decisions.

    Optimizing Your Capital Structure with Mezzanine Debt

    In our advisory work, we often position clients to benefit from hybrid instruments in mezzanine debt structures, which sit between senior obligations and common equity. This subordinated layer can strengthen the balance sheet while preserving ownership control.

    What Is Mezzanine Debt?

    We define this as subordinated debt financing that includes equity participation features, such as warrants, allowing lenders to share in upside without diluting founders prematurely.

    How It Optimizes Capital Structure

    By layering mezzanine capital above equity, companies reduce dilution and gain flexible repayment options like payment-in-kind interest. This bridge is particularly useful for acquisitions, management buyouts, and growth-stage expansion.

    Mezzanine vs. Unitranche vs. Senior Debt

    Feature Mezzanine Debt Unitranche Debt Senior Debt
    Position in capital structure Junior to senior, senior to equity Single blended tranche Most senior
    Interest rate type Higher fixed or floating with PIK Blended rate; typically floating Lowest, often floating
    Covenant strictness Fewer financial covenants Moderate Strictest
    Equity component Warrants or equity kickers common Usually none None
    Typical use case Acquisitions, buyouts, recapitalizations Mid-market LBOs, quick close Working capital, asset-heavy deals

    Unitranche debt blends senior and subordinated layers into one facility, while subordinated debt financing remains a more traditional second-lien or junior note. We help management teams evaluate each path against their capital needs and timeline.

    Trade-offs and Customization

    Mezzanine capital carries higher interest and potential equity give-ups, but it provides speed and fewer restrictive covenants than senior loans. Through our debt advisory services at Zaidwood Capital, we structure each facility to match a company’s cash flow profile without promising any specific outcome.

    This section is for informational purposes only and does not constitute investment advice. Consult your legal, tax, and financial advisors before making decisions. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Resources