Table of Contents
- Series A Funding: Foundational Concepts and Process
- Core Series A Funding Mechanics: Valuation, Equity, and Investor Roles
- Series A Valuation Methodologies and Term Sheet Negotiation
- Preparing for Series A: Pitch Decks, Data Rooms, and Partner Selection
- Structuring Series A Deals and Navigating Regulatory Frameworks
- Your Series A Funding Questions Answered
- Closing Your Series A Round and Planning for Growth
Series A Funding: Foundational Concepts and Process
Having outlined the broader capital-raising journey, we now turn to Series A funding—the first institutional round that transforms validated product-market fit into scalable growth. Companies typically raise $2 million to $15 million to expand their team, penetrate markets, and build operational infrastructure. This capital injection signals the shift from early traction to rapid execution, demanding a disciplined approach to capital formation and investor relations.
The Series A process follows a structured path. Founders prepare a business plan, pitch deck, and financial projections, then pitch to venture capitalists and angel investors. Due diligence examines financial, legal, and technical aspects; our firm manages data rooms and coordinates documentation. Term sheet negotiation precedes the final closing. Throughout the Series A funding process, Zaidwood Capital’s advisory model provides senior-level attention, leveraging proprietary tools like the Velocity Matrix and Sovereign Data Nexus to accelerate deal execution and research-backed investor targeting.
Core to a round is the Series A valuation: pre-money valuation reflects the company’s worth before investment, while adding the invested capital yields the post-money valuation (e.g., $8M pre-money + $2M investment = $10M post-money). The Series A term sheet details liquidation preferences, board composition, anti-dilution provisions, and voting rights—all critical for balancing founder control with investor safeguards.
Our firm assists with pitch refinement, data room management, and introductions to over 4,000 institutional investors. For founders, pursuing the CFA program professional development—as the CFA Institute highlights—builds essential financial analysis skills. With the foundational process established, the next sections explore Series A valuation and term sheet specifics in greater depth.
Core Series A Funding Mechanics: Valuation, Equity, and Investor Roles
Once the foundational preparation is complete, founders must grasp the core mechanics that govern a series a round. In series a funding, the valuation framework sets the stage for all subsequent negotiations. Pre-money valuation is the company’s worth before new investment, while post-money valuation adds the new capital. For example, a $10 million pre-money valuation plus a $5 million investment yields a $15 million post-money valuation. Founders often ask how series a valuation is determined; it is not a formula but a reflection of market comparables, traction metrics, and investor demand. Our capital formation expertise, informed by trends in energy M&A advisory, shows that a defensible valuation rests on rigorous financial modeling and a clear growth narrative.
The same investment also illustrates equity dilution. Assuming the founders held all shares before the series a round, the $5 million investment buys the new investors a 33.3% stake ($5 million / $15 million post-money), reducing founder ownership to 66.7%. In practice, a Series A almost always creates a new employee option pool of 10–20% of the post-money capitalization, which is carved out of the pre-money valuation. This further erodes the founder stake: after setting aside a 15% pool, the founders’ post-money ownership could fall below 50%. This is why we emphasize that founders must understand the pre-money valuation’s composition, as the option pool can significantly shift ownership economics. Dilution is a necessary trade-off for growth capital, and we advise founders to model these scenarios early.
Investor roles in a series a round are clearly delineated. The lead investor typically prices the round, negotiates key terms, conducts thorough due diligence, and often secures a board seat to monitor governance. Syndicate participants—other funds or angels—write smaller checks, may receive pro-rata rights for follow-on rounds, but have limited governance influence. Compliance with guidelines from a financial regulatory authority securities (like FINRA) ensures that investor communications meet disclosure standards. As a Boutique M&A and Capital Advisory Firm, we help founders identify suitable lead investors and structure syndicates that align with long-term objectives.
A standard series a term sheet crystallizes the key economic and control provisions negotiated between founders and investors. The three provisions that most affect founder outcomes are:
- Liquidation preference: The most common is a 1x non-participating preference, which returns the investor’s original investment before any proceeds are distributed to common shareholders.
- Anti-dilution protection: Typically weighted average anti-dilution adjusts the conversion price if future rounds are issued at a lower valuation, protecting early investors from severe dilution.
- Voting rights: Series A investors often receive protective provisions that grant veto power over major corporate actions such as a sale, new equity issuance, or changes to the board.
Negotiating these terms requires careful attention to long-term founder control. With these mechanics in mind, the term sheet becomes the next critical document to master.
Series A Valuation Methodologies and Term Sheet Negotiation
Once a startup has achieved product-market fit and key milestones, the Series A funding round introduces more substantial capital and sophisticated valuation methods. For founders entering this pivotal stage, understanding how investors determine a company’s worth and structure deal terms is essential. Below, we outline the common valuation approaches and the critical terms that shape both the investment and future growth.
Series A Valuation Methodologies
Series A valuation is both an art and a science, relying on structured methodologies to arrive at a pre-money figure that aligns founder and investor interests. At Zaidwood Capital, we guide clients through three primary frameworks that dominate early-stage financing.
The Venture Capital (VC) Method works backward from a projected terminal value. Investors estimate the company’s future exit value—typically based on revenue multiples or comparable acquisitions—and then apply their required rate of return, often 40-60% annually, to discount that figure to today’s pre-money valuation. This approach accounts for expected dilution from future rounds and employee option pools.
The Scorecard Method, favored by angel investors and early-stage funds, adjusts a baseline average pre-money valuation for startups in the same region and sector. The investor evaluates the target company across dimensions such as the strength of the management team, market opportunity size, product defensibility, and competitive landscape. Each factor receives a weighting and a comparative rating, producing a customized pre-money estimate. This method is particularly useful when a startup lacks the extensive financial history required for more quantitative models.
The Comparable Transactions method analyzes recent Series A rounds in similar industries to establish valuation benchmarks. We review publicly available data and proprietary deal intelligence to identify precedent transactions, taking care to normalize for differences in growth rates, market conditions, and capital structures. This market-based approach grounds the series a valuation discussion in observable, real-world outcomes rather than purely theoretical projections.
Term Sheet Structures and Key Terms
The series a term sheet serves as the blueprint for the investment relationship. While it is non-binding in most respects, its provisions establish the economic and governance framework that will govern the company through subsequent financing rounds. We advise founders to focus on several critical terms:
- Liquidation Preference: This determines how proceeds are distributed in an exit or dissolution. A 1x non-participating preference allows investors to recover their investment before common shareholders receive anything, after which remaining proceeds are shared pro-rata. A participating preference, by contrast, lets investors double-dip—receiving their preference amount and then sharing in the remaining distribution. We typically counsel founders to negotiate for non-participating structures to preserve upside for the team and early stakeholders.
- Board Composition: Series A investors often require one or more board seats. The resulting board structure—which may include a mix of founder directors, investor directors, and independent directors—shapes strategic decision-making authority. Maintaining founder control while providing investors sufficient oversight requires careful calibration.
- Anti-Dilution Clauses: These protect investors if the company raises a future down round at a lower valuation. Weighted average anti-dilution adjusts the conversion price based on the size and pricing of the new issuance, balancing protection with founder fairness. Full ratchet anti-dilution, a more aggressive provision, resets the investor’s conversion price entirely to the lower round’s price. The weighted average approach is generally more founder-friendly and market-standard in competitive Series A negotiations.
Our advisory experience consistently shows that founders who understand these provisions before entering negotiations secure more balanced outcomes.
The Role of Investor Networks
Series A rounds rarely involve a single check-writer; they attract coordinated participation from angel syndicates and venture capital funds that bring both capital and strategic value. Angel syndicates aggregate commitments from high-net-worth individuals, often contributing domain expertise and customer introductions alongside their investment. Venture capital funds deploy institutional capital and typically lead the round, setting terms and coordinating the due diligence process.
Investors often engage specialized providers for comprehensive M&A due diligence services to evaluate a startup’s financials, operations, and legal standing before committing to a Series A round. Drawing on our internal advisory work, we recognize that regulatory changes—such as those affecting healthcare M&A—directly influence deal timelines and valuation methodologies, as rigorous compliance verification becomes a central component of investor diligence. Zaidwood Capital’s experience in managing these multi-party negotiations helps founders navigate the complex dynamics of syndicated Series A processes, ensuring that both lead and follow-on investors align on terms and expectations.
With a successful Series A close, the company enters a new phase of scaling. In the following section, we discuss post-Series A fundraising and growth strategies.
Preparing for Series A: Pitch Decks, Data Rooms, and Partner Selection
Securing series a funding requires a disciplined approach to preparation. At Zaidwood Capital, we guide founders through building a compelling pitch deck, organizing a thorough data room, selecting an advisory partner, and managing due diligence—the four stages that form the backbone of a successful capital raise.
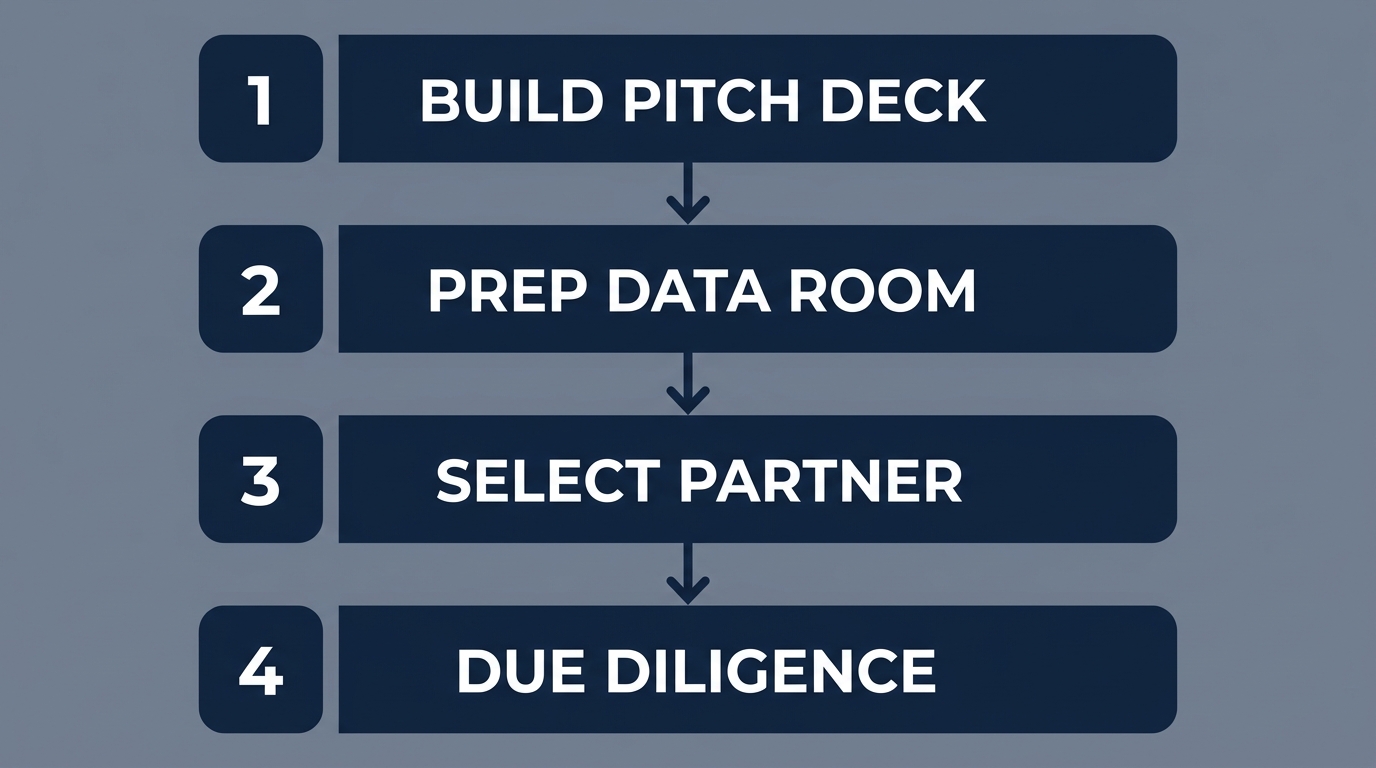
Four essential stages for Series A funding preparation
Building a Compelling Pitch Deck
While seed decks emphasize vision, a Series A deck must anchor every claim in validated traction and credible projections. Investors at this stage scrutinize unit economics, market sizing, and the specific use of proceeds. We help founders craft decks that lead with data-driven storytelling, replacing long paragraphs with clear visuals that map growth trajectories. Key slides to include:
- Problem and solution statement
- Addressable market and segmentation
- Product differentiation and defensibility
- Traction metrics (revenue, retention, growth rates)
- Unit economics and financial projections, including series a valuation assumptions
- Team qualifications and relevant experience
- Capital ask and detailed use-of-funds breakdown
We work closely with founders to refine each slide, ensuring the narrative aligns with investor expectations and the ask is clearly tied to growth milestones. Visuals like cohort analysis charts convey traction better than text, building credibility and keeping investor attention on growth potential. A concise, visually compelling deck sets the stage for the due diligence to follow.
Preparing Your Data Room
Due diligence moves quickly, and investors expect instant access to critical documentation. A well-structured data room not only expedites the series a funding timeline but also demonstrates operational maturity. We recommend organizing the following in a secure virtual repository, such as our Deal Vault:
- Capitalization table and equity history
- Audited or reviewed financial statements (P&L, balance sheet, cash flow)
- Legal documents: articles of incorporation, IP registrations, significant contracts
- Customer contracts and revenue concentration data
- Competitive landscape and market analysis
- Management team bios and organizational chart
- Any regulatory filings or compliance documents
We secure these documents in a Deal Vault that offers access controls and real-time activity tracking. This end-to-end management accelerates investor due diligence and signals that your company is ready for a Series A infusion. We work with founders to compile and audit every file, ensuring nothing is missing when the first investor inquiry arrives.
Selecting the Right Advisory Partner
Selecting the right advisory partner can make the difference between a drawn-out fundraising process and a successful capital raise. At Zaidwood Capital, we guide founders to evaluate advisors on factors beyond general corporate finance experience. Key criteria include:
- Deep sector expertise, including an understanding of regulatory environments and industry-specific valuation metrics
- A proven track record of closing Series A transactions and managing investor relationships
- Access to a global network of venture capital and private equity investors
- Proprietary technology that streamlines due diligence and investor matching, such as our Sovereign Data Nexus and Precision Catalyst
- A full-cycle approach that covers strategic documentation, data room management, and post-raise integration
An advisory firm with cross-sector experience, including healthcare mergers and acquisitions, can provide unique insights and a broader investor network for your Series A round. As a boutique M&A and capital advisory firm, we bring senior-level attention and a full-cycle methodology that aligns your growth story with the right institutional capital.
Navigating the Due Diligence Process
Once investor interest is secured, the due diligence phase begins. We guide founders through each step to ensure a smooth evaluation:
- Initial document review and investor queries
- Management presentations and site visits (virtual or in-person)
- Legal and financial verification (cap table, IP, contracts)
- Term sheet negotiation and finalization
The series a term sheet outlines valuation, governance, and liquidation preferences. With your pitch deck, data room, and advisory partner ready, you are well-positioned to evaluate term sheets and move toward closing.
Structuring Series A Deals and Navigating Regulatory Frameworks
In a Series A funding round, marrying sound deal structuring with rigorous regulatory compliance is essential for a successful capital raise. Founders must navigate term-sheet provisions that govern investor returns while satisfying SEC exemptions and self-regulatory standards. Aligning these dimensions early reduces friction and protects all stakeholders.
During a Series A valuation analysis, three methodologies guide negotiations: the Venture Capital Method, public-company comparables, and discounted cash flow models. Pre-money valuation remains a negotiated outcome, not a formula. The Series A term sheet then defines the investor-founder relationship, covering liquidation preferences (participating vs. non-participating), anti-dilution protection — weighted-average is generally more founder-friendly than full-ratchet — board composition, protective provisions, and drag-along rights.
When planning a Series A funding round, compliance with Regulation D is paramount. Rule 506(b) prohibits general solicitation, while Rule 506(c) permits broader outreach but requires verified accredited investor status—typically through third-party verification or self-certification. Employee equity falls under Rule 701, and state blue-sky laws necessitate notice filings in each state where investors reside. Zaidwood Capital is not a registered broker-dealer; securities are offered through Finalis Securities LLC, a registered broker-dealer. FINRA’s guidelines on private-placement suitability and communications emphasize thorough investor qualification and risk disclosure.
For founders seeking a partner that combines deal-structuring expertise with regulatory insight, we provide tailored advisory support. We bring deep capital-markets experience and proprietary analytics to support every phase of the round. Energy-sector companies can leverage our energy mergers and acquisitions advisory to streamline the Series A process. With a well-structured Series A in place, the next stage focuses on growth execution and eventual exit strategies.
This information is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to buy or sell any security. Investments involve risk and are not guaranteed to appreciate. Consult with legal, tax, and financial advisors before making investment decisions.
Your Series A Funding Questions Answered
Your series a funding questions answered here—especially for healthcare founders navigating regulatory shifts. Drawing on our experience as a Boutique M&A and Capital Advisory Firm, we address three critical areas where deal-making expertise clarifies early-stage capital raising.
How do regulatory changes affect Series A funding for healthcare startups?
FDA approvals and CMS reimbursement reforms have a profound influence on deal timelines and investor appetite. When reimbursement models pivot toward value-based care, we help clients recalibrate pitch decks and pro forma financials so the opportunity remains clear and compelling.
What is a typical Series A valuation for a healthcare company?
No single range fits every case. Regulatory risk, addressable market size, and intellectual property strength all sway series a valuation discussions. Our team works with founders to frame these variables before opening a series a funding round, aligning documentation with what institutional investors actually scrutinize.
What are the key term sheet provisions founders should watch?
Liquidation preferences, anti-dilution clauses, and board composition are vital in a series a term sheet. We leverage our proprietary Sovereign Data Nexus and Velocity Matrix to stress-test these provisions within a full-cycle M&A context, giving founders a sharper negotiating edge.
With our deep experience in healthcare M&A, we help you turn these answers into action.
Closing Your Series A Round and Planning for Growth
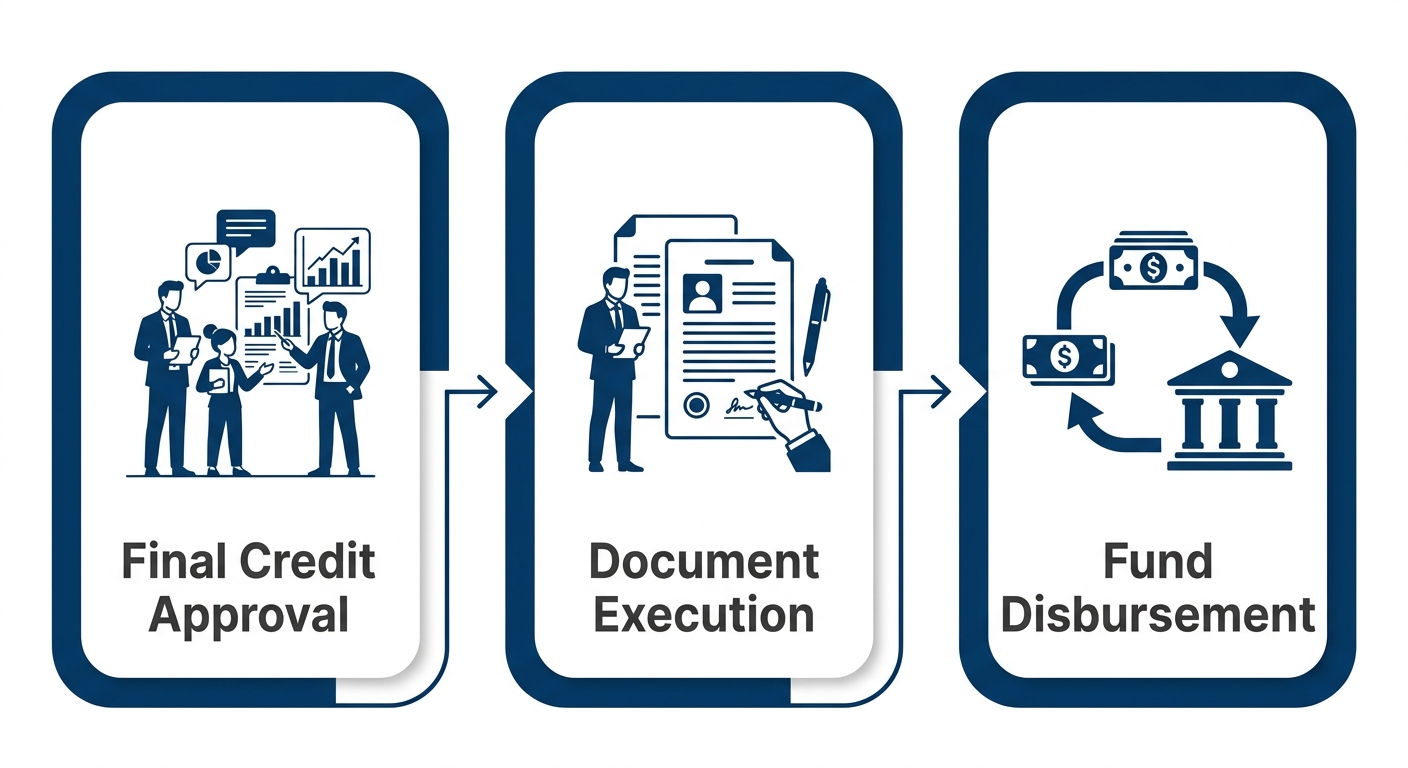
Finalizing series a funding is more than just an electronic transfer—it demands precise coordination of legal documentation, escrow, and wire transfers. We guide founders through this critical stage, ensuring the stock purchase agreement, investor rights agreement, and amended corporate charter are executed seamlessly. Our team serves as the central hub, aligning your legal counsel, the escrow agent, and incoming investor funds so that every condition precedent is satisfied before capital is released.
Once the round is closed, disciplined capital allocation transforms a new series a valuation into sustainable expansion. A typical blueprint dedicates roughly 40% to talent acquisition, 30% to marketing and sales acceleration, 20% to product development, and 10% to strategic reserves. With a finalized series a term sheet behind you, growth planning becomes measurable. We implement our Velocity Matrix and Precision Catalyst frameworks to shorten execution timelines and elevate investor communications from day one.
- Execute and file the stock purchase agreement, investor rights agreement, and amended charter
- Sync legal counsel, escrow instructions, and wire confirmations through a single point of contact
- Deploy a board-reviewed capital allocation model prioritizing hiring, go-to-market, product, and reserves
- Anchor a 6-month cash runway, a live KPI dashboard, and a quarterly board reporting cadence