Zaidwood Capital

Tag: strategic financial consulting

  • Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Table of Contents

    Choosing Between Boutique and Bulge Bracket Investment Banking

    When weighing boutique vs bulge bracket investment banking, the core distinction lies in service scope and client intimacy. Specialist advisory firms offer focused, senior-led strategies that often result in faster execution and stronger alignment with client goals. Large global banks provide extensive capital markets access and resources suited for complex cross-border mandates. For companies considering private equity exit opportunities, boutique advisors frequently deliver customized positioning within their specific industry ecosystems. Similarly, talent dynamics around investment banking compensation packages reflect the differing demands of these models. We track SEC regulatory updates closely, as heavier compliance overhead affects larger institutions disproportionately while we leverage our full-cycle M&A and capital advisory approach to integrate deep advisory with proprietary data, streamlining transactions without the structural friction of multi-layered global firms.

    Ultimately, choosing between these paths depends on your transaction scope and strategic priorities. Our model bridges the gap by combining the personalized guidance of a boutique with the data-driven precision and investor network scale that growing companies require, a balance explored further in the next section.

    1. Senior Banker Attention and Personal Service

    In the boutique vs bulge bracket investment banking debate, one key differentiator is the level of senior attention you receive. At large, full-service firms, deal execution is often delegated to junior teams while managing directors appear only at critical milestones. We find this approach can dilute accountability and slow decision-making.

    Our model is fundamentally different. When you engage a boutique investment banking firm like Zaidwood Capital LLC, your mandate is led directly by our principals from pitch to close. As outlined in our description of M&A advisory services, senior bankers provide strategic guidance, valuation, negotiation support, and hands-on deal management throughout the entire lifecycle. This structure ensures decades of combined experience are applied to your specific strategic goals, delivering more tailored advice and faster execution.

    This personalized service is particularly valued by private equity firms seeking seamless exit execution and by companies requiring discreet, high-touch advisory. By leveraging our proprietary network and data resources, our senior team simplifies complex transactions, embodying our commitment to Streamlining Transactions with precision and focus.

    2. Tailored Fee Structures for Mid-Market Deals

    When considering boutique vs bulge bracket investment banking, the fee negotiation dynamics shift substantially for middle-market transactions. Unlike the rigid, standard pricing grids common at large institutions, we design our compensation around each mandate’s unique contours. This flexibility ensures your advisory costs reflect actual deal complexity rather than a one-size-fits-all schedule, aligning our incentives directly with your outcome.

    A typical framework might blend an initial retainer with a success-based component, or we may structure a milestone-driven fixed fee for a carve-out divestiture. The mix is always negotiated, absorbing variables like target size, cross-border diligence, and sector-specific resource requirements. For private equity firms managing portfolio company exits, this custom approach preserves more equity value while delivering institutional-quality execution. Our compensation benchmarks, detailed on our FAQ page, illustrate how tailored structures sit competitively within industry norms. As we always clarify, fees are custom-quoted and subject to mutual agreement rather than a published rate card.

    This disciplined yet adaptable approach removes friction from the engagement, letting you forecast costs with clarity. Next, we will walk through how our execution process turns that aligned structure into deal momentum.

    3. Specialized Industry Expertise

    Specialized industry expertise is a defining hallmark of the boutique model in investment banking. Unlike generalist institutions, boutique firms concentrate intellectual and relational capital into targeted verticals, cultivating an intimate understanding of sector dynamics, competitive landscapes, and value drivers. In private equity exit opportunities, this depth translates directly into superior deal sourcing because advisory teams speak the same operational language as founders, operators, and institutional buyers. Drawing from our own capital network exceeding $15 billion and an aggregate transaction volume surpassing $24.4 billion, we see consistent evidence that specialization sharpens valuation insight and accelerates execution.

    Sector-specific knowledge also shapes how boutique teams prepare portfolio companies for exit. Advisors often bring prior operating experience within the industries they serve, allowing them to anticipate buyer diligence questions and position assets around the metrics that matter most to private equity firms. When general partners evaluate acquisition targets, they rely on advisors who can interpret unit economics, regulatory nuances, and customer concentration risks without a learning curve, an advantage that industry depth systematically delivers.

    Industry depth shortens timelines and reduces transaction friction, qualities that matter acutely when fund lifecycles and market windows dictate exit timing. The structural alignment between boutique specialization and private equity mandates explains why sector-focused advisory teams continue gaining share in middle-market transactions. As the discussion shifts toward compensation structures, that same specialized expertise becomes a tangible factor influencing how transaction professionals are rewarded for execution.

    4. Agile Decision-Making and Speed

    Agile decision-making and speed represent some of the most compelling differentiators when evaluating boutique vs bulge bracket investment banking advisory services. At Zaidwood Capital, our lean, partner-led structure eliminates the multiple layers of approval and internal bureaucracy that typically slow down larger institutions. This streamlined architecture translates into faster, more decisive action for our clients.

    The role of an M&A advisor is inherently to accelerate deal timelines through proactive market intelligence and efficient coordination of due diligence. We execute this through our proprietary Velocity Matrix framework, which drives transaction velocity without compromising the depth or quality of our analysis. This systematic approach ensures that while we move quickly, we never sacrifice the financial, legal, and operational rigor that complex transactions demand.

    This responsiveness is particularly critical for owners pursuing private equity exit opportunities, where market windows can close rapidly and timing often correlates directly with value realization. Our direct partner involvement and efficient processes allow us to respond to these dynamics with the urgency they require. This structural speed also enables us to deliver a level of service intensity and personalization that more layered organizations find difficult to match.

    Agility here is not about cutting corners. It is the natural outcome of a flatter organizational design, empowered decision-makers, and a proprietary operating system purpose-built to optimize transaction timelines. This foundation of responsive execution supports the personalized and cost-effective approach that distinguishes true partnership in M&A advisory.

    5. Comprehensive Network Access and Deal Sourcing

    Beyond our advisory capabilities, the real differentiator in the boutique vs bulge bracket investment banking landscape is the depth of our network. We connect clients with 4,000+ global investors and $15B+ in deployable capital, creating private equity exit opportunities that rival the largest institutions while maintaining the agility of a specialized boutique.
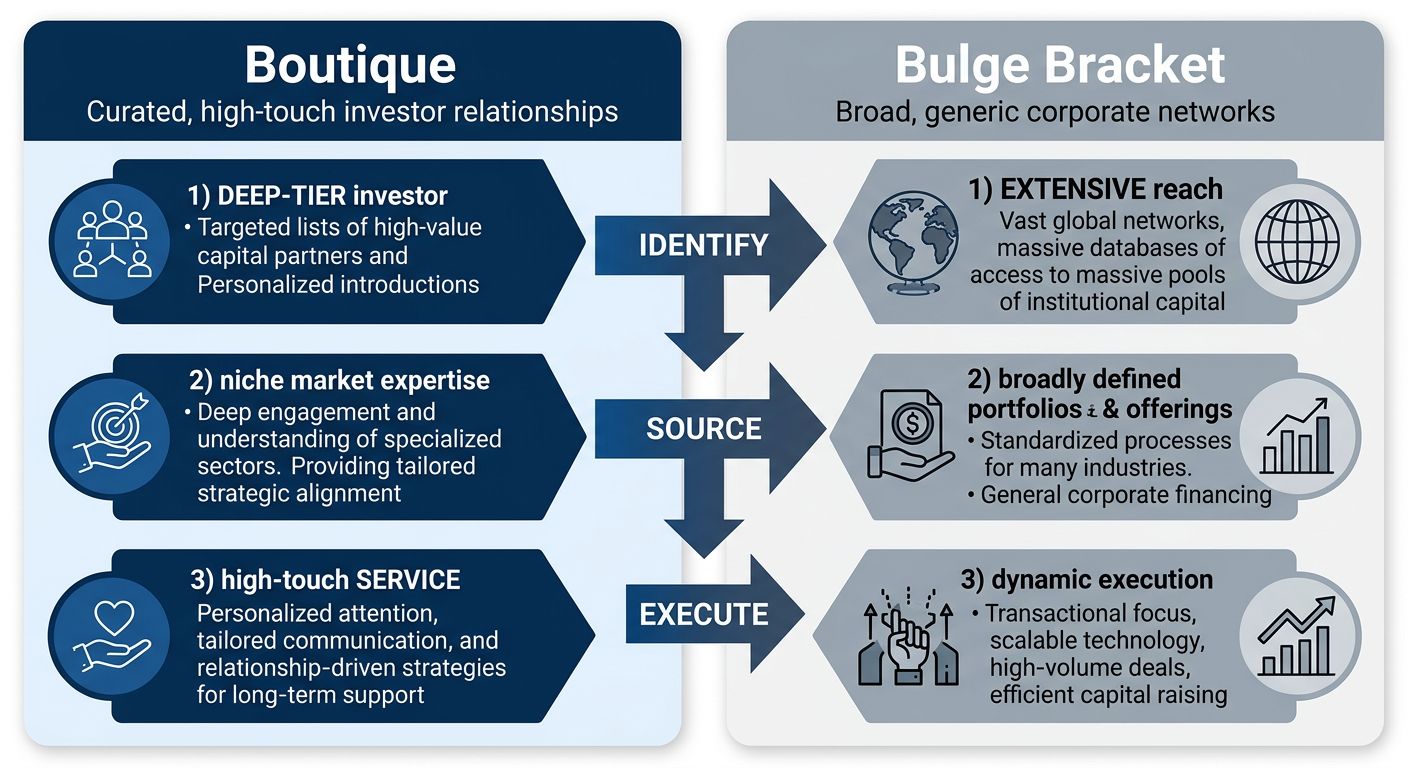
    Infographic comparing boutique M&A firm's high-touch investor network against bulge bracket's broad corporate network with deal sourcing funnel stages.
    Boutique vs. bulge bracket network access comparison at Zaidwood Capital.

    This integrated approach is powered by proprietary tools, including the Sovereign Data Nexus, Precision Catalyst, and Velocity Matrix, which sharpen deal sourcing and analysis. Our $24.4B+ aggregate transaction volume across full-cycle M&A, equity, and debt mandates confirms the scale we deliver. Exclusive access to Deal Vault and our curated Investor Rolodex further extends our partners’ reach. As our internal resources explain, these capabilities streamline the entire capital formation lifecycle, from LP placement and debt structuring to equity advisory.

    Whether you are evaluating private equity exit opportunities or structuring a capital raise, this institutional-grade infrastructure, delivered by a boutique firm, provides a clear advantage over traditional bulge bracket models. Our approach ensures you receive both the scale and the personalization that today’s complex deals demand. We’ll next explore how our fairness opinions and transaction advisory services add another layer of diligence.

    6. Cultural Alignment and Communication

    The choice in boutique vs bulge bracket investment banking extends beyond structure and into the softer, yet equally critical, dimensions of culture and communication. At Zaidwood Capital, we believe that a strong advisory relationship depends on transparency, trust and open dialogue — qualities that are built through consistent interaction rather than brand reputation alone. How a firm communicates directly shapes your experience during what is often the most consequential financial event in a company’s lifecycle.

    Communication style and responsiveness matter because M&A processes move quickly and demand real-time judgment. Boutique firms typically offer direct access to senior partners and a highly personalized cadence, while larger platforms operate through more structured teams and formalized reporting. Neither approach is inherently superior; the right fit depends on how you prefer to receive information, make decisions and manage pressure. Our internal resource on what M&A advisors do outlines how advisors facilitate fit assessments early in the process, helping clients evaluate both technical capability and interpersonal compatibility.

    Finding the right cultural fit also means considering how an advisor handles long-term strategic goals such as private equity exit opportunities or structuring investment banking compensation packages. These conversations require discretion, deep industry knowledge and a relationship grounded in mutual confidence. Full-Cycle M&A mandates succeed when the advisory team aligns with your organization’s values, communication norms and decision-making rhythm — a principle we prioritize through every phase of engagement.

    Streamlining Transactions depends as much on human chemistry as it does on financial engineering. In our experience, the most successful partnerships are those where both sides invest in candid, ongoing communication. The next section outlines practical steps you can take to evaluate and engage an advisor who fits your unique organizational culture.

    Making the Right Choice for Your M&A Needs

    Given the distinct advantages of each model, selecting the right advisor depends on your transaction size, industry focus, and desired level of partner attention. M&A advisors typically provide comprehensive support across buy-side and sell-side representation, valuation, due diligence, and deal negotiation. At Zaidwood Capital, we deliver Full-Cycle M&A and capital advisory that combines the personalized service of a boutique firm with access to over 4,000 institutional investors and $15B+ in deployable capital. Our approach ensures seamless execution from initial due diligence through final closing, backed by $24.4B+ in aggregate transaction volume. We encourage you to assess your specific requirements and book a call for tailored guidance on your M&A journey.

    Resources

  • Supply Chain Financing Explained: Essential Guide for 2026

    Supply Chain Financing Explained: Essential Guide for 2026

    Table of Contents

    The Foundations of Supply Chain Financing

    Supply chain financing encompasses a set of technology-driven solutions that allow buyers and suppliers to improve working capital without relying on traditional trade finance instruments such as letters of credit. According to Zaidwood Capital’s resource library, SCF is a vital component of global lending alternatives, helping businesses stabilize cash flows while deepening trading relationships.

    Reverse factoring is one of the most widely adopted structures. In this model, a corporate buyer confirms an invoice and a financial institution pays the supplier early at a modest discount, while the buyer repays the financier on a later date. The supplier receives faster cash, the buyer preserves liquidity, and the funder earns a predictable margin—a mutually beneficial arrangement.

    Dynamic discounting offers an alternative mechanism: the buyer uses its own cash to pay invoices ahead of term in exchange for a sliding-scale discount. This gives suppliers near-immediate access to funds at a cost that adjusts with the speed of payment. Inventory finance rounds out the toolkit by providing dedicated funding against stock held in the supply chain, reducing carrying costs and freeing capital for growth.

    Many businesses also layer in equipment financing to complement these solutions, funding the tangible assets that keep supply chains moving. Together these instruments provide greater cash-flow predictability, reduce supplier concentration risk, and strengthen the resilience of the entire supply network.

    Understanding Supply Chain Financing Benefits and Distinctions

    Supply chain financing has emerged as a key buyer-led solution that enables companies to optimize working capital while strengthening supplier relationships. Unlike traditional factoring, which is initiated when a supplier sells its receivables, SCF is initiated by the buyer, leveraging its own credit rating to secure attractive financing terms for its suppliers. This fundamental shift creates a more collaborative and cost-effective financing environment. In this section, we explore the core benefits and six critical distinctions that set supply chain financing apart from traditional factoring.

    The table below compares these financing methods across six critical aspects:

    Supply Chain Financing vs Traditional Factoring
    AspectSupply Chain FinancingTraditional Factoring
    InitiationInitiated by the buyer, leveraging its credit ratingInitiated by the supplier selling its receivables
    Credit AssessmentBased on buyer’s creditworthiness, not supplier’sBased on supplier’s customer credit and invoice quality
    Cost of CapitalLower cost, typically buyer’s cost of funds plus a small marginHigher fees, discount plus service charges
    Working Capital ImpactExtends buyer’s payables without straining supplier, optimizes cash conversion cycleAccelerates supplier cash flow but may not benefit buyer’s DPO directly
    Supplier RelationshipStrengthens buyer-supplier relationship through collaborative liquidityCan be perceived as supplier distress; may damage relationship
    Risk ExposureCounterparty risk primarily on the buyer; operational and legal risksRisk of non-payment by debtor; recourse arrangements common

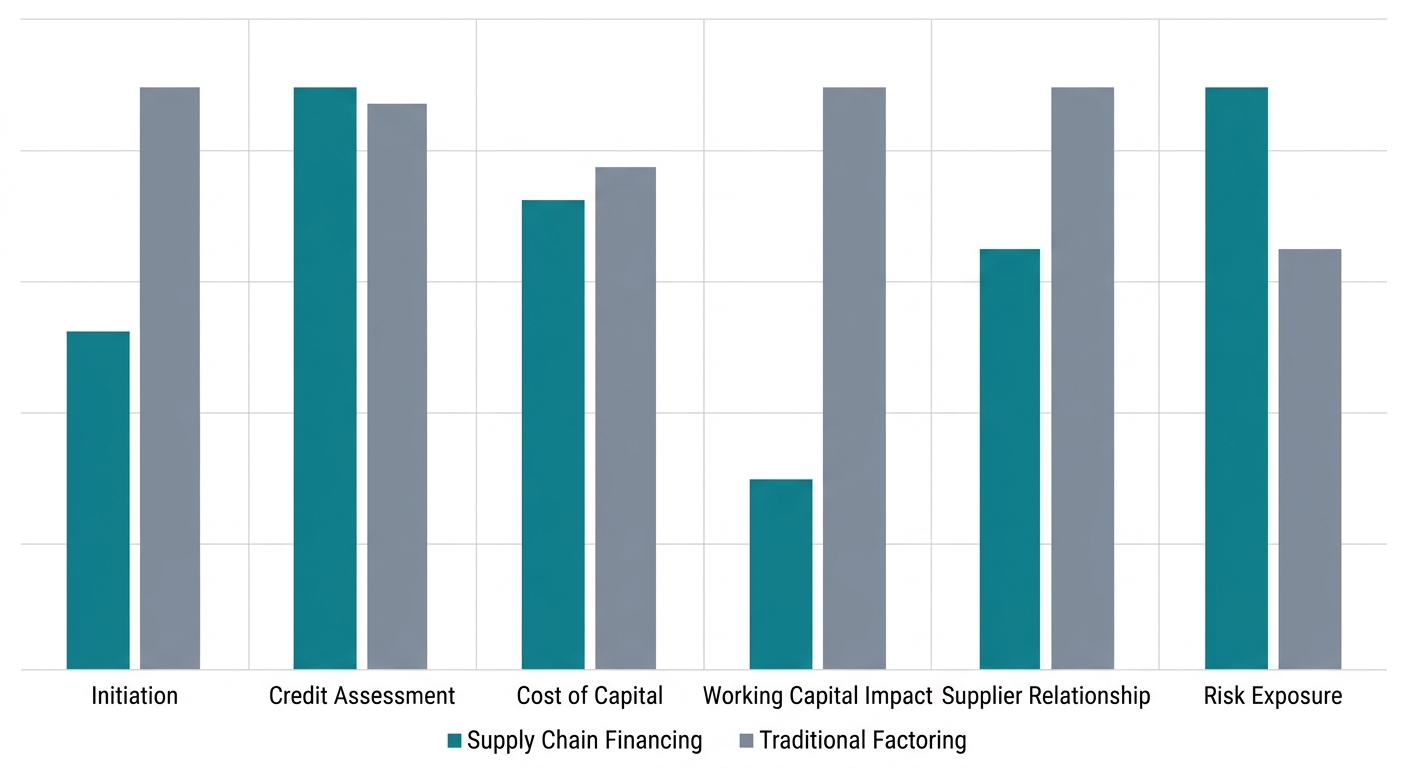
    From a strategic standpoint, supply chain financing delivers a decisive edge by lowering the cost of capital—leveraging the buyer’s credit rather than relying on supplier-level assessments—while simultaneously extending payment terms without squeezing supplier liquidity. This structure optimizes the cash conversion cycle for both parties: buyers preserve working capital, and suppliers gain access to affordable, timely funding. Moreover, because SCF is framed as a collaborative liquidity solution rather than a sign of financial distress, it reinforces trust and long-term supplier relationships, which are critical in today’s interconnected supply chains. The risk profile also shifts favorably; counterparty risk concentrates on the financially stronger buyer rather than on diverse, often smaller, suppliers. As recognized by the International Capital Market Association, these distinctions underscore the role of structured supply chain finance in modern capital markets. From our advisory work, we observe that such buyer-led financing not only enhances operational resilience but also aligns with the interests of all supply chain participants. The chart below visualizes how SCF outperforms traditional factoring across these performance dimensions, reinforcing why it has become a preferred strategy for resilient supply chains.

    Bar chart comparing supply chain financing and traditional factoring across six key performance aspects using teal and gray bars

    Supply chain financing versus traditional factoring comparison across six key business aspects

    Key Mechanisms and Structures in Supply Chain Finance

    Modern supply chain financing (SCF) helps businesses optimize working capital through a variety of structured instruments, each designed to align the liquidity needs of buyers and suppliers. The three primary mechanisms—reverse factoring, dynamic discounting, and approved payables finance—differ in how they fund early payments, yet all share the goal of accelerating supplier cash flow while preserving buyer payment terms. Understanding their inner workings and when to apply each is essential for corporate treasurers seeking to build resilient, financially stable supply networks.

    How Reverse Factoring Unlocks Liquidity

    Reverse factoring, often called approved payables finance, follows a disciplined sequence that centers on the buyer’s credit strength. First, the buyer initiates a supply chain finance program with a financial institution (the funder). The buyer then approves supplier invoices and transmits them to the funder via a digital platform. Upon receiving approved invoices, the funder pays the supplier early—generally after applying a small discount—while the original invoice due date remains unchanged. The buyer ultimately repays the funder at the agreed-upon extended term, thereby preserving its own cash on hand. This structure enables suppliers to access lower-cost capital than traditional factoring because the funding cost is benchmarked against the buyer’s superior credit rating, not the supplier’s.

    For buyers, the arrangement stretches payment terms without squeezing the financial health of their supply chain partners, reducing the risk of supplier insolvency. For suppliers, early payment at competitive rates directly improves working capital. Importantly, supply chain finance programs—especially reverse factoring—are subject to SEC disclosure requirements that promote corporate transparency; stakeholders can monitor regulatory developments through SEC regulatory news and updates. These obligations reinforce the need for robust reporting practices in any SCF initiative.

    Dynamic Discounting vs Approved Payables Finance

    Dynamic discounting takes a different approach: it is a buyer-funded mechanism where the buyer voluntarily offers early payment to suppliers in exchange for a discount that increases the earlier payment is made. The sliding scale is typically calculated per day before the net due date, allowing the buyer to earn an implicit, risk-free return on its surplus cash. Because no external funder is involved, dynamic discounting is most attractive to corporate treasuries that hold ample liquidity and seek to optimize cash returns without introducing third-party credit risk.

    By contrast, approved payables finance (including reverse factoring and multi-bank platforms) relies on an external funder that purchases approved receivables against the buyer’s credit. This model is preferred when the buyer wants to inject liquidity into its supply chain without deploying its own cash, or when it lacks the excess balances needed for dynamic discounting. The following table summarises the key instruments available:

    Types of Supply Chain Finance Instruments
    InstrumentDescriptionTypical UsersBenefitsLimitations
    Reverse FactoringBuyer-initiated program where a funder pays supplier invoices early against the buyer’s credit ratingLarge buyers with strong credit, multiple SME suppliersLower financing cost, stable supply chainRequires buyer commitment; supplier onboarding complexity
    Dynamic DiscountingBuyer offers early payment to suppliers in exchange for a sliding-scale discount based on how early payment is madeBuyers with excess cash; suppliers needing liquidityNo third-party funder; buyer earns better return on cashOnly works if buyer has surplus cash; discount negotiation can be complex
    Approved Payables FinanceSimilar to reverse factoring but often includes multiple buyers and suppliers on a multi-bank platformMultinational corporates, banks, and large supplier networksScalable, automated, integrated with ERP systemsHigh setup costs; requires robust technology integration

    Selecting the right instrument depends on a corporation’s treasury priorities. Reverse factoring shines when the goal is to fortify the supply chain without significant cash outlay, leveraging the buyer’s credit for the benefit of the entire supplier base. Dynamic discounting offers the best fit when the buyer holds surplus cash and can capture a safe, immediate return. For large multinationals managing sprawling supplier networks, approved payables finance delivered through multi-bank platforms delivers the scalability and automation needed to process thousands of invoices efficiently while maintaining compliance with evolving disclosure standards.

    Integrating Technology Platforms into Supply Chain Finance

    Technology platforms are the connective tissue that makes modern supply chain finance practical at scale. Through ERP-integrated portals and, increasingly, blockchain-based ledgers, these systems automate invoice verification, trigger early-payment offers, and execute fund transfers with minimal manual intervention. As soon as a buyer approves an invoice, the platform can instantly notify the supplier and, if the program rules are met, initiate payment to a designated account. Real-time dashboards then allow all parties—buyers, suppliers, and funders—to track invoice status, discount terms, and cash positions, reducing both operational friction and the opportunity for fraud.

    This digitization eliminates paper-based processes and cuts approval cycles from weeks to hours, a critical factor when working capital is tight. Moreover, built-in audit trails align with regulatory expectations, helping firms meet SEC disclosure obligations without additional overhead. As supply chain financing continues to evolve, the seamless integration of these platforms will remain a cornerstone for driving efficiency, transparency, and resilience across global trade ecosystems.

    Implementing Supply Chain Finance for Working Capital Optimization

    Having established the strategic value of supply chain financing for working capital optimization, this section moves from theory to execution. For mid-market CFOs and treasurers, capturing the liquidity benefits demands a structured, three-phase approach: internal readiness assessment, partner selection, and a controlled pilot-to-rollout journey. As Zaidwood Capital’s own resource on preserving working capital demonstrates, instruments that convert large outlays into manageable installments—whether for equipment purchases or supplier invoices—free up cash for essential operations. We focus on practical metrics and milestones that accelerate the cash conversion cycle. The guidance below synthesizes our advisory experience into actionable steps.

    Assessing Your Company’s Readiness for Supply Chain Finance

    Before approaching funders, we recommend a thorough internal review. Several key indicators signal that a company will benefit from receivables financing and can attract competitive terms.

    • Cash Conversion Cycle Metrics: A high days sales outstanding (DSO) or a meaningful opportunity to extend days payable outstanding (DPO) relative to days inventory outstanding (DIO) indicates trapped working capital. If your DPO is well below industry peers, a supply chain finance program can generate immediate liquidity.
    • Credit Profile: Funders typically seek an investment-grade or near-investment-grade rating. Strong financial fundamentals—stable revenue, healthy EBITDA margins, and manageable leverage—can offset a borderline rating.
    • Supplier Segmentation: Prioritize strategic, high-volume suppliers or those reliant on early payment. A segmentation framework identifies the top 10–20 suppliers whose early-payment discount appetite will maximize working-capital lift and simplify onboarding.
    • Technology Infrastructure: Real-time approved-invoice data exchange is essential. Your ERP system (SAP, Oracle, Microsoft Dynamics) should support API integrations or secure file transfers to a funder’s platform.
    • Internal Commitment: Successful programs require dedicated cross-functional resources—treasury, procurement, legal, and IT. Our team provides a readiness checklist to ensure all stakeholders are aligned before launch.

    Selecting the Right Supply Chain Finance Partner

    Choosing the right SCF partner is critical. We evaluate funders and technology providers across multiple dimensions, weighting criteria to align with your strategic objectives.

    • Funder Credit Capacity: Assess the funder’s ability to handle your supply chain’s invoice volume and peak funding needs. Look for a track record of stability and diverse capital sources.
    • Platform Scalability: The technology platform must integrate with your ERP and support rapid supplier onboarding. Examine API capabilities, security protocols, and dashboard analytics.
    • Legal and Structuring Expertise: The partner should possess deep experience with receivables purchase agreements, true-sale opinions, and cross-border trade finance if relevant. Our team can review legal terms to mitigate counterparty risk.
    • Supplier-Onboarding Support: A partner offering dedicated enrollment resources accelerates adoption and reduces internal strain.
    • Pricing Transparency: Evaluate the discount margin relative to your weighted average cost of capital (WACC) and confirm all fees are clearly disclosed.

    We run a structured RFP with weighted scoring. Early preparation of documents—financials, tax returns, credit application—mirrors the requirements Zaidwood Capital’s equipment financing resource outlines.

    Steps to Launch and Manage a Program

    With readiness confirmed and a partner selected, execution follows a phased roadmap. We guide clients through:

    1. Pilot Design: Select 5–10 friendly suppliers and run a controlled invoice-discounting cycle. Measure the impact on DPO and supplier satisfaction, then refine workflows.
    2. Legal Documentation: Finalize master receivables purchase agreements and supplier participation agreements. The onboarding documentation process mirrors the requirements for equipment financing—Zaidwood Capital can help you prepare the necessary financial information.
    3. Supplier Onboarding: Communicate program benefits, provide training, and assist with platform enrollment to drive adoption.
    4. Full Rollout: Expand to the broader supplier base, integrating governance and KPI monitoring.

    The table below outlines the full implementation roadmap, mapping each phase to key activities, timelines, and responsible parties.

    Supply Chain Finance Implementation Roadmap
    PhaseKey ActivitiesTypical TimelineResponsible Party
    Internal Readiness AssessmentAnalyze cash conversion cycle, supplier segmentation, credit rating4–6 weeksCFO / Treasury
    Partner SelectionRFP to funders and tech platforms; legal due diligence6–12 weeksProcurement & Legal
    Pilot ProgramOnboard top 10 suppliers, test workflows, validate savings8–12 weeksCross-functional team
    Full Rollout & GovernanceExpanding to full supplier base, establishing KPIs, ongoing risk monitoring6–12 monthsTreasury & Operations

    Ongoing governance tracks KPIs like DPO improvement, supplier adoption rate, and cost-of-funds versus WACC, with periodic risk reviews. This content is educational, not investment advice. To discuss your implementation, we invite you to Book A Call.

    Mitigating Risks and Ensuring Success in Supply Chain Finance Programs

    As companies expand their supply chain financing initiatives, the complexity of managing counterparties, operations, and regulatory landscapes introduces a range of risks that can undermine program stability. We understand that a structured approach to identifying and mitigating these risks is essential for building lasting SCF resilience. The following table outlines the primary risk categories, along with their concrete manifestations and proven mitigation strategies.

    Risk Category Description Examples Mitigation Strategy
    Counterparty Risk Buyer payment default or credit downgrade Default, rating decline Credit analysis, diversification, credit insurance
    Operational Risk Process failures, IT disruptions, invoice errors Platform outage, data errors Dual-approval workflows, disaster recovery testing
    Legal & Regulatory Risk Non-compliance with securities/tax laws Misclassification, tax challenges Legal counsel, SEC monitoring, ICMA guidelines
    Technology & Cybersecurity Risk Data breaches, hacking, integration gaps Ransomware, data leak Cybersecurity audits, encryption, vendor assessments

    While these targeted measures address distinct vulnerabilities, truly robust supply chain financing programs require an integrated risk management framework. Counterparty due diligence must be paired with operational resilience so that a single buyer default does not cascade through the entire supply network. Similarly, legal compliance—guided by standards from the International Capital Market Association (ICMA)—should be embedded alongside aggressive cybersecurity protocols. Implementing regular audits and engaging specialized cyber security consulting services can help fortify the SCF platform against evolving digital threats.

    Continuous monitoring and adaptive governance are what keep risk controls effective over time. We recommend stress testing exposure under adverse scenarios, conducting periodic independent audits of processes and technology, and updating governance structures to reflect new threats. By embedding proactive oversight into the program’s DNA, companies can move from reactive firefighting to sustained resilience. This forward-looking posture not only safeguards capital flows but also strengthens the confidence of suppliers and investors alike, setting the stage for scalable growth.

    Common Questions About Supply Chain Financing

    With foundational concepts in place, we turn to the questions businesses most often ask about supply chain financing.

    What exactly is supply chain financing?

    Supply chain financing—also called reverse factoring—is a buyer-led program. The buyer’s stronger credit standing lets suppliers collect early payment at a lower cost than traditional borrowing.

    How does the process work step by step?

    First the buyer approves invoices. Then a financial institution pays the supplier early, deducting a small fee. Finally the buyer remits the full invoice amount to the institution on the original due date.

    How does supply chain funding differ from factoring?

    Factoring is initiated by the supplier and can be more expensive. Reverse factoring, in contrast, relies on the buyer’s credit quality and happens only with the buyer’s direct participation.

    Who qualifies for these supply chain funding programs?

    Suppliers need approved invoices from a participating buyer. They also must complete the financing platform’s know-your-customer verification before accessing the early-payment facility.

    Having addressed the most frequent questions, the next stage is understanding how to put this knowledge into action.

    Strategic Considerations for Corporate Finance Leaders

    Corporate finance leaders should view M&A as a strategic growth lever, not just a transaction. Supply chain financing unlocks working capital and strengthens liquidity without adding traditional debt. The right mix of mezzanine, venture debt, and equity aligns capital structure with company stage and goals. Comprehensive due diligence—financial, legal, operational, human capital—flags risks and value drivers before any deal. Tailored advisory matches financial strategy to corporate objectives, and our network of 4,000+ investors and $15B+ capital accelerates deal flow and improves terms. Once strategic direction is clear, execution becomes the priority.

    This article was researched and written with the assistance of AI tools.

    Resources