Zaidwood Capital

Category: Private Equity

  • M&A Due Diligence Services: Complete Guide for 2026

    M&A Due Diligence Services: Complete Guide for 2026

    Table of Contents

    Essential Guide to M&A Due Diligence Services

    Building on the role of investment banks in M&A, a critical component of any transaction is the comprehensive evaluation delivered by M&A due diligence services. Due diligence is the detailed examination of a target company’s financials, operations, legal standing, and strategic fit to identify potential risks and validate the transaction thesis.

    The process encompasses four main pillars: financial due diligence, which scrutinizes historical and projected financial performance; legal due diligence, which reviews contracts, intellectual property, and regulatory compliance; operational due diligence, which assesses internal processes and scalability; and strategic/commercial due diligence, which evaluates market positioning and synergy potential. While thorough, due diligence is a risk mitigation tool, not a guarantee of success.

    Zaidwood Capital, a Boutique M&A and Capital Advisory Firm, streamlines transactions—particularly the due diligence phase—by offering the Sovereign Data Nexus secure data room that enables controlled document exchange. As investment banks, we coordinate due diligence across financial, legal, and operational workstreams, acting as gatekeepers and advisors. Understanding what is an investment bank helps clarify how we structure and oversee each step of this rigorous process.

    By converting raw data into actionable insights, thorough due diligence empowers decision-makers to negotiate from a position of clarity. The following sections break down each type of due diligence and how boutique firms streamline them.

    Core Components of M&A Due Diligence

    The cornerstone of a successful transaction is a thorough due diligence process. When clients engage us for M&A due diligence services, we structure the review around five interconnected areas: Financial, Legal, Operational, Commercial, and Strategic. Each area addresses distinct risks and opportunities that collectively shape the investment thesis.

    Comparison Table: Key Diligence Areas at a Glance
    Diligence AreaFocusKey Questions Answered
    FinancialHistorical and projected financial statements, working capital, debt structureAre revenue and margin trends sustainable? Are there hidden liabilities?
    LegalContracts, litigation history, IP ownership, regulatory complianceAre there pending lawsuits or IP encumbrances? Do contracts contain change-of-control clauses?
    OperationalSupply chain, IT systems, workforce, facilitiesHow resilient is the supply chain? Are key person dependencies manageable?
    CommercialCustomer concentration, market competitiveness, sales pipelineAre top customers locked in or at risk? Is the revenue base diversified?
    StrategicFit with acquirer’s long-term plan, cultural alignment, synergy potentialWill the target accelerate or dilute the acquirer’s strategic objectives?

    Financial diligence scrutinizes historical and projected income statements, balance sheets, and cash flows to validate performance trends. We assess working capital adequacy, debt structure, and off-balance-sheet exposures that could mask hidden liabilities. The goal is to confirm that reported earnings translate into sustainable cash generation and to quantify any adjustments needed to normalize the target’s financial position.

    Legal diligence examines the target’s contract portfolio, litigation history, intellectual property ownership, and regulatory compliance. We pay special attention to change-of-control provisions that could trigger termination or consent rights. All legal and financial reviews are conducted in alignment with CFA Institute professional standards for objectivity and thoroughness, ensuring no material legal risk is overlooked.

    Operational diligence probes the resilience of the supply chain, the robustness of IT systems, and the composition of the workforce. We evaluate key person dependencies and facility redundancies that could disrupt post-close operations. Understanding these operational levers allows us to quantify integration risks and identify quick wins that enhance value from day one.

    Commercial diligence assesses customer concentration, the health of the sales pipeline, market competitiveness, and revenue diversification. By analyzing contract renewals and switching costs, we determine whether top customers are locked in or at risk of churn. A diversified revenue base reduces post-transaction volatility and strengthens the platform’s long-term growth trajectory.

    Strategic diligence evaluates how well the target aligns with the acquirer’s long-term plan, cultural values, and synergy potential. We map revenue and cost synergies to concrete integration milestones, ensuring that the deal advances the acquirer’s strategic objectives rather than diluting them. A systematic review across all five areas uncovers both hidden risks and value-creation opportunities.

    Each component warrants a deeper dive; in the following pages we examine the specific methodologies and best practices for each diligence area. Our approach, refined through extensive technology M&A experience as captured in our guide to tech transaction steps, ensures that no dimension of risk escapes scrutiny.

    In-Depth Process Walkthrough of M&A Due Diligence

    Now we examine the three phases that make up a comprehensive due diligence process. A walkthrough of our M&A due diligence services reveals how scoping, review, and integration work together to mitigate risk.

    Phase 1: Scoping and Data Room Preparation

    Comparison Table: Financial vs. Operational Due Diligence
    DimensionFinancial DiligenceOperational Diligence
    Primary goalValidate historical accuracy and future earnings capacityAssess the sustainability of operations and efficiency of processes
    Key documentsAudited P&L, balance sheet, cash flow, tax returnsSOPs, org chart, IT architecture, supplier contracts
    Typical teamCPAs, valuation analysts, FP&A specialistsOperations consultants, supply chain experts, HR specialists
    OutputQuality of earnings report, debt capacity analysisOperational risk matrix, integration readiness score

    Phase 1 begins with scoping sessions where our deal team and the buyer’s leadership jointly identify the value drivers and critical risk areas—such as customer concentration, key-person dependency, or regulatory exposure—that will shape the diligence agenda. From those discussions, we build a detailed data request list that typically includes multiple years of audited financial statements (P&L, balance sheet, cash flow), material customer and vendor contracts, IP registrations, employment agreements, and corporate governance documents. A secure virtual data room—our deal vault—is then deployed on our Sovereign Data Nexus platform. The environment is structured with a folder hierarchy that mirrors the diligence workstreams: financial, legal, commercial, and operations. We configure tiered access controls so that legal reviewers, for example, can only access contract folders, while financial analysts see only the finance section. We also align the workstream teams on review timelines, assign responsibilities, and confirm that all requested materials have been uploaded. This disciplined preparation is the foundation that makes the subsequent document review efficient and secure.

    Phase 2: Document Review and Issue Identification

    In Phase 2, our specialists simultaneously review financial statements, legal contracts, operational KPIs, and commercial agreements to surface risks and validate the target’s representations. Financial analysts verify historical earnings, working capital trends, and revenue quality by examining audited P&L, balance sheets, and tax returns, flagging any non-recurring items or accounting policy inconsistencies. Legal counsel scrutinizes customer and vendor contracts for change-of-control triggers, assignment restrictions, and indemnity provisions, and they review employment agreements for retention risks and non-compete enforceability. On the operational side, we assess KPIs such as revenue per employee, system uptime, and supply-chain resilience, comparing them against industry benchmarks to spot inefficiencies. Throughout the phase, we use the data room’s built-in Q&A module to submit targeted questions to the seller’s management; each response is logged and cross-referenced. This iterative process often brings hidden liabilities to the surface. The data room’s Q&A module tracks each query and response, and we cross-reference answers against the original documents to verify consistency. The issue log is shared with the buyer’s deal team in real time, enabling collaborative prioritization. As we illustrate in our complete guide on tech mergers and acquisitions, deep document review frequently uncovers unreported contingent liabilities or non-compliant IP assignments that can affect valuation. In regulated sectors, we also overlay compliance checks against FTC, CMS, and FCC standards, informed by our internal research on how regulatory shifts influence transaction risk. All identified issues are entered into a shared issue log, assigned severity ratings, and prioritized for the subsequent reporting phase.

    Phase 3: Reporting, Remediation, and Deal Integration

    In Phase 3, our team synthesizes all findings into a comprehensive diligence report, beginning with an executive summary that highlights the most critical risks and opportunities. The report segments findings by financial, legal, and operational dimensions, each with a severity rating. Red flags—such as excessive customer concentration, material litigation, or compliance exposures—are escalated immediately and can influence valuation adjustments or the inclusion of special indemnities in the purchase agreement. Our reporting delivers the core M&A due diligence services as actionable intelligence that shapes the client’s negotiation posture. We typically hold a findings review session with the buyer’s leadership to walk through every issue and agree on remediation priorities. To bridge the gap between diligence and post-close execution, we use our Velocity Matrix to translate key risks into a structured 100-day integration plan. Once the diligence report is finalized, the findings directly inform the negotiation of the purchase agreement and integration planning.
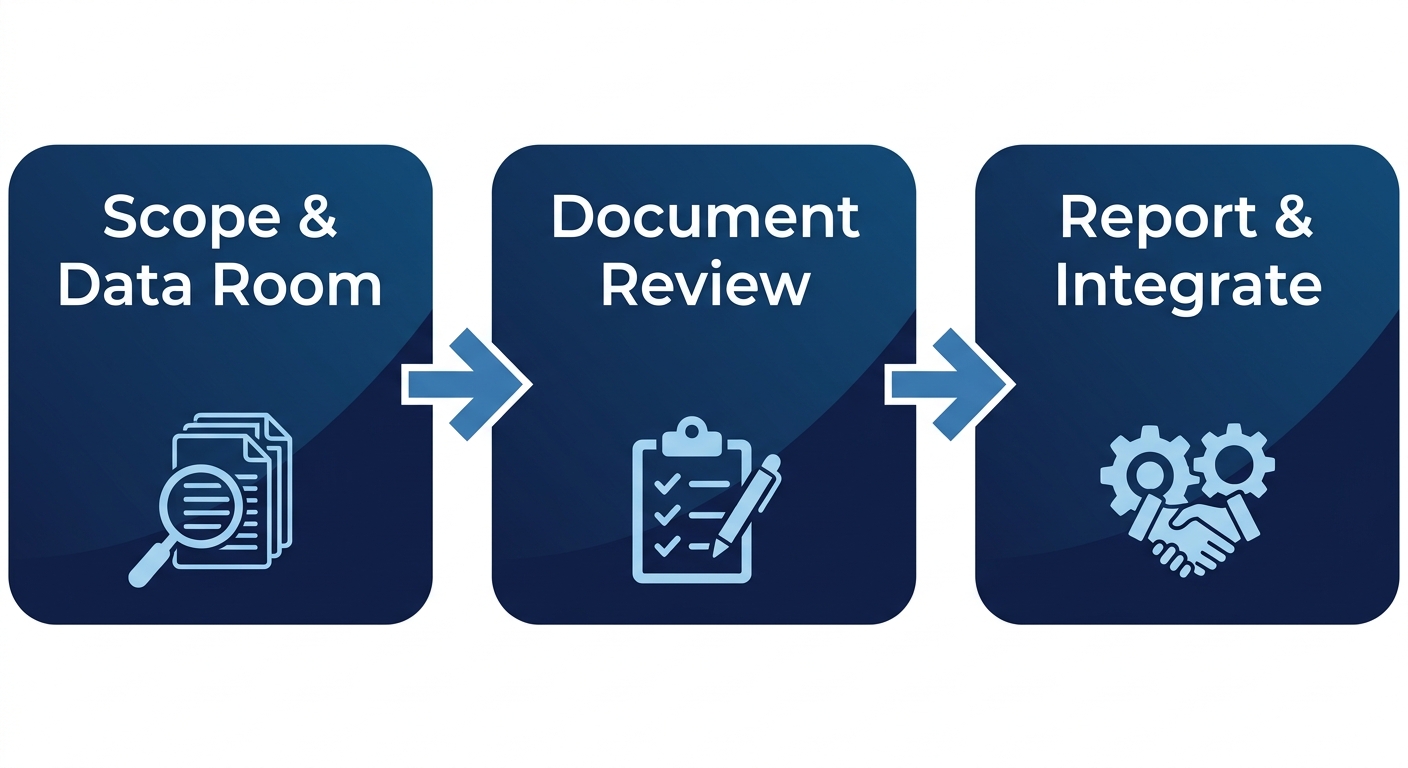
    M&A due diligence process flow diagram with three connected stages: scoping and data room preparation, document review and issue identification, and reporting with remediation and deal integration

    Due diligence process: Scoping, Review, Integration

    Practical Application of Due Diligence in M&A

    With the strategic importance of due diligence established, we now turn to its practical execution. When conducting due diligence in tech mergers and acquisitions, assembling the right team and timeline is critical. Our M&A due diligence services are anchored in a disciplined process that aligns financial, legal, and operational expertise to uncover risks and validate the deal thesis early.

    Assembling Your Diligence Team and Timeline

    A well-structured diligence engagement draws on three core roles: a financial advisor who leads the process—typically a boutique M&A firm like Zaidwood Capital—a legal counsel with deep M&A experience, and a technical or industry specialist who can assess operational and market realities. We converge these disciplines around a single checklist that maps every data request, interview, and verification step against a shared timeline.

    A sample 5-week timeline typically unfolds as follows:

    • Weeks 1-2 — Scoping and Information Request: Define the diligence scope, issue the initial document request list, and align client and target management on confidentiality protocols.
    • Weeks 3-4 — Intensive Review: Conduct document analysis, site visits, management interviews, and workstream-specific deep dives (financial, legal, operational, commercial).
    • Week 5 — Report Synthesis: Draft the due diligence report, isolate deal-breakers and conditions to closing, and present findings to the deal team.

    Pro Tip: Always verify key executives’ backgrounds before finalising the diligence timeline. Late-stage discoveries of litigation or misrepresentation can derail transactions, so we include these checks early.

    This collaborative staging keeps the entire team accountable and prevents last-minute surprises.

    Leveraging Data Rooms and Proprietary Tools

    A secure data room is a foundational piece of M&A diligence. Granular permissions, watermarking, and audit trails are non-negotiable. While basic cloud storage (Google Drive) works for small deals, most mid-market transactions demand virtual data room platforms like Intralinks or Ansarada with user-specific rights and detailed logs. For the highest-stakes cross-border scenarios, we rely on Zaidwood Capital’s Deal Vault, which leverages our Sovereign Data Nexus for air-gapped protection and end-to-end encryption.

    Comparison Table: Data Room Options for Due Diligence
    Provider TypeSecurity FeaturesIdeal For
    Basic cloud storage (e.g., Google Drive, Dropbox)Standard encryption, shared linksSmall, fast-moving deals where volume is low
    Virtual Data Room platforms (e.g., Intralinks, Ansarada)Granular permissions, audit trails, watermarkingMid-market M&A with multiple bidders
    Zaidwood Capital’s Deal Vault (private server)Air-gapped environment, Sovereign Data Nexus integrationComplex cross-border transactions demanding highest security

    Each tier matches deal complexity: basic for low-complexity asset sales, VDRs for multi-bidder auctions, and Deal Vault when sovereign-grade security is required.

    Beyond the data room, Precision Catalyst tracks investor engagement—document opens, time spent, repeat visits—flagging high-interest parties to accelerate follow-ups. This data-driven approach concentrates our M&A due diligence services on the most promising leads, shortening the overall diligence cycle.

    Synthesizing Findings into Actionable Reports

    Translating weeks of analysis into a decision-ready report requires discipline. We structure every due diligence report to be concise—typically 2–4 pages of core material plus supporting appendices—and to avoid absolute language. The standard sections include:

    • Executive Summary: A one-page synthesis of the target’s strategic fit, valuation range, and go/no-go recommendation.
    • Functional Findings: Separate subsections for financial, legal, operational, and commercial due diligence, each highlighting the top three risks and opportunities.
    • Deal-Breakers and Risk Matrix: A table that categorizes issues by severity and probability, clearly flagging items that could kill the deal.
    • Conditions to Closing: Concrete actions the target must complete before signing, such as resolving outstanding litigation, obtaining key customer consents, or cleaning up IP ownership.
    • Recommendations: Final guidance on whether to proceed, renegotiate terms, or walk away.

    This structure ensures every stakeholder—whether a CEO, private equity partner, or legal advisor—can grasp the essential picture in minutes and drill into the details as needed. The resulting report arms the deal team with clear conditions to closing, which we address in the next section on negotiation and deal structuring.

    Advanced M&A Due Diligence Strategies

    Building on the foundational due diligence framework, advanced strategies dive deeper into operational and sector-specific risks, especially in cross-border contexts. Our advanced M&A due diligence services in New York go beyond the financial basics, examining technology integration, regulatory exposure, and cultural alignment. This comprehensive approach is critical for deal success.

    For cross-border transactions, the data room requirements multiply significantly. We manage virtual data rooms that comply with diverse data residency laws and incorporate translation services, ensuring that parties in different countries can review documents securely and without legal friction. This operational infrastructure is a core part of our due diligence services, streamlining what is often a logistical bottleneck in international deals.

    Assessing cultural and operational fit is another vital layer of advanced M&A due diligence practices. In cross-border deals, we evaluate not only language barriers and business norms but also time-zone management and workforce integration. A typical domestic merger can stabilize in three to nine months, but international combinations often require six to eighteen months due to the need for deeper integration planning and trust-building. This extended timeline reinforces the need for patient capital and thorough vetting.

    Sector-specific expertise tailors these cross-border due diligence strategies further. For technology companies, advanced diligence includes IP ownership verification, a rigorous software code audit, a cybersecurity posture review, and subscription revenue validation. In healthcare M&A, our due diligence services cover HIPAA compliance, FDA regulatory pathways, clinical trial data integrity, and reimbursement dependencies. These strategies set the stage for executing a rigorous due diligence plan, which we cover next.

    Frequently Asked Questions About M&A Due Diligence

    Building on the steps above, we address some frequently asked questions about M&A due diligence.

    What is M&A due diligence and why is it important?
    Our M&A due diligence services provide a comprehensive evaluation of financial, legal, operational, and strategic factors to identify risks and support informed decisions.

    What key areas are assessed during M&A due diligence?
    We review financial statements, legal contracts, operational workflows, and strategic positioning, leveraging our Sovereign Data Nexus for data-driven insights.

    How does Zaidwood Capital support clients during M&A due diligence?
    Our M&A due diligence services combine Precision Catalyst for investor engagement and Velocity Matrix for rapid execution, ensuring efficient and thorough due diligence.

    This information is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to buy or sell any security.

    Close Your Deals with Confidence

    With preparation complete, execution is where confidence is built. As a Boutique M&A and Capital Advisory Firm, we rely on rigorous M&A due diligence services tailored to each deal’s unique risks and opportunities, reducing uncertainty at every stage. The Sovereign Data Nexus provides proprietary real-time data that validates assumptions, flags hidden risks, and delivers actionable intelligence. Backed by a global network and capital markets experience, the Velocity Matrix accelerates closing timelines, giving clients the transparency to close with confidence, and carrying that assurance into the post-close relationship.
    Resources

  • Healthcare Mergers and Acquisitions: Key Trends for 2026

    Healthcare Mergers and Acquisitions: Key Trends for 2026

    Table of Contents

    Understanding Healthcare Mergers and Acquisitions

    Healthcare mergers and acquisitions encompass transactions involving hospitals, pharmaceutical companies, biotech firms, and healthcare services. These can be horizontal (combining similar entities like hospital systems), vertical (acquiring a supplier), or conglomerate (diversifying across sectors).

    Drivers of current healthcare M&A trends include regulatory shifts, technological advances, cost pressures, and the pursuit of economies of scale. An aging population and the shift to value-based care further accelerate activity. They also prompt cross-sector partnerships and targeted investments in outpatient and digital care models. With the increase in private equity healthcare acquisitions, firms are pursuing platform investments and buy-and-build strategies.

    At Zaidwood Capital, our Boutique M&A and Capital Advisory Firm guides clients through Full-Cycle M&A, applying proprietary intelligence and a global network to navigate this complex landscape. In the following sections, we explore how specialized advisory firms orchestrate these transactions.

    The landscape of healthcare mergers and acquisitions is undergoing a fundamental transformation, driven by powerful market forces that are reshaping how providers, payers, and technology companies structure deals. Our analysis has identified several converging trends that are accelerating consolidation and redefining value creation in the sector, from record private equity participation to the rapid integration of digital health capabilities into traditional care delivery models.

    The Private Equity Surge in Healthcare

    Private equity has emerged as a dominant force driving current healthcare M&A trends, with deal volume concentrated heavily in physician practice groups, outpatient surgical centers, and specialty care platforms. This influx of capital reflects PE sponsors’ recognition that fragmented healthcare delivery offers substantial opportunities for operational improvement and economies of scale. Private equity healthcare acquisitions now frequently target multi-site platforms rather than individual practices, creating regional networks that can negotiate more favorable payer contracts while standardizing clinical protocols. We observe that these investors are increasingly sophisticated, bringing dedicated healthcare operating partners who understand the regulatory and reimbursement complexities that define the industry, rather than applying generic financial engineering approaches that characterized earlier investment waves.

    The competitive dynamics have intensified, with dry powder levels in healthcare-focused funds reaching unprecedented levels. This abundance of capital has compressed cap rates and elevated purchase multiples, particularly for assets demonstrating strong organic growth and technology-enabled service models. Our experience indicates that successful transactions now require rigorous upfront financial modeling and operational due diligence that goes well beyond traditional quality-of-earnings analyses, examining payer mix concentration, physician retention incentives, and compliance history with equal weight to historical financial performance.

    Technology Convergence Reshaping Deal Structures

    The intersection of healthcare delivery and tech mergers and acquisitions has introduced new complexity into deal-making, as AI-powered diagnostics, telemedicine platforms, and remote patient monitoring systems become core operational assets rather than ancillary tools. Digital health startups attracting significant investment are being valued on technology-forward metrics that blend traditional healthcare EBITDA multiples with SaaS-like recurring revenue frameworks, creating novel valuation methodologies that challenge conventional approaches. Our internal analysis, drawing on aggregated transaction experience exceeding $24.4 billion in volume, indicates that acquirers are willing to pay meaningful premiums for platforms demonstrating scalable technology infrastructure that can accelerate post-merger integration and unlock synergy realization timelines.

    This convergence demands that advisors possess cross-sector expertise spanning both healthcare reimbursement architecture and technology intellectual property considerations. The due diligence process has expanded to encompass algorithm bias assessments, interoperability standards verification, and data privacy compliance under frameworks that continue to evolve as regulatory bodies increase their scrutiny of health data monetization. We believe that the most successful transactions will be those where technology integration planning begins during initial deal evaluation rather than as a post-closing workstream, allowing acquirers to accurately model the true cost and timeline for achieving projected synergies.

    Regulatory Dynamics and the Role of Investment Banks

    Heightened Federal Trade Commission scrutiny and antitrust enforcement have introduced extended review timelines and greater uncertainty into healthcare M&A, particularly for horizontal combinations that concentrate market share within specific geographies or clinical specialties. Investment banks play an essential role in navigating these dynamics by structuring transactions with appropriate risk-mitigation mechanisms, including reverse breakup fees and clearly defined regulatory-effort covenants. Our advisory approach, grounded in full-cycle M&A execution across sectors including healthcare, technology, and energy, emphasizes early engagement with antitrust counsel to identify potential competitive concerns before they can derail transaction momentum. The shift toward value-based care and population health management continues to serve as a strategic imperative for consolidation, as integrated delivery networks seek the scale necessary to assume risk under alternative payment models and invest in the infrastructure required for care coordination.

    As these dynamics evolve, we anticipate that the pace of healthcare M&A will remain robust, with technology-enabled platforms and private equity portfolio companies continuing to drive deal flow across the middle market and upper-middle market segments.

    The Impact of Regulatory Changes on Healthcare M&A

    Recent changes in healthcare mergers and acquisitions regulation have introduced new layers of complexity for buyers and sellers navigating today’s deal environment. We see these regulatory shifts directly shaping the trends in healthcare M&A activity, from deal timelines to valuation methodologies. Our team at Zaidwood Capital monitors these developments closely, ensuring that every transaction we advise on reflects the latest compliance requirements and strategic considerations.

    The evolving regulatory landscape demands rigorous financial analysis grounded in established professional standards. The CFA Institute’s Code of Ethics and Standards provides a critical benchmark for ensuring fair-valuation opinions withstand scrutiny from all stakeholders. When we evaluate healthcare M&A trends, we recognize that deal volume increasingly correlates with regulatory predictability. For instance, private equity healthcare acquisitions have intensified in subsectors where reimbursement policies remain stable, while heightened antitrust oversight has cooled activity in concentrated hospital markets.

    Key regulatory bodies shaping healthcare dealmaking include:

    • Federal Trade Commission (FTC) and Department of Justice (DOJ): Enforce antitrust guidelines under the Hart-Scott-Rodino Act, with recent revisions increasing pre-merger notification thresholds and extending review timelines.
    • Centers for Medicare & Medicaid Services (CMS): Drives value-based care policies that directly impact hospital and physician practice valuations through reimbursement reforms.
    • Federal Communications Commission (FCC): Governs spectrum allocation and telecommunications compliance, including FCC regulatory compliance for transactions involving wireless health platforms or connected medical devices.

    Antitrust enforcement has intensified considerably, with the FTC and DOJ applying stricter scrutiny to healthcare consolidation. The updated Hart-Scott-Rodino thresholds now trigger more filings, while extended review periods compress deal timelines and increase regulatory risk for both parties. We advise clients to factor these procedural changes into their transaction planning from day one, as delays can materially affect financing arrangements and seller expectations.

    CMS reimbursement reforms under value-based care models have fundamentally altered how acquirers assess target financials. Practices with strong performance metrics under alternative payment models command premium valuations, while those dependent on traditional fee-for-service structures face discounting. Understanding these policy-driven valuation dynamics is essential for both strategic and financial buyers.

    For digital health transactions, FCC oversight introduces a cross-sector compliance dimension that many deal teams overlook. Whether a target holds spectrum licenses for telehealth platforms or operates connected medical devices, FCC regulatory compliance must be verified during due diligence. Failing to address telecommunications regulations can delay closings or create post-transaction liability.

    Understanding these regulatory impacts is critical before examining the role of private equity in healthcare. We believe that preparedness—supported by disciplined financial analysis and proactive regulatory engagement—remains the most effective strategy for navigating today’s complex deal environment and executing successful Full-Cycle M&A transactions.

    Private Equity’s Growing Role in Healthcare Acquisitions

    The landscape of healthcare mergers and acquisitions has been fundamentally reshaped by the accelerating influence of private capital. Institutional investors and fund managers now view the healthcare sector as a prime target for deployment, driven by powerful secular trends like an aging global population, rapid technology advancements and a steady push toward value-based care models. Understanding what is an investment bank reveals the essential intermediary that facilitates these complex private equity healthcare acquisitions, guiding both buyers and sellers through a disciplined transaction lifecycle.

    This surge in activity is not speculative. Consolidation in fragmented markets like outpatient services and physician practice management continues to accelerate. We see current healthcare M&A trends characterized by a fierce competition for tech-enabled healthcare platforms, where private equity sponsors seek to back companies with scalable software, data analytics and telemedicine capabilities. These platform investments often serve as a foundation for aggressive add-on acquisition strategies, allowing a portfolio company to rapidly expand its geographic footprint and service lines through a series of smaller, complementary healthcare mergers and acquisitions.

    When structuring these deals, private equity firms rely on several common transaction frameworks. A leveraged buyout uses the target’s assets and cash flows as collateral to secure acquisition financing, maximizing return potential through debt. Growth capital investments provide minority or majority stakes to fuel expansion without a full transfer of control. Add-on acquisitions, as noted, are the tactical tool for building a dominant platform. Each structure demands rigorous financial analysis to model returns and identify synergies.

    We at Zaidwood Capital, as a Boutique M&A and Capital Advisory Firm, provide the critical advisory services that make these frameworks actionable. Our team conducts comprehensive valuation analysis, manages multi-dimensional due diligence, and architects optimal deal structures that balance risk and reward. We then lead the capital syndication process, leveraging a global network of over 4,000 institutional and private investors to secure the necessary financing. To enhance this Full-Cycle M&A execution, we deploy our proprietary technology suite. Our Sovereign Data Nexus powers intelligent target identification and data vault management, Precision Catalyst refines investor engagement and Velocity Matrix is purpose-built to accelerate deal timelines without sacrificing diligence quality.

    It is important to state clearly that while we deploy these sophisticated tools and processes, outcomes are never guaranteed. Our role as your advisor is to maximize process efficiency and strategic positioning, not to promise specific deal terms or investment returns. The dynamic forces shaping healthcare mergers and acquisitions show no sign of slowing, and in the next section, we will explore the step-by-step process for executing a healthcare acquisition mandate with precision.

    This website is for informational purposes only and is not an offer, solicitation, recommendation, or commitment to buy or sell any security. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer. Investments involve risk and are not guaranteed to appreciate; investors may lose all or part of their investment. Consult with legal, tax, and financial advisors or a registered representative before making investment decisions. Past performance does not guarantee future results.

    Preparing Your Company for a Healthcare Merger

    Amid accelerating trends in healthcare mergers and acquisitions, companies that prepare thoroughly gain a critical competitive edge. While many preparation steps mirror those of substantial tech mergers and acquisitions, healthcare adds layers of regulatory scrutiny and operational complexity that demand a specialized approach. As Zaidwood Capital outlines in its M&A workflow, a structured, milestone-driven process is essential to maximizing transaction value.

    Understanding current trends in healthcare M&A is foundational because new developments—such as private equity’s deepening interest in digital health and the shift toward value-based care consolidation—are reshaping deal timelines and diligence requirements. Recognizing the landscape of private equity healthcare acquisitions early in your planning allows you to position your company as an attractive target for the most active and well-capitalized buyers in the sector.

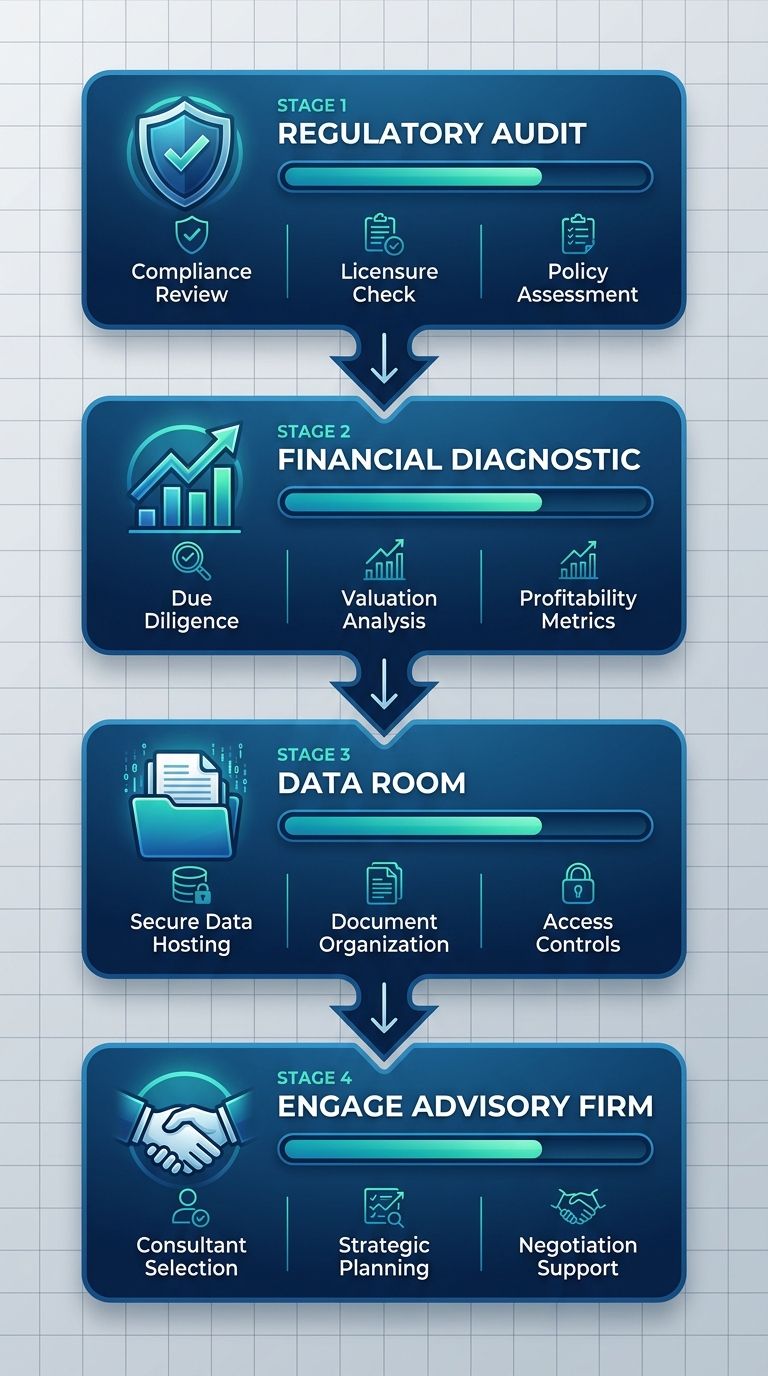
    • Conduct a Pre-Merger Regulatory Audit – Engage specialized counsel to review your compliance with HIPAA, the Stark Law, and FDA regulations. Addressing potential exposure before entering a transaction prevents deal delays and valuation discounts.
    • Perform a strategic financial diagnostic – Our team prepares the strategic documentation that buyers and investors expect: investor pitch decks, detailed business plans, and pro forma financial models. This diagnostic not only surfaces operational efficiencies but also demonstrates your company’s growth trajectory through rigorous, data-backed projections.
    • Organize a Confidential Data Room – We help you populate a secure Deal Vault so that patient data, payer contracts, and financial records are shared safely and efficiently. A well-organized data room signals institutional readiness and accelerates due diligence.
    • Engage a boutique M&A advisory firm – A Boutique M&A and Capital Advisory Firm with deep healthcare sector experience brings process discipline and strategic insight that generalist advisors cannot match. Zaidwood Capital deploys proprietary tools throughout preparation: Sovereign Data Nexus provides real-time market intelligence, Precision Catalyst optimizes investor targeting, and our Velocity Matrix compresses execution timelines.

    Zaidwood Capital emphasizes that the right advisory partner brings value far exceeding fees by aligning your preparation with the expectations of a global network of private equity and institutional investors. Our Full-Cycle M&A methodology ensures that no aspect of readiness is overlooked.

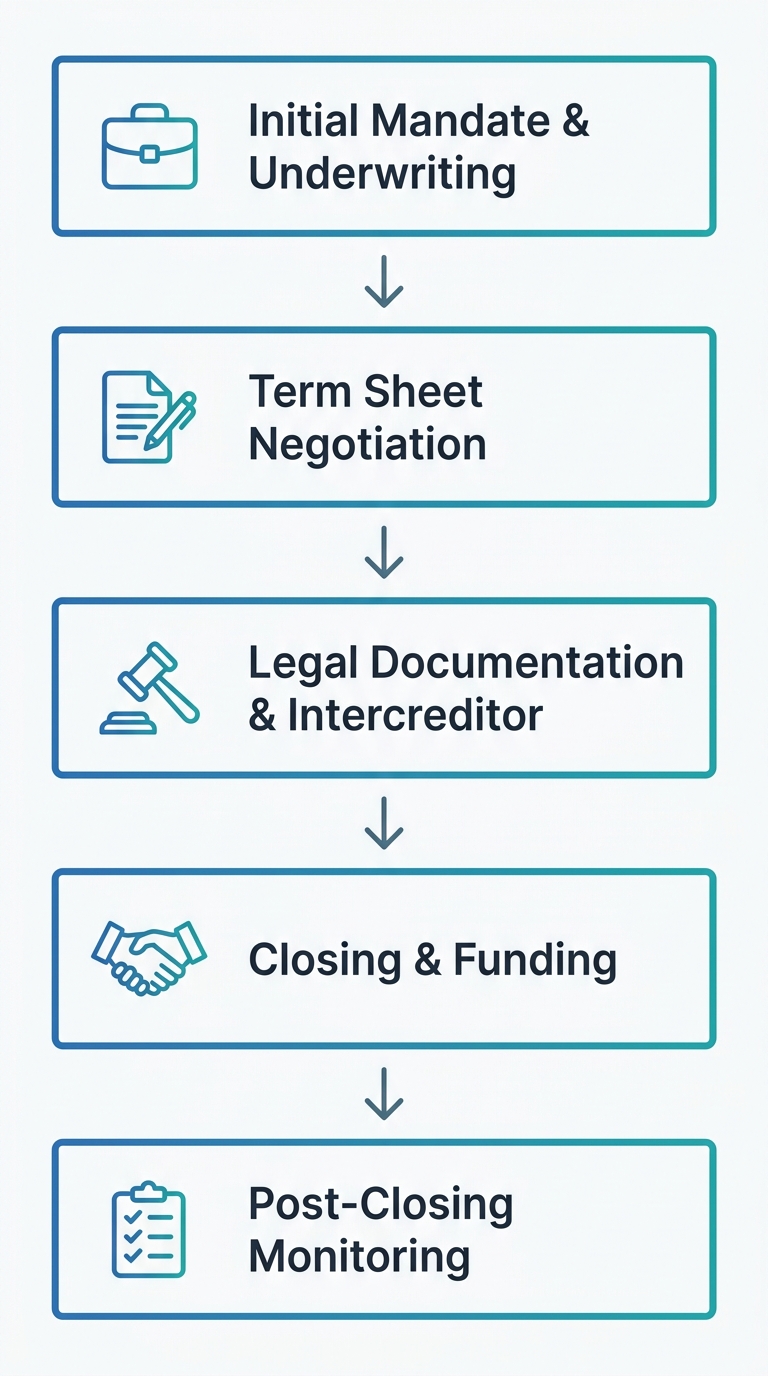
    Vertical process flow showing four stages for healthcare merger preparation: regulatory audit, financial diagnostic, data room setup, and engaging advisory firm.

    Four-step preparation process for healthcare M&A

    With a solid preparation foundation, the next critical phase is structuring the transaction—an area where Zaidwood Capital’s Full-Cycle M&A expertise excels. Contact Zaidwood Capital to begin your healthcare M&A preparation journey.

    How an M&A Advisory Firm Navigates Healthcare Transactions

    Given these unique challenges, an experienced M&A advisory firm approaches healthcare transactions with a careful, structured, sector-specific methodology. Healthcare deal-making requires far more than standard financial analysis—it demands deep regulatory fluency and the ability to identify value where others might overlook it. Our advisory team holds advanced credentials such as the CFA charterholder program, ensuring rigorous financial analysis and valuation discipline in healthcare mergers and acquisitions.

    Regulatory complexity is the defining feature of healthcare M&A. Every transaction must account for FDA approval pathways, HIPAA compliance obligations, and anti-kickback statutes that simply do not exist in other industries. Through our proprietary Sovereign Data Nexus infrastructure, we maintain continuously updated healthcare market data, enabling valuations that reflect not just historical performance but forward-looking regulatory risk. This data-driven approach, combined with our deep understanding of healthcare M&A trends, helps sellers position their assets more effectively and helps buyers understand exactly what they are acquiring from a compliance standpoint.

    Effective buyer targeting in healthcare transactions requires identifying both strategic acquirers—hospital systems, pharmaceutical companies, and payer organizations seeking vertical integration—and financial sponsors pursuing private equity healthcare acquisitions. Our Velocity Matrix methodology applies this segmented buyer intelligence to accelerate deal timelines through streamlined due diligence. By pre-packaging the compliance, reimbursement, and clinical data that healthcare investors prioritize, we can help reduce the friction that typically slows healthcare deal cycles.

    This full-cycle M&A capability extends from initial seller preparation and data room management through to post-close integration support. We continuously monitor healthcare mergers and acquisitions globally, integrating that intelligence into our post-close planning and investor outreach to improve execution timelines and clarity. As a Boutique M&A and Capital Advisory Firm, we bring Financial Services 3.0 infrastructure to every engagement—combining real-time analytics with the personalized guidance that complex healthcare transactions demand. Understanding this process reveals why engaging a specialized firm can deliver efficient outcomes for healthcare clients navigating today’s dynamic deal environment.

    Key Takeaways for Healthcare M&A Success

    Success in healthcare mergers and acquisitions demands a specialized, data-driven approach. Our experience navigating complex private equity healthcare acquisitions has shown that winning outcomes rely on a specific combination of proprietary intelligence and precise execution.

    • Sovereign Data Nexus is our foundational edge. Proprietary data access and private servers enable us to identify and evaluate healthcare targets with unmatched precision.
    • Precision Catalyst accelerates deal flow. Integrated digital marketing-driven investor engagement attracts the right capital partners for healthcare acquisitions.
    • Velocity Matrix ensures rapid closure. Our rapid execution capabilities help close healthcare M&A before market conditions shift.
    • Full-Cycle M&A expertise reduces risk. Guiding transactions from strategic documentation to post-merger integration maximizes value at every stage.
    • Deep sector knowledge is non-negotiable. Understanding regulatory dynamics, reimbursement models, and operational nuances separates successful healthcare M&A trends from costly missteps.

    Implementing these strategies with an experienced partner is the key to closing winning healthcare deals.

    Resources

  • Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Boutique vs Bulge Bracket Investment Banking: 2026 Comparison Guide

    Table of Contents

    Choosing Between Boutique and Bulge Bracket Investment Banking

    When weighing boutique vs bulge bracket investment banking, the core distinction lies in service scope and client intimacy. Specialist advisory firms offer focused, senior-led strategies that often result in faster execution and stronger alignment with client goals. Large global banks provide extensive capital markets access and resources suited for complex cross-border mandates. For companies considering private equity exit opportunities, boutique advisors frequently deliver customized positioning within their specific industry ecosystems. Similarly, talent dynamics around investment banking compensation packages reflect the differing demands of these models. We track SEC regulatory updates closely, as heavier compliance overhead affects larger institutions disproportionately while we leverage our full-cycle M&A and capital advisory approach to integrate deep advisory with proprietary data, streamlining transactions without the structural friction of multi-layered global firms.

    Ultimately, choosing between these paths depends on your transaction scope and strategic priorities. Our model bridges the gap by combining the personalized guidance of a boutique with the data-driven precision and investor network scale that growing companies require, a balance explored further in the next section.

    1. Senior Banker Attention and Personal Service

    In the boutique vs bulge bracket investment banking debate, one key differentiator is the level of senior attention you receive. At large, full-service firms, deal execution is often delegated to junior teams while managing directors appear only at critical milestones. We find this approach can dilute accountability and slow decision-making.

    Our model is fundamentally different. When you engage a boutique investment banking firm like Zaidwood Capital LLC, your mandate is led directly by our principals from pitch to close. As outlined in our description of M&A advisory services, senior bankers provide strategic guidance, valuation, negotiation support, and hands-on deal management throughout the entire lifecycle. This structure ensures decades of combined experience are applied to your specific strategic goals, delivering more tailored advice and faster execution.

    This personalized service is particularly valued by private equity firms seeking seamless exit execution and by companies requiring discreet, high-touch advisory. By leveraging our proprietary network and data resources, our senior team simplifies complex transactions, embodying our commitment to Streamlining Transactions with precision and focus.

    2. Tailored Fee Structures for Mid-Market Deals

    When considering boutique vs bulge bracket investment banking, the fee negotiation dynamics shift substantially for middle-market transactions. Unlike the rigid, standard pricing grids common at large institutions, we design our compensation around each mandate’s unique contours. This flexibility ensures your advisory costs reflect actual deal complexity rather than a one-size-fits-all schedule, aligning our incentives directly with your outcome.

    A typical framework might blend an initial retainer with a success-based component, or we may structure a milestone-driven fixed fee for a carve-out divestiture. The mix is always negotiated, absorbing variables like target size, cross-border diligence, and sector-specific resource requirements. For private equity firms managing portfolio company exits, this custom approach preserves more equity value while delivering institutional-quality execution. Our compensation benchmarks, detailed on our FAQ page, illustrate how tailored structures sit competitively within industry norms. As we always clarify, fees are custom-quoted and subject to mutual agreement rather than a published rate card.

    This disciplined yet adaptable approach removes friction from the engagement, letting you forecast costs with clarity. Next, we will walk through how our execution process turns that aligned structure into deal momentum.

    3. Specialized Industry Expertise

    Specialized industry expertise is a defining hallmark of the boutique model in investment banking. Unlike generalist institutions, boutique firms concentrate intellectual and relational capital into targeted verticals, cultivating an intimate understanding of sector dynamics, competitive landscapes, and value drivers. In private equity exit opportunities, this depth translates directly into superior deal sourcing because advisory teams speak the same operational language as founders, operators, and institutional buyers. Drawing from our own capital network exceeding $15 billion and an aggregate transaction volume surpassing $24.4 billion, we see consistent evidence that specialization sharpens valuation insight and accelerates execution.

    Sector-specific knowledge also shapes how boutique teams prepare portfolio companies for exit. Advisors often bring prior operating experience within the industries they serve, allowing them to anticipate buyer diligence questions and position assets around the metrics that matter most to private equity firms. When general partners evaluate acquisition targets, they rely on advisors who can interpret unit economics, regulatory nuances, and customer concentration risks without a learning curve, an advantage that industry depth systematically delivers.

    Industry depth shortens timelines and reduces transaction friction, qualities that matter acutely when fund lifecycles and market windows dictate exit timing. The structural alignment between boutique specialization and private equity mandates explains why sector-focused advisory teams continue gaining share in middle-market transactions. As the discussion shifts toward compensation structures, that same specialized expertise becomes a tangible factor influencing how transaction professionals are rewarded for execution.

    4. Agile Decision-Making and Speed

    Agile decision-making and speed represent some of the most compelling differentiators when evaluating boutique vs bulge bracket investment banking advisory services. At Zaidwood Capital, our lean, partner-led structure eliminates the multiple layers of approval and internal bureaucracy that typically slow down larger institutions. This streamlined architecture translates into faster, more decisive action for our clients.

    The role of an M&A advisor is inherently to accelerate deal timelines through proactive market intelligence and efficient coordination of due diligence. We execute this through our proprietary Velocity Matrix framework, which drives transaction velocity without compromising the depth or quality of our analysis. This systematic approach ensures that while we move quickly, we never sacrifice the financial, legal, and operational rigor that complex transactions demand.

    This responsiveness is particularly critical for owners pursuing private equity exit opportunities, where market windows can close rapidly and timing often correlates directly with value realization. Our direct partner involvement and efficient processes allow us to respond to these dynamics with the urgency they require. This structural speed also enables us to deliver a level of service intensity and personalization that more layered organizations find difficult to match.

    Agility here is not about cutting corners. It is the natural outcome of a flatter organizational design, empowered decision-makers, and a proprietary operating system purpose-built to optimize transaction timelines. This foundation of responsive execution supports the personalized and cost-effective approach that distinguishes true partnership in M&A advisory.

    5. Comprehensive Network Access and Deal Sourcing

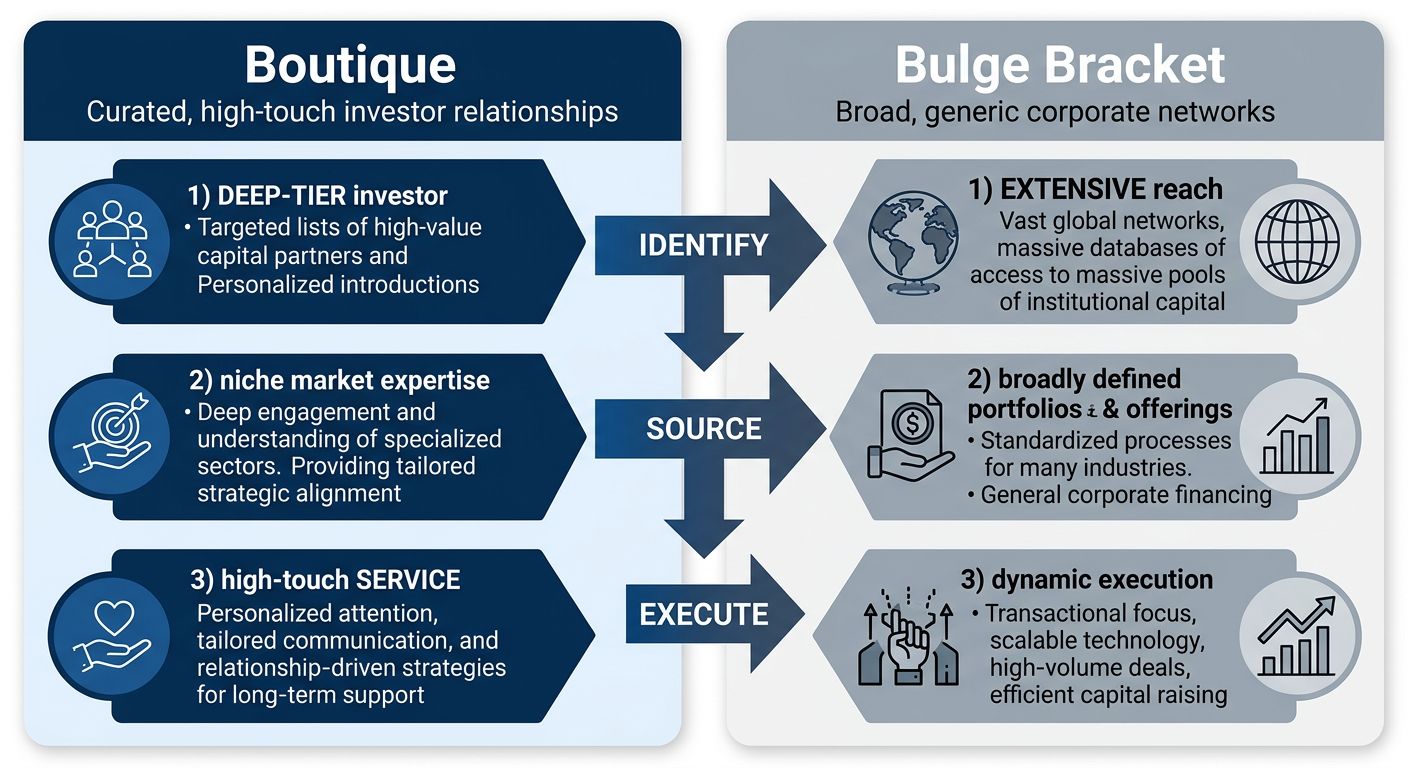
    Beyond our advisory capabilities, the real differentiator in the boutique vs bulge bracket investment banking landscape is the depth of our network. We connect clients with 4,000+ global investors and $15B+ in deployable capital, creating private equity exit opportunities that rival the largest institutions while maintaining the agility of a specialized boutique.

    Infographic comparing boutique M&A firm's high-touch investor network against bulge bracket's broad corporate network with deal sourcing funnel stages.
    Boutique vs. bulge bracket network access comparison at Zaidwood Capital.

    This integrated approach is powered by proprietary tools, including the Sovereign Data Nexus, Precision Catalyst, and Velocity Matrix, which sharpen deal sourcing and analysis. Our $24.4B+ aggregate transaction volume across full-cycle M&A, equity, and debt mandates confirms the scale we deliver. Exclusive access to Deal Vault and our curated Investor Rolodex further extends our partners’ reach. As our internal resources explain, these capabilities streamline the entire capital formation lifecycle, from LP placement and debt structuring to equity advisory.

    Whether you are evaluating private equity exit opportunities or structuring a capital raise, this institutional-grade infrastructure, delivered by a boutique firm, provides a clear advantage over traditional bulge bracket models. Our approach ensures you receive both the scale and the personalization that today’s complex deals demand. We’ll next explore how our fairness opinions and transaction advisory services add another layer of diligence.

    6. Cultural Alignment and Communication

    The choice in boutique vs bulge bracket investment banking extends beyond structure and into the softer, yet equally critical, dimensions of culture and communication. At Zaidwood Capital, we believe that a strong advisory relationship depends on transparency, trust and open dialogue — qualities that are built through consistent interaction rather than brand reputation alone. How a firm communicates directly shapes your experience during what is often the most consequential financial event in a company’s lifecycle.

    Communication style and responsiveness matter because M&A processes move quickly and demand real-time judgment. Boutique firms typically offer direct access to senior partners and a highly personalized cadence, while larger platforms operate through more structured teams and formalized reporting. Neither approach is inherently superior; the right fit depends on how you prefer to receive information, make decisions and manage pressure. Our internal resource on what M&A advisors do outlines how advisors facilitate fit assessments early in the process, helping clients evaluate both technical capability and interpersonal compatibility.

    Finding the right cultural fit also means considering how an advisor handles long-term strategic goals such as private equity exit opportunities or structuring investment banking compensation packages. These conversations require discretion, deep industry knowledge and a relationship grounded in mutual confidence. Full-Cycle M&A mandates succeed when the advisory team aligns with your organization’s values, communication norms and decision-making rhythm — a principle we prioritize through every phase of engagement.

    Streamlining Transactions depends as much on human chemistry as it does on financial engineering. In our experience, the most successful partnerships are those where both sides invest in candid, ongoing communication. The next section outlines practical steps you can take to evaluate and engage an advisor who fits your unique organizational culture.

    Making the Right Choice for Your M&A Needs

    Given the distinct advantages of each model, selecting the right advisor depends on your transaction size, industry focus, and desired level of partner attention. M&A advisors typically provide comprehensive support across buy-side and sell-side representation, valuation, due diligence, and deal negotiation. At Zaidwood Capital, we deliver Full-Cycle M&A and capital advisory that combines the personalized service of a boutique firm with access to over 4,000 institutional investors and $15B+ in deployable capital. Our approach ensures seamless execution from initial due diligence through final closing, backed by $24.4B+ in aggregate transaction volume. We encourage you to assess your specific requirements and book a call for tailored guidance on your M&A journey.

    Resources

  • What Is NAV Financing in Private Equity? A Complete Guide

    What Is NAV Financing in Private Equity? A Complete Guide

    Table of Contents

    NAV financing in private equity represents a sophisticated form of fund-level leverage secured against the net asset value of a private equity fund’s portfolio of companies. Unlike traditional fund-level debt, which may rely on general partner or limited partner guarantees, these asset-backed credit facilities derive their security primarily from the underlying portfolio’s appraised worth. As leaders in Full-Cycle M&A and capital advisory, we at Zaidwood Capital structure these facilities to provide sponsors with a flexible, non-dilutive capital solution that aligns with the fund’s existing asset base while preserving its long-term investment strategy.

    This form of fund-level leverage has gained traction for several common applications. Sponsors frequently use NAV facilities to accelerate distributions to limited partners, avoiding the need for a full asset sale when liquidity is desired. They also serve as a bridge for follow-on investments, enabling a fund to support portfolio company add-on acquisitions between traditional capital calls. The Institutional Limited Partners Association (ILPA) has acknowledged the growing role of fund-level credit, emphasizing in its guidance that any such leverage must be aligned with fiduciary duties and transparent for LP stakeholders.

    Our firm’s capital advisory services encompass the entire lifecycle of NAV financing, from initial eligibility analysis and lender identification to term negotiation and closing. With access to extensive institutional networks and deep expertise in asset-backed structures, we help sponsors navigate the complexities of these loans.

    Fundamentals of NAV Financing and Fund-Level Leverage

    Building on the overview of fund capital strategies, we now examine two core forms of fund-level leverage: subscription lines and NAV financing. Fund-level leverage refers to the strategic use of debt by a fund itself, most commonly through subscription lines or NAV-based credit facilities.

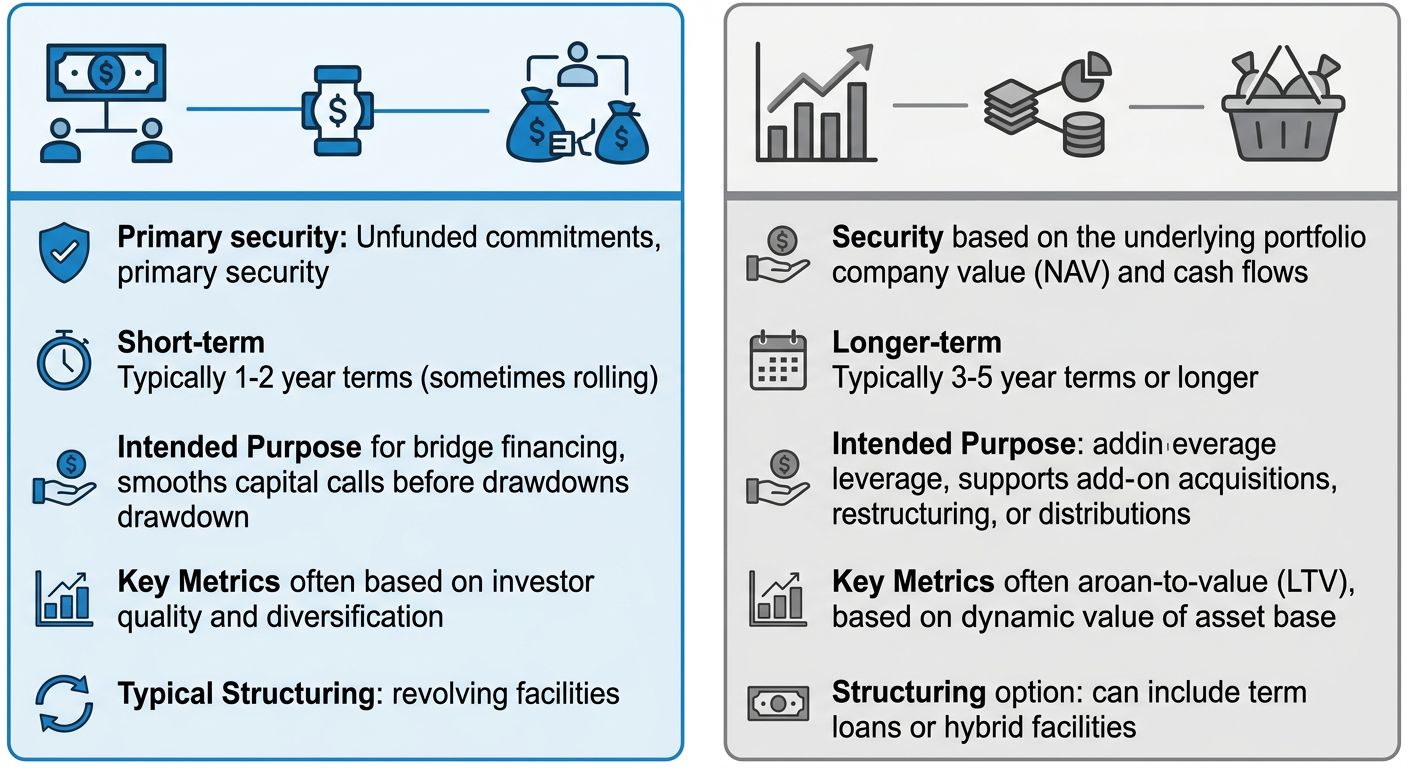
    Comparison: Subscription Lines vs. NAV Financing Facilities

    The following table provides a direct comparison of these two prevalent forms of fund-level leverage:

    FeatureSubscription LineNAV Financing
    PurposeFund capital callsFund distributions and acquisitions
    CollateralUnfunded commitmentsPortfolio company value
    Typical Terms1-2 years3-5 years
    Two-column comparison infographic contrasting subscription line financing with NAV financing terms.

    Comparison of subscription line and NAV financing terms and features for fund-level leverage.

    The Mechanics of NAV Loans: Structure, Growth Drivers, and Key Terms

    Growth Drivers Behind NAV-Based Lending in 2026

    DriverImpact on DemandExample Scenario
    LP Distribution PressureGPs need to return capital without exiting positionsBridge distributions with NAV facility
    Dry Powder OverhangUninvested capital pushes GPs to seek leverageUse NAV to fund follow-on acquisitions
    Regulatory EvolutionBasel IV makes subscription lines less attractiveNAV lines offer off-balance-sheet treatment

    Structuring NAV Loan Facilities: Key Components

    The architecture of a typical NAV financing in private equity facility rests on a few core components. The borrowing base is derived from the aggregate NAV of the portfolio companies. Lenders then apply an advance rate, typically ranging between 10 and 20 percent of that NAV.

    How NAV Financing Creates Value for Private Equity Funds

    The strategic value of NAV financing extends beyond liquidity. By using NAV loans, GPs can smooth fund-level returns and avoid fire sales of portfolio assets during market dislocations. Specialized debt advisory services from firms like Zaidwood Capital help navigate these structures.

    How Private Equity Firms Use NAV Financing for Distributions and Growth

    Use CaseTypical Advance RateCollateral Pool
    LP Distribution10-15% of NAVPortfolio companies
    Follow-On Acquisition20-30% of NAVTarget + existing portfolio

    Distributing Returns to Limited Partners via NAV Facilities

    Rather than selling assets at a suboptimal time, sponsors borrow against the fund’s net asset value and distribute the proceeds to investors.

    Using NAV Financing for Follow-On Acquisitions

    GPs draw on pre-arranged NAV financing facilities to move immediately when an acquisition opportunity emerges.

    Practical Steps to Secure a NAV Loan Agreement

    Securing a NAV facility requires a structured approach. Our corporate advisory services team at Zaidwood Capital negotiates with a network of over 3,000 lenders.

    Advanced Considerations in NAV Financing: Risk Management and Best Practices

    Risk FactorDescriptionMitigation Strategy
    Portfolio OverleverageAdding debt at fund levelMaintain conservative LTV ratios
    Valuation VolatilityNAV fluctuations affect borrowingRegular mark-to-market

    Common Questions About NAV Financing in Private Equity

    What is NAV financing in private equity? It is a form of fund-level leverage secured against a portfolio’s net asset value.

    Maximizing Fund Returns with Strategic NAV Financing

    At Zaidwood Capital, our debt advisory and capital formation capabilities support general partners in designing tailored financing structures.

    Resources

  • Middle Market M&A Trends 2026: Expert Guide to Private Equity

    Middle Market M&A Trends 2026: Expert Guide to Private Equity

    Table of Contents

    The middle market M&A trends 2026 are reshaping the dealmaking environment through several interconnected forces:

    • Private credit unitranche financing is replacing traditional capital stacks, simplifying structures and reducing closing friction.
    • Record private equity dry powder is driving aggressive consolidation, particularly in mid-size sectors.
    • Proprietary data platforms, including Zaidwood Capital’s Velocity Matrix, are Streamlining Transactions by cutting due diligence timelines and widening buyer visibility.
    • Shifting interest rate expectations and regulatory scrutiny are compressing deal windows, elevating the importance of speed and precision.

    These dynamics are redefining the middle-market M&A landscape in 2026. According to Zaidwood Capital’s analysis of leading M&A advisors, firms that embed data-driven execution and full-cycle capabilities are winning mandates. Our own Full-Cycle M&A and capital advisory approach integrates these innovations, helping clients capitalize on these middle market deal trends before the window closes. The following section examines how leading advisory firms align with each of these forces.

    1. Rising Deal Volume and Momentum

    Middle market M&A trends 2026 point to a significant acceleration in deal volume as we move through the first half of the year. Across the U.S. middle market, transaction activity is building momentum driven by a convergence of favorable conditions that are reshaping how deals get done. The surge in deal volume has placed increased demand on M&A advisors who can navigate this increasingly complex landscape with precision.

    A primary catalyst is the expanded availability of private credit unitranche financing, which has become a preferred debt solution for sponsors and companies alike. By blending senior and subordinated debt into a single facility, unitranche structures streamline execution and provide certainty of close — a critical advantage in competitive processes. This financing innovation directly fuels the 2026 mid-market M&A momentum we are observing.

    At the same time, record levels of private equity dry powder deployment are intensifying competition for quality assets. With substantial uninvested capital waiting to be deployed, sponsors are under pressure to transact, driving valuations higher and accelerating timelines. According to Federal Reserve System data, the current interest rate environment — while still elevated relative to the prior decade — has provided enough stability for buyers and sellers to align on pricing expectations, removing a major impediment to deal activity.

    As deal momentum builds, the financing structures and institutional players driving these transactions warrant closer examination.

    2. Sector Spotlight: Where M&A Activity Is Concentrated

    Building on the broader M&A landscape, middle market M&A trends 2026 point to a clear concentration of activity across several key industries. Our analysis, informed by internal expertise in cyber security consulting and deal execution, identifies the technology sector as the undisputed leader. Demand for AI, cloud infrastructure, and heightened security needs are compelling companies to consolidate at a rapid pace.

    Beyond technology, we observe significant sector concentration in healthcare and life sciences, driven by an aging global demographic and an accelerating pace of innovation. The energy transition and cleantech sectors are also emerging as major M&A hot spots, fueled largely by governmental incentives and corporate sustainability commitments. This broad-based activity is being supercharged by private equity dry powder deployment, as sponsors actively seek platform investments in these favored niches.

    • Technology: Dominated by cybersecurity and AI-driven scalability.
    • Healthcare: M&A centered on biotech innovation and service consolidation.
    • Energy: Deal activity focused on renewables and grid infrastructure.

    Geographically, North America remains the epicenter for these transactions, though deal flow in Europe and select Asia-Pacific markets is rising. Understanding which sectors are active sets the stage for examining the top advisory firms driving these deals.

    3. Private Credit Unitranche Financing Reshaping the Landscape

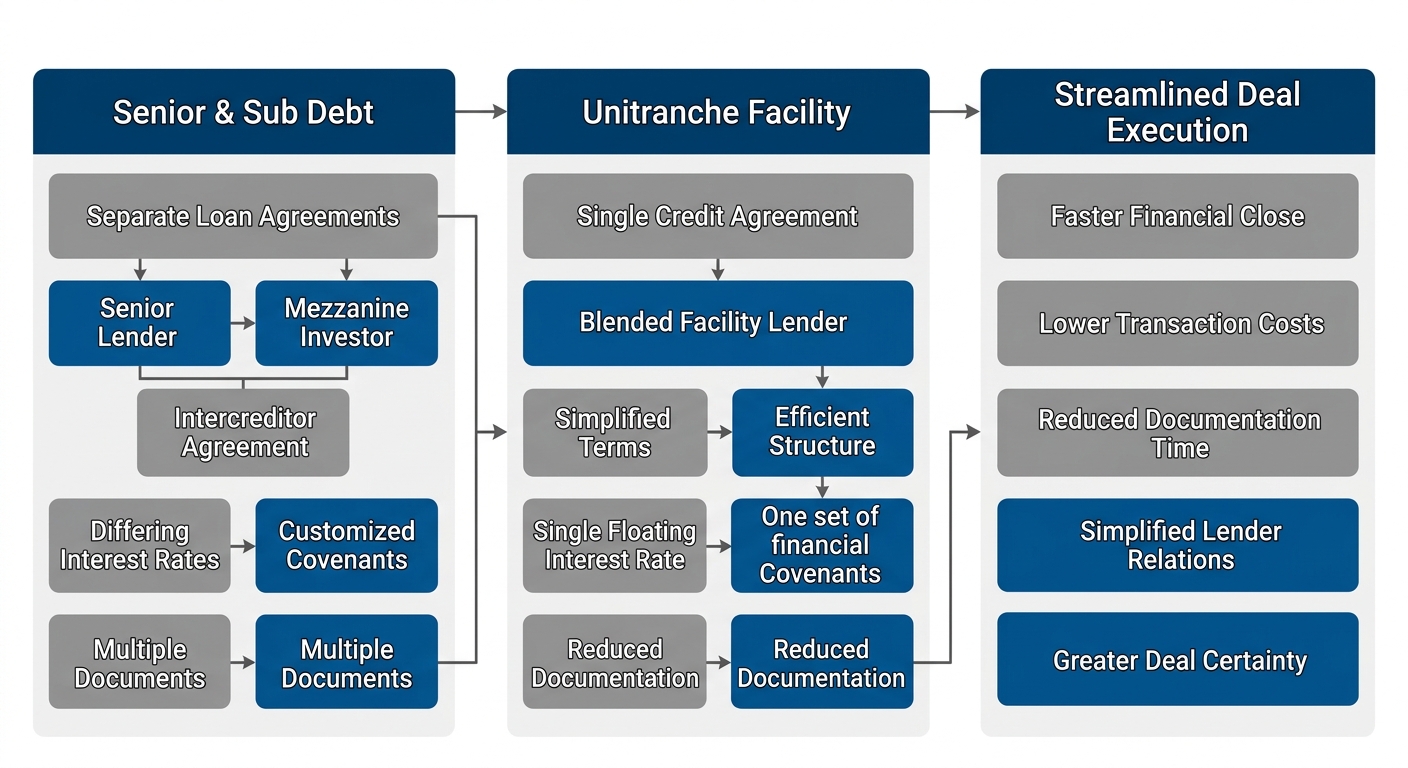
    Building on the broader M&A advisory trends, unitranche financing has emerged as a transformative force in middle-market deal execution. A single-tranche facility combines senior and subordinated debt into one combined debt instrument, offering both speed and simplicity for buyers and sellers navigating complex transactions.

    Leading advisory firms increasingly recommend unitranche structures, evidenced by the criteria Zaidwood Capital uses to identify top M&A advisors—transaction volume, network access, and specialized industry expertise. Our full-cycle M&A and capital advisory approach connects clients with over 4,000 institutional investors, streamlining transactions through proprietary frameworks like the Velocity Matrix.

    These unitranche structures align with capital market standards established by the International Capital Market Association (ICMA), ensuring documentation practices meet global benchmarks for transparency. This alignment with Financial Services 3.0 principles reduces the need for separate capital layers, accelerating close times significantly.

    For middle market m&a trends 2026, private credit unitranche financing enables more leveraged buyouts and growth equity transactions. Our Sovereign Data Nexus and Precision Catalyst methodology provide the execution speed modern dealmakers require.

    Horizontal process-flow diagram with three connected boxes labeled Senior & Sub Debt, Unitranche Facility, and Streamlined Deal Execution, using blue and gray colors.

    Illustration of unitranche financing mechanics combining senior and subordinated debt into a single facility.

    Through our extensive investor network and disciplined deal structuring, we facilitate unitranche transactions that deliver certainty and efficiency—foreshadowing how these financing innovations directly influence deal execution strategies in the sections ahead.

    4. Interest Rates and Their Impact on Deal Financing

    In middle market M&A trends 2026, interest rate impact remains a decisive variable shaping deal financing strategies. The federal reserve system has set the fed funds target range at 3.50% to 3.75%, directly influencing the cost of senior debt, mezzanine financing and unitranche financing structures. When rates rise, borrowing costs climb and private equity firms often adjust by lowering leverage ratios and increasing equity contributions to maintain acceptable returns.

    We observe that private credit unitranche financing has gained prominence in the current higher-rate environment as borrowers seek alternatives to traditional bank debt. This single-tranche solution simplifies capital structures and can provide covenant flexibility that syndicated loans lack.

    The rate environment also drives sponsor behavior. Common adjustments we see include:

    • Prudent leverage reduction to offset higher interest expense
    • Greater equity checks to de-risk capital structures
    • Increased use of floating-to-fixed rate swaps

    Top M&A advisory firms—including Goldman Sachs, Morgan Stanley and Houlihan Lokey—help clients structure financing to mitigate rate risk. At Zaidwood Capital, we provide Full-Cycle M&A and capital advisory, supporting clients with debt and equity advisory to navigate rate volatility while preserving deal momentum.

    With rates redefining cost of capital, the next section examines specific financing structures—such as unitranche debt and equity solutions—that can optimize outcomes in this dynamic environment.

    5. Valuation Multiples and the Dry Powder Effect

    In the landscape of middle market M&A trends 2026, understanding valuation multiples is essential for buyers and sellers alike. A valuation multiple — often expressed as an EBITDA multiple — represents the ratio of a company’s enterprise value to its earnings before interest, taxes, depreciation, and amortization, serving as a standardized metric for comparing deal pricing across transactions. In the middle market, these multiples typically range based on company size, sector dynamics, and growth trajectory, with premium valuations reserved for businesses demonstrating scalable operations and defensible market positions. As we observe current 2026 middle market deal trends, the interplay between abundant capital and limited quality assets continues to reshape pricing expectations.

    The dry powder effect — the accumulation of uninvested private equity dry powder capital — has become one of the most significant forces driving valuation multiples upward heading into 2026. Record levels of dry powder reported through 2024-2025, estimated in the trillions globally, have intensified competition for quality middle market assets as fund managers face deployment deadlines. This oversupply of capital chasing a finite pool of attractive acquisition targets creates natural upward pressure on purchase multiples, a dynamic that aligns with the broader mid-market M&A outlook for sustained elevated pricing. Buyers armed with significant dry powder are increasingly willing to stretch valuation parameters to secure platform investments and add-on acquisitions that strengthen their portfolio strategies.

    Supporting this high-multiple environment, private credit unitranche financing has emerged as a critical enabler for acquirers looking to bridge valuation gaps. Unitranche structures combine senior and subordinated debt into a single facility, streamlining execution and reducing refinancing risk — key advantages when aggressive bidding pushes enterprise values beyond what traditional senior lenders are willing to support. This financing flexibility allows buyers to compete effectively in auctions and negotiate with confidence, reinforcing the competitive bidding dynamics that characterize today’s middle market. Sectors such as technology, healthcare, and business services have seen particularly pronounced multiple expansion, though the degree of premium varies significantly by industry and company size.

    Navigating this high-multiple, high-competition environment demands sophisticated advisory support. Our comparative analysis of the best M&A advisors for 2026 highlights firms with the sector expertise and transaction experience necessary to maximize outcomes under these conditions. Similarly, our overview of top M&A advisory firms identifies the capabilities clients need when facing competitive processes influenced by significant dry powder deployment. At Zaidwood Capital, we bring full-cycle M&A and capital advisory expertise to every engagement, leveraging our access to over 4,000 institutional investors and deep transaction experience to help clients achieve optimal results in an increasingly complex market.

    6. Private Equity Dry Powder: The Urgency to Deploy

    In examining current middle market M&A trends 2026, one fundamental driver stands apart: private equity dry powder. This term describes the massive pool of committed capital that private equity firms have raised from limited partners but have not yet invested. As these unallocated reserves reach historically high levels, fund managers face an intensifying race against predefined investment periods. Capital that sits idle beyond its mandated deployment window risks being returned to investors, creating a structural urgency that directly fuels acquisition activity across the middle market.

    We see how this private equity dry powder deployment timeline pushes sponsors toward decisive action. Competing funds vie for quality assets before investment horizons expire, compressing due diligence cycles and elevating the importance of accelerated execution. In this environment, private credit unitranche financing has emerged as an alternative capital tool that can streamline deal timelines by combining senior and subordinated debt into a single facility. Navigating this accelerated deal landscape demands precision, and our resources on top M&A advisory firms provide guidance for those seeking expertise in Full-Cycle M&A execution. This urgency to deploy makes an experienced advisor less of a luxury and more of a competitive necessity.

    7. Regulatory Shifts and Macroeconomic Considerations

    Understanding middle market M&A trends 2026 requires examining the evolving regulatory and economic landscape that directly shapes financing dynamics. The U.S. Securities and Exchange Commission continues to refine disclosure requirements and rulemaking agendas—including recent proposals to rescind certain Regulation NMS Rules—while providing essential SEC investor tools that help market participants stay informed about compliance obligations affecting transaction structures.

    The Board of Governors of the Federal Reserve System maintained a Fed Funds Target Range of 3.50% to 3.75% as of mid-2026, with PCE inflation at 3.8% and GDP growth at 1.6% in Q1, according to official data. This rate environment sustains elevated financing costs for leveraged transactions while simultaneously fueling demand for private credit unitranche financing as sponsors seek flexible alternatives to traditional bank lending. The persistence of approximately $1.5 trillion in private equity dry powder deployment pressure continues driving middle-market deal activity despite macroeconomic headwinds, creating a complex environment where regulatory fragmentation across state and federal jurisdictions demands sophisticated advisory capabilities.

    At Zaidwood Capital, our Full-Cycle M&A and capital advisory approach helps clients navigate these intersecting forces—translating regulatory complexity and monetary policy signals into actionable transaction strategies without making assumptions about guaranteed outcomes.

    8. Operational Due Diligence and Full-Cycle Advisory Imperative

    As middle market m&a trends 2026 accelerate transaction timelines, operational due diligence has emerged as a decisive factor beyond traditional financial review. This discipline assesses a target’s operations, supply chain resilience, IT infrastructure, and human capital — areas where fragmented advisory can create blind spots. When legal, financial, and operational workstreams operate in silos, inefficiencies multiply, particularly as competition intensifies.

    Rising private credit unitranche financing demands deeper operational underwriting from lenders, who now scrutinize continuity and integration readiness as closely as debt-servicing capacity. Concurrently, record private equity dry powder deployment forces buyers to differentiate through execution certainty rather than price alone. A robust operational due diligence framework becomes the differentiator.

    We address these pressures through full-cycle advisory, a model that unifies pre-deal strategy, execution, and post-merger integration under a single, coordinated process. By leveraging proprietary tools like the Velocity Matrix, we streamline transactions without compromising rigor — a necessity in the middle market today. This integrated approach sets the stage for the execution frameworks we detail next.

    Capitalizing on 2026 M&A Opportunities

    The middle market m&a trends 2026 point to a landscape ripe with transaction potential driven by structural shifts in financing and capital availability. Private equity dry powder continues to accumulate, creating urgency among sponsors to deploy capital into disciplined acquisition strategies. Simultaneously, private credit unitranche financing has matured as a flexible, single-tranche solution that simplifies deal execution and accelerates closing timelines for mid-sized transactions.

    These tailwinds do not guarantee outcomes—deal success depends on precision in execution. Drawing on insights from our internal FAQ on what makes a top M&A advisory firm, we believe the firms that capture these opportunities will be those with full-cycle capabilities, deep institutional networks, and sector-specific expertise. As middle market m&a trends 2026 intensify competition for quality assets, our team at Zaidwood Capital brings together capital advisory, due diligence rigor, and access to a global investor base to help clients move from analysis to action without crossing into broker-dealer services.

    Resources

  • Choosing the Right Mezzanine Debt Structures: Key Considerations

    Choosing the Right Mezzanine Debt Structures: Key Considerations

    Table of Contents

    Understanding Mezzanine Debt Structures

    Mezzanine debt structures are hybrid financing instruments that sit between senior secured debt and common equity in a company’s capital stack. Often viewed as junior capital, mezzanine debt fills the gap when conventional senior loans reach their capacity. This content is for informational purposes only and is not an offer, solicitation, or investment advice. Zaidwood Capital LLC is not a registered broker-dealer.

    Mezzanine debt is a form of subordinated debt financing that typically does not require hard collateral. Instead, lenders are compensated with a higher interest rate and an equity kicker—often warrants or conversion rights—which provides upside participation in the borrower’s success. This combination of debt and equity features makes it a flexible tool for companies needing capital beyond what senior lenders will provide. By taking a junior position, mezzanine lenders assume greater risk but also capture more of the company’s value creation.

    Mezzanine debt structures commonly bridge funding gaps in leveraged buyouts, acquisitions, and growth capital transactions where senior debt limits are reached but equity dilution is undesirable. Unlike unitranche debt, which combines senior and mezzanine layers into a single facility, traditional mezzanine structures remain clearly subordinated and offer lenders deeper equity participation.

    Engaging a debt advisor can simplify the sourcing and negotiation of mezzanine terms. At Zaidwood Capital we connect clients to a network of over 4,000 institutional and private investors with more than $15 billion of deployable capital, streamlining the process. Zaidwood Capital’s global lending services provide access to institutional investors and specialized debt funds that may not be reachable through conventional banking channels. This access is critical for firms that lack existing relationships with mezzanine providers.

    Of course, every transaction depends on the company’s specific situation, and no outcome is guaranteed. Our role is to present options, not promise particular results.

    Mezzanine Debt in the Capital Stack: Position, Pricing, and Purpose

    Within this layered structure, mezzanine debt occupies a distinctive position as the bridge between senior secured loans and pure equity. We view mezzanine debt structures as a flexible layer that is structurally subordinated to senior lenders but holds priority over equity holders in repayment and asset claims. This middle placement means mezzanine investors take on a moderate-to-high risk profile, reflecting the fact that they are repaid only after senior obligations are satisfied, yet before any residual value flows to equity.

    The following comparison table highlights how mezzanine fits within the capital stack alongside senior debt and equity:

    Mezzanine vs Senior Debt vs Equity in the Capital Stack
    AttributeSenior DebtMezzanine DebtEquity
    Position in StackFirst claim on assets and cash flowSubordinated to senior, senior to equityLowest priority, residual claim
    Risk LevelLowModerate to highHighest
    Typical ReturnLIBOR + 200-400 bps10-20% blendedVariable, target IRR 20%+
    Control RightsCovenants onlyMay include warrants or conversionVoting rights and board seats

    Senior debt holds the first claim on cash and assets; equity sits at the bottom targeting 20%+ IRRs and holding voting control. Mezzanine debt sits between them, subordinated to senior but senior to equity, typically offering a 10–20% blended return through interest, PIK, and equity-linked features such as warrants or conversion rights. Its control rights can include board observation or conversion triggers, providing a middle path.

    The 10–20% blended return commonly seen in mezzanine debt structures arises from a mix of contractual interest payments, payment-in-kind (PIK) accruals, and equity upside through warrants or conversion rights. Because mezzanine sits below senior debt in the capital stack, its risk profile is elevated; investors accept that they will be repaid only after all senior obligations are met. For this reason, mezzanine debt is often categorized as subordinated debt financing. In certain transactions, lenders may combine the senior and mezzanine layers into a single unitranche debt facility, streamlining documentation and reducing execution complexity. At Zaidwood Capital, we evaluate these structures against a company’s cash flow projections and strategic ambitions to build capital stacks that align risk and return profiles with long-term objectives.

    Mezzanine financing is most frequently used when a company’s senior debt capacity is exhausted, yet equity dilution is undesirable. Typical use cases include growth capital for expansion, acquisition financing, leveraged buyouts, and recapitalizations where flexible capital bridges the gap between senior debt and equity without ceding control. At Zaidwood Capital, our global lending services encompass mezzanine debt as a core component of the capital solutions we design—integrating subordinated debt financing and, where appropriate, unitranche debt structures that combine senior and mezzanine layers to streamline execution. This approach allows us to tailor risk-return profiles that match a company’s cash flow dynamics and strategic goals.

    While senior debt offers security and equity captures upside, mezzanine debt bridges the two with a balanced risk-return profile, providing essential flexibility for growing companies.

    This website is for informational purposes only and is not investment advice.

    Structuring Mezzanine Debt for Acquisitions and Growth

    As we move from senior to mezzanine structures, the role of hybrid capital becomes central to bridging funding gaps in complex transactions. Mezzanine debt structures occupy a unique position in the capital stack, sitting below senior obligations but above equity. At Zaidwood Capital, we structure these instruments as part of our full-cycle debt advisory, delivering flexible junior capital solutions for acquisitions and growth. While we leverage our network of over 4,000 institutional investors to source capital, we are not a registered broker-dealer and do not offer investment advice — please consult your own advisors before making financing decisions.

    The following table compares three common junior capital solutions used in acquisition financing:

    Mezzanine vs Unitranche vs Subordinated Debt
    FeatureMezzanine DebtUnitranche DebtSubordinated Debt
    StructureTwo-tranche (senior + sub) or standaloneSingle blended loan (senior + mezzanine combined)Strictly junior to senior debt
    Pricing10-18% all-inLIBOR + 500-800 bpsLIBOR + 600-900 bps
    CovenantsIncurrence-based, may include equity kickerMaintenance covenants typicalLess restrictive than senior
    Best Use CaseAcquisition financing with hybrid return profileMid-market borrowers seeking simplified documentationBridge financing or recapitalizations

    Each solution serves a distinct purpose, and the choice depends on the sponsor’s appetite for complexity, covenant flexibility, and return targets.

    Typical Interest Rates and Terms in 2026

    Current market conditions make mezzanine financing particularly relevant, with all-in pricing typically ranging from 10% to 18%. This spread includes a cash pay component tied to benchmark rates — often LIBOR-based — plus payment-in-kind interest and an equity kicker in the form of warrants. According to Zaidwood Capital’s internal CADE FAQ, the precise split between cash and PIK depends on transaction risk, while the warrants enhance the lender’s yield to compensate for junior security. Upfront fees, prepayment penalties, and structuring charges are also common, and we work with borrowers to model these layers so the total cost of capital remains transparent. In 2026, sustained demand from private equity firms and family offices continues to support a borrower-friendly but disciplined underwriting environment.

    The Role of Mezzanine in Buy-Side Transactions

    Mezzanine debt structures shine in leveraged buyouts and growth-capital raises where senior debt capacity alone falls short of the required enterprise value. By layering a junior tranche, sponsors can increase total leverage without ceding control — an approach we use frequently when advising on buy-side mandates. For emerging markets m&a acquisitions, where projected transaction volumes may surge 15% annually, mezzanine provides a flexible bridge that absorbs country and currency risks while preserving equity upside. The equity kicker aligns lender and sponsor incentives, allowing the financing to behave almost as quasi-equity, which is valuable in high-growth sectors like fintech or renewables. Our debt advisory team draws on the firm’s CADE FAQ and transaction experience to calibrate the right mix of senior debt, mezzanine, and equity for each acquisition.

    Integrating with Unitranche and Subordinated Debt

    In more complex capital structures, mezzanine debt is often combined with unitranche debt or subordinated debt financing to optimize the cost and documentation burden. Unitranche — a single blended loan — appeals to mid-market sponsors with its simplicity and maintenance covenants, but it may lack the return-enhancing features of a standalone mezzanine piece. When we integrate mezzanine with subordinated debt financing, the subordinated layer acts as a bridge facility or recapitalization tool sitting just above equity, while the mezzanine tranche retains its hybrid character. This layered approach can lower the weighted-average cost of capital and satisfy both covenant-light investors and lenders seeking higher yields. Zaidwood Capital’s internal CADE FAQ highlights that such integrated structures are especially common in emerging-market M&A and resource-intensive sectors, where bespoke terms and patient capital are essential. Our role is to design the sequencing — senior, unitranche, mezzanine, subordinated — so that the overall package meets the client’s strategic and liquidity objectives.

    Practical Framework for Evaluating Mezzanine Financing Options

    With a clear understanding of mezzanine basics, we now present a practical evaluation framework. For executives and private equity sponsors, selecting the right financing structure is critical to maximizing returns and minimizing risk. Our advisory team at Zaidwood Capital has developed this decision-focused guide to help you assess whether mezzanine debt structures align with your acquisition strategy and capital stack requirements.

    When to Choose Mezzanine Over Senior Debt

    Senior debt typically reaches its limit at 3-4x EBITDA, constrained by collateral coverage and maintenance covenant requirements. When additional capital is needed to close a transaction or fund growth initiatives, but further senior lien capacity is exhausted, mezzanine financing becomes a strategic solution. Unlike senior lenders who require secured collateral, mezzanine providers accept an unsecured or subordinated position, relying on cash flow analysis rather than hard asset coverage. This flexibility proves essential when the target company has limited fixed assets but strong, predictable free cash flow.

    In our experience, the decision often comes down to a trade-off between cost and flexibility. While unitranche debt can offer a simpler, single-document structure that blends senior and subordinated tranches, it typically provides less flexibility than a bifurcated capital structure. A unitranche facility may restrict prepayment options and lack the warrant overlay that aligns mezzanine investors with equity upside. We recommend evaluating your specific covenant tolerance and exit horizon before choosing between these subordinated alternatives.

    Step-by-Step Structuring for Private Equity Deals

    Structuring mezzanine financing requires a methodical approach to balance the interests of sponsors, senior lenders, and subordinated investors. Our framework follows a five-stage process refined through over 300 completed transactions.

    Diagram showing five stages of a mezzanine financing evaluation process from initial mandate to post-closing monitoring with downward arrows connecting each stage

    Five-stage mezzanine financing evaluation process flow diagram

    The process begins with the initial mandate and underwriting phase, where we assess the target company’s credit profile, historical cash flows, and projected debt service capacity. This determines the appropriate sizing of the subordinated debt financing tranche, typically targeting a total leverage level of five to seven times EBITDA inclusive of senior debt.

    Next, term sheet negotiation addresses the critical economic and control terms. Warrant coverage—the equity kicker that enhances investor returns—is negotiated alongside the cash coupon and any payment-in-kind (PIK) toggle features. When negotiating warrant terms, it is important to ensure alignment with global capital market standards to maintain market conformity and facilitate syndication if needed. The amortization schedule for mezzanine is often back-end loaded, with minimal principal payments during the early years to preserve portfolio company cash flow. Legal documentation and the intercreditor agreement then codify the relative rights of senior and subordinated lenders, followed by closing, funding, and post-closing covenant monitoring.

    Benefits of Mezzanine in Acquisition Financing

    Mezzanine financing offers distinct advantages that make it a powerful tool in acquisition capital structures. Based on our proprietary benefit analysis, the most compelling attribute is its function as a bridge to equity without immediate dilution. Existing shareholders retain full ownership and control, while any equity participation via warrants is deferred and typically limited in scope. Unlike equity investors, mezzanine providers generally do not require board seats, preserving operational control for management.

    From a cost perspective, mezzanine debt structures carry an all-in cost of 10 to 18 percent, and critically, the cash interest component is tax-deductible. This contrasts sharply with equity financing, where investors target a 20 to 30 percent internal rate of return through capital appreciation and dividends that are not deductible to the company. The effective after-tax cost advantage makes mezzanine an efficient instrument for bridging valuation gaps in competitive auction processes.

    The following matrix helps executives compare mezzanine debt and equity on key decision criteria.

    Mezzanine Debt vs Equity: Decision Matrix for Acquisition Financing
    CriteriaMezzanine DebtEquity Financing
    DilutionMinimal (via warrants or conversion on limited basis)Full dilution of existing shareholders
    Cost of Capital10-18% all-in (tax-deductible interest)Target IRR 20-30% (higher required return)
    ControlNo board seats typically; covenants onlyInvestors often receive board representation
    FlexibilityPrepayment options vary, call protection commonExit required for liquidity; no redemption schedule
    Best ForCompanies with stable cash flow seeking bridge capitalHigh-growth companies needing strategic guidance and long-term capital

    This framework, informed by industry benchmarks and Zaidwood Capital case studies, provides a practical lens for evaluating trade-offs. The choice between subordinated debt and equity ultimately depends on your liquidity horizon, control preferences, and the underlying predictability of portfolio company earnings. To see how these structures work in practice, refer to our case studies below. This is for informational purposes only; consult your financial advisor before making financing decisions.

    Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer and is separate from Finalis. Past performance does not guarantee future results.

    Advanced Considerations: Risk Allocation, Leverage Ratios, and Investor Alignment

    Building on our earlier discussion of baseline financing options, we now turn to the sophisticated structural elements that define effective mezzanine debt structures. For sponsors and companies evaluating growth capital, understanding risk allocation, leverage benchmarks and alignment mechanisms separates a well-structured transaction from one that introduces unintended friction. We focus here on the analytical framework Zaidwood Capital applies when advising clients through these complex capital stack decisions.

    Risk Allocation and Intercreditor Dynamics

    Risk allocation in mezzanine financing centers on contractual subordination and the intercreditor agreement. This agreement governs the relationship between senior and mezzanine lenders, defining payment waterfalls, standstill periods and remedies upon default. Because mezzanine debt sits behind senior obligations, recovery in a downside scenario depends heavily on how these provisions are drafted. We structure intercreditor terms that preserve mezzanine lender rights while respecting senior creditor priority, ensuring each party understands its position before capital is deployed.

    Leverage Ratio Benchmarks Across the Capital Structure

    Leverage ratios, typically expressed as Debt/EBITDA, provide a common yardstick for assessing financial risk. The table below summarizes the benchmarks we observe across Zaidwood Capital transactions and broader industry data:

    Leverage Ratio Benchmarks by Debt Type
    Debt TypeLeverage Ratio (Debt/EBITDA)Typical Uses
    Senior Debt2.5x – 4.0xRevolving credit, term loans
    Mezzanine Debt0.5x – 2.0x (on top of senior)Acquisition bridge, growth capital
    Unitranche Debt3.5x – 5.5x (combined)Mid-market leveraged buyouts
    Subordinated Debt1.0x – 2.5xRecapitalizations, rescue financing

    These ranges illustrate how each debt layer contributes to total leverage. Senior debt anchors the structure, while mezzanine facilities layer on additional capacity, typically 0.5x to 2.0x above the senior component. For unitranche debt, the combined ratio reaches materially higher levels, creating a different risk-return profile for investors.

    Higher leverage amplifies equity returns but also increases vulnerability to earnings volatility. Recent SEC regulatory updates reinforce the need for transparent leverage disclosure and risk retention compliance, particularly for structures that push total leverage beyond historical norms. We monitor these regulatory developments closely, as they directly influence structuring options and documentation standards for mezzanine and subordinated debt financing.

    Investor Alignment Mechanisms

    Aligning interests between debt holders and equity sponsors requires deliberate structural features. Beyond the base coupon, we often incorporate PIK interest components that preserve cash flow for operational needs while compounding value for lenders. Warrants or equity co-investment rights give mezzanine investors participation in upside, matching their risk exposure with potential reward. Board observer rights provide visibility into strategic decisions without impairing management autonomy, and change-of-control provisions ensure lenders are protected — or compensated — if ownership transitions occur.

    These mechanisms transform a simple debt instrument into a partnership-oriented capital solution. Sponsors benefit from flexible financing terms while investors gain safeguards and upside exposure that senior creditors typically do not receive.

    In the next section we explore how these structural considerations feed into the due diligence process and real-world case examples.

    This content is for informational purposes only and does not constitute investment advice. Readers should consult their own legal, tax and financial advisors before making any decisions.

    Frequently Asked Questions About Mezzanine Debt Structures

    What Are Mezzanine Debt Structures?

    Mezzanine debt structures sit between senior secured debt and equity in a company’s capital hierarchy. This financing is typically unsecured and subordinated to first-lien lenders, meaning it carries higher risk but also commands higher returns. A key feature of mezzanine financing is its equity participation component — often through warrants or conversion rights — which gives lenders upside potential beyond fixed interest payments.

    How Does Mezzanine Financing Compare to Unitranche Debt?

    While both are flexible capital solutions, unitranche debt blends senior and subordinated tranches into a single facility with one blended interest rate. In a mezzanine debt structure, the layers remain distinct: a senior lender holds first priority, and the mezzanine provider sits behind them. Unitranche simplifies administration but may limit the equity upside that defines mezzanine financing.

    What Are the Typical Uses for Mezzanine Debt?

    Companies commonly use subordinated debt to fund acquisitions, support growth capital initiatives, and execute recapitalizations. Because mezzanine financing does not require hard asset collateral, it is especially useful for businesses whose value lies in cash flows or intellectual property rather than physical assets. This flexibility makes it a go-to tool for middle-market transactions and sponsor-backed deals.

    How Does Mezzanine Debt Relate to Subordinated Debt Financing?

    Mezzanine debt is a form of subordinated debt financing, distinguished by its equity-linked features. All mezzanine instruments rank below senior obligations, but not all subordinated debt includes warrants or conversion rights. The additional return potential compensates mezzanine providers for their deeper position in the repayment waterfall.

    What Are the Main Risks of Mezzanine Financing?

    Because mezzanine debt is unsecured and junior to senior loans, recovery in a default scenario can be significantly lower. The higher interest cost also increases the financial burden on the borrower. However, for companies with stable cash flows and strong growth trajectories, the risk-return trade-off of a mezzanine debt structure can be strategically sound. Please note that all investments involve risk, and past performance does not guarantee future results; you should consult your legal, tax, and financial advisors before making decisions.

    Optimizing Your Capital Structure with Mezzanine Debt

    In our advisory work, we often position clients to benefit from hybrid instruments in mezzanine debt structures, which sit between senior obligations and common equity. This subordinated layer can strengthen the balance sheet while preserving ownership control.

    What Is Mezzanine Debt?

    We define this as subordinated debt financing that includes equity participation features, such as warrants, allowing lenders to share in upside without diluting founders prematurely.

    How It Optimizes Capital Structure

    By layering mezzanine capital above equity, companies reduce dilution and gain flexible repayment options like payment-in-kind interest. This bridge is particularly useful for acquisitions, management buyouts, and growth-stage expansion.

    Mezzanine vs. Unitranche vs. Senior Debt

    Feature Mezzanine Debt Unitranche Debt Senior Debt
    Position in capital structure Junior to senior, senior to equity Single blended tranche Most senior
    Interest rate type Higher fixed or floating with PIK Blended rate; typically floating Lowest, often floating
    Covenant strictness Fewer financial covenants Moderate Strictest
    Equity component Warrants or equity kickers common Usually none None
    Typical use case Acquisitions, buyouts, recapitalizations Mid-market LBOs, quick close Working capital, asset-heavy deals

    Unitranche debt blends senior and subordinated layers into one facility, while subordinated debt financing remains a more traditional second-lien or junior note. We help management teams evaluate each path against their capital needs and timeline.

    Trade-offs and Customization

    Mezzanine capital carries higher interest and potential equity give-ups, but it provides speed and fewer restrictive covenants than senior loans. Through our debt advisory services at Zaidwood Capital, we structure each facility to match a company’s cash flow profile without promising any specific outcome.

    This section is for informational purposes only and does not constitute investment advice. Consult your legal, tax, and financial advisors before making decisions. Securities are offered through Finalis Securities LLC; Zaidwood Capital is not a registered broker-dealer.

    Resources

  • Private Equity Continuation Funds: Complete Guide for Investors

    Private Equity Continuation Funds: Complete Guide for Investors

    Table of Contents

    Private equity continuation funds explained

    Private equity continuation funds are GP-led secondary transactions where a new fund vehicle is established to hold existing portfolio assets beyond the original fund’s term. These structures can be arranged as single-asset continuation vehicles or as multi-asset pools. The objective is twofold: they provide limited partners with an early liquidity mechanism while enabling the general partner to continue managing and growing the assets.

    In a typical transaction, the GP sponsors the new vehicle and offers existing LPs a choice — a cash exit at a reset valuation or the opportunity to roll their interests into the successor fund. This approach aligns incentives and can supply follow-on capital for further value creation.

    For fund managers, executing a continuation fund requires specialized capital-raising and placement capabilities. Learn more about our capital formation services. This is not investment advice — consult your professional advisors.

    How Private Equity Continuation Funds Work

    Private equity continuation funds, also known as GP-led secondary transactions, are sophisticated financial vehicles that allow general partners to extend their holding period for high-potential portfolio companies or assets. At Zaidwood Capital, we have observed a significant increase in GP-led secondary transactions as fund managers seek innovative ways to maximize returns for their investors. These structures provide liquidity options for existing limited partners while enabling continued value creation in promising investments.

    The core mechanism involves a GP initiating a GP-led secondary transaction by transferring assets from an existing fund into a newly formed continuation vehicle. This process typically includes both existing LPs and new institutional investors, with the GP retaining a significant stake to demonstrate confidence in the assets’ future performance and align interests across all parties involved.

    Flowchart of a GP-led continuation fund transaction with five connected stages in a professional blue and gray palette

    GP-led continuation fund transaction process flow

    The transaction flow illustrated above demonstrates how these complex structures come together. The process begins with asset identification and valuation, followed by the formation of the new vehicle, capital raising from both new and existing investors, and ultimately the transfer of assets to the continuation fund.

    Financing plays a critical role in structuring these transactions, and debt advisory services from Zaidwood Capital can provide the necessary financing structures for these funds. According to Zaidwood Capital’s internal knowledge resources, our Full-Cycle M&A and capital advisory practice encompasses mezzanine debt, venture debt, and asset-based lending structures that support GP-led secondary transactions. With access to over 4,000 institutional investors and $15 billion in deployable capital, we help structure the optimal financing package for each unique situation.

    The valuation process requires rigorous fairness opinions and third-party advisory to ensure alignment with LP interests. Independent valuation firms assess the transferred assets to establish a fair market price, protecting all stakeholders involved in the transaction.

    Continuation funds can be structured as single-asset continuation vehicles or multi-asset vehicles, depending on the GP’s strategic objectives. A single-asset continuation vehicle focuses on one high-conviction portfolio company, while multi-asset structures consolidate several related holdings. These structures have become increasingly prevalent in today’s private equity landscape, offering flexible solutions for portfolio optimization and extended value creation timelines.

    GP-Led Secondary Transactions and Single-Asset Vehicles

    GP-led secondary transactions have become a defining feature of today’s private equity landscape, driven by the growing use of private equity continuation funds. In a GP-led deal, a general partner facilitates the sale of existing limited partner interests to new investors, often by transferring a portfolio company into a newly created continuation fund. This structure gives both continuing and exiting LPs greater flexibility than a traditional fund liquidation.

    A prominent subset of these transactions is the single-asset vehicle. Here, a single portfolio company is moved into a standalone fund, allowing the GP to hold a high-performing asset beyond the original fund’s life. This approach unlocks the runway needed for additional value creation while providing immediate liquidity to LPs who wish to exit. In our experience, these vehicles also enable more tailored governance terms and focused board oversight, which can accelerate strategic initiatives and operational improvements, provide clearer reporting metrics for investors concentrated on concentration risk and exit timing, and support alignment of incentives among continuing stakeholders while preserving LP choice and protections. We have seen demand for single-asset continuation vehicles increase significantly as GPs seek longer holding periods for prized assets.

    Why do GPs favor these structures? First, they can retain top-performing companies rather than selling them prematurely. Second, they raise follow-on growth capital to fund expansion or acquisitions. Third, they offer existing LPs a clear choice: cash out at fair value or roll their interest into the new vehicle. These transactions typically require independent valuations and approval from the LP advisory committee, ensuring alignment with capital market standards for secondary processes.

    At Zaidwood Capital, we advise clients on navigating these transactions from initial structuring through close. Our work in the private equity secondary market confirms that well-designed continuation funds balance the interests of all parties while capturing additional upside. The next section explores the valuation techniques that underpin fairness opinions in these evolving deal structures.

    Several interrelated factors explain this surge in popularity. We see that private equity continuation funds have become a cornerstone of liquidity solutions in 2026, driven by regulatory clarity, market demand for flexible exits, and the structural innovation of GP-led transactions.

    The U.S. Securities and Exchange Commission (SEC) has been a primary catalyst for this growth. SEC investor protection has been a key priority, with the SEC strengthening its initiatives to oversee GP-led secondary transactions. Through proposed rule changes and enforcement priorities, the regulator has clarified the framework for exempt offerings and secondary market activity, making it easier for fund managers to structure continuation vehicles that safeguard investor interests while providing much-needed transactional certainty.

    Market demand for liquidity solutions has further accelerated the trend. Institutional investors are increasingly turning to these structures to realize partial or full exits without triggering forced asset sales that could dilute returns. Private equity continuation funds give LPs the flexibility to recycle capital while GPs retain high-performing assets for further value creation. With fund lifespans extending beyond traditional horizons, the ability to execute gp-led secondary transactions has become essential for aligning the longer-term interests of managers and their limited partners.

    Structurally, the rise of single-asset continuation vehicles has been a defining feature of this cycle. These vehicles bundle a single portfolio company into a new fund, allowing the GP to extend the investment period and pursue additional growth while offering existing LPs the choice to liquidate or roll their interests. This targeted approach has gained traction as a flexible way to manage concentrated positions, reduce portfolio complexity, and align incentives without the legal and operational burden of full-fund restructurings. These examples show private equity continuation funds balance liquidity needs with longer-term investment horizons overall.

    Having examined the drivers, we now turn to the mechanics of these transactions and how they are structured to meet the needs of sponsors and investors alike.

    Benefits and Risks for LPs and GPs

    For GPs considering a continuation fund, the strategic advantages are compelling. Private equity continuation funds allow general partners to access liquidity from older fund portfolios without forcing a premature sale of assets that still have meaningful upside potential. We see this as a powerful tool that aligns interests by giving GPs the ability to extend their management of high-performing assets—particularly through the use of single-asset continuation vehicles—while simultaneously offering limited partners a clear choice between realizing gains and maintaining exposure. From an LP perspective, this structure provides valuable optionality. Rather than facing a binary outcome when a fund nears the end of its life, investors receive a liquidity event for their legacy fund interests coupled with the ability to roll over their commitment if they believe in the continued growth trajectory of the underlying portfolio.

    However, these transactions are not without complexity. One of the most persistent challenges lies in determining a fair market price for inherently illiquid assets, which requires rigorous third-party valuation work and independent fairness opinions. The inherent GP–LP conflict of interest sits at the center of every GP-led secondary transaction—the GP serves as both sponsor of the existing fund and, effectively, the buyer in the new continuation vehicle. To manage this, we advise clients to insist on transparent disclosure, independent governance structures, and the active involvement of legal and financial advisors who represent LP interests throughout the process.

    All GP-led secondary transactions are subject to FINRA regulatory compliance standards, including requirements for fairness opinions and transparent disclosure. When a broker-dealer such as Finalis Securities LLC is engaged, adherence to FINRA rules is mandatory. The Financial Industry Regulatory Authority (FINRA) establishes the regulatory framework that governs how securities firms involved in these transactions must operate, providing a baseline of investor protection through its oversight of disclosure practices, fair-dealing obligations, and conflict-of-interest management. This regulatory overlay reinforces the governance discipline that sophisticated LPs should demand.

    We emphasize that continuation funds are not risk-free. LPs should carefully evaluate the GP’s track record with similar structures, the specific governance protections built into the transaction, and whether the continuation vehicle genuinely aligns with their portfolio objectives. When structured thoughtfully and governed transparently, continuation funds can serve as a valuable liquidity and portfolio management solution—but the burden of due diligence rests squarely on all parties involved.

    This content is for informational purposes only and does not constitute investment advice or an offer, solicitation, or recommendation to transact. Investments involve risk and may be illiquid; investors may lose all or part of their investment. Zaidwood Capital LLC is not a registered broker-dealer. Securities are offered through Finalis Securities LLC, a separate entity.

    Best Practices for Evaluating Continuation Fund Opportunities

    Private equity continuation funds represent a growing segment of GP-led secondary transactions where a general partner transfers one or more portfolio assets from an existing fund into a new vehicle under the same management. While these structures can offer extended value-creation runway and fresh capital, they demand rigorous investor scrutiny to ensure the transaction serves limited partner interests fairly. We believe a methodical evaluation framework is essential for any LP assessing such opportunities.

    At the core of every analysis are several critical factors. First, we examine GP incentive alignment—specifically whether the manager is committing meaningful co-investment capital to the continuation vehicle and how the fee structure impacts net returns. Second, the fairness of the valuation process requires close attention, including whether an independent third-party opinion has been obtained and how the pricing compares to recent market benchmarks. Third, the composition and independence of the oversight committee or advisory board play a vital role in mitigating conflicts of interest, as does the transparency of disclosure around any existing GP–LP dynamics that may influence the proposed transaction.

    A thorough review must also consider the fund’s historical track record and the strategic rationale for retaining the asset rather than pursuing an outright sale. Investors should scrutinize the fee structure carefully, including management fees, any transaction-related costs, and the impact on carried interest calculations. Zaidwood Capital notes that evaluating the underlying financing terms is equally important, and our debt advisory team often helps clients analyze leverage arrangements embedded in continuation fund structures to ensure they align with long-term value-creation objectives. We also evaluate exit timing, market receptivity, and operational improvement plans to ensure the continuation path is realistic and achievable over time.

    These due diligence pillars—alignment, valuation integrity, independent oversight, and fee transparency—form the foundation of informed LP decision-making in GP-led secondary transactions. With these best practices in mind, our team can assist in structuring and vetting such opportunities.

    Key Takeaways and Next Steps in Continuation Fund Strategy

    Our earlier sections laid out how private equity continuation funds serve as flexible structures that extend fund life and deliver intermediate liquidity. These vehicles allow general partners to hold prized assets longer while giving limited partners options to roll over or exit.

    GP-led secondary transactions and single-asset continuation vehicles form the core of this strategy, aligning sponsor and investor interests through transparent pricing and governance. At Zaidwood Capital, we advise on structuring these transactions, from selecting the appropriate vehicle to managing the reinvestment process.

    As you evaluate your next move, you may consider:

    • Reviewing your current fund documents and limited partnership agreements for rollover provisions.
    • Weighing single-asset continuation funds against multi-asset GP-led solutions based on your portfolio concentration and return objectives.
    • Engaging a capital advisor experienced in secondary transactions and structured liquidity events.

    Our Continuation Fund FAQ details common questions, and we invite you to book a discovery call for tailored guidance on your specific situation.

    Resources

  • Smart Manufacturing: Complete Guide for 2026

    Smart Manufacturing: Complete Guide for 2026

    Table of Contents

    Smart Manufacturing Defined for 2026

    Building on manufacturing’s evolution toward digital integration, smart manufacturing in 2026 represents interconnected systems leveraging IoT, AI, and data analytics for real-time optimization. These smart manufacturing ecosystems enable factories to adapt dynamically, minimizing waste and maximizing output through advanced automation.

    NIST’s smart manufacturing systems provide the foundation via three pillars: cyber-physical systems integration for seamless machine-human collaboration; real-time data analytics for predictive insights; and autonomous decision-making for self-optimizing operations. Authoritative U.S. government standards from the National Institute of Standards and Technology (NIST) emphasize model-based practices, digital threads, and industrial AI metrology. NIST research emphasizes model-based practices, digital threads, and industrial AI metrology, and promotes tools for systems modeling, heterogeneous data fusion, and trusted lifecycle data to support interoperable, measurable, and repeatable smart manufacturing deployments across complex supply chains with clear metrics and standards globally.

    2026 Key Tech: Digital Twins & AI

    Digital twins in manufacturing simulate production lines virtually, while ai predictive maintenance forecasts failures to slash downtime.

    By 2026, these yield 20-30% efficiency gains and cost reductions, per NIST benchmarks and industry data.

    At Zaidwood Capital, we view smart manufacturing as a high-growth sector ripe for investment. While defined by these principles, deploying smart manufacturing requires addressing implementation challenges ahead.

    Core Principles of Smart Manufacturing

    Building on these foundations, the core principles of smart manufacturing revolve around integrating Internet of Things (IoT), artificial intelligence (AI), big data, and cyber-physical systems to create adaptive production environments. This approach transforms static factories into dynamic, responsive operations known as smart factories or Industry 4.0 manufacturing. According to the National Institute of Standards and Technology (NIST), these principles drive innovation and competitiveness in modern industry.

    Full Automation. Traditional manual and semi-automated processes give way to AI and IoT-driven full automation. We see ai predictive maintenance playing a pivotal role, where AI algorithms anticipate equipment failures, minimizing downtime and optimizing workflows. NIST guidelines on manufacturing systems design analysis highlight how this shift enhances reliability and efficiency.

    Real-Time Data Utilization. Siloed, reactive data is replaced by real-time analytics powered by big data. Digital twins in manufacturing enable simulation-based optimization, allowing virtual replicas of physical assets for testing scenarios without real-world risks. NIST research, cited as authoritative U.S. government frameworks, underscores data analytics for smart manufacturing to support informed decision-making.

    Seamless Connectivity. Isolated machines evolve into interconnected cyber-physical systems integration in manufacturing systems design, fostering machine interoperability. National Institute of Standards and Technology (NIST) systems integration frameworks provide standards for this connectivity, enabling resilient production networks as per government research on manufacturing systems integration.

    The following table illustrates key differences:

    Traditional vs. Smart Manufacturing

    Key Differences in Core Principles and Technologies (Data sourced from NIST manufacturing systems research and industry benchmarks for 2026 projections)

    Traditional vs. Smart Manufacturing
    AspectTraditional ManufacturingSmart Manufacturing
    Manual and semi-automated processesLimited roboticsAI and IoT-driven full automation
    Reactive, siloed dataPaper-based or basic ERPReal-time analytics and big data
    ConnectivityNo interoperabilityCyber-physical systems integration

    This comparison, drawn from NIST manufacturing systems design analysis, reveals how smart manufacturing principles outperform traditional methods in adaptability and efficiency. For instance, full automation reduces human error, while real-time data empowers proactive strategies. These shifts position Industry 4.0 manufacturing for scalable growth, aligning with NIST’s emphasis on cyber-physical advancements.

    Infographic comparing traditional and smart manufacturing across automation, data utilization, and connectivity with illustrative icons

    Traditional vs Smart Manufacturing comparison visualization

    Key Technologies Driving Smart Manufacturing

    Delving deeper into smart manufacturing, interconnected technologies like IoT, AI, and digital twins enable real-time data flow, predictive insights, and optimized operations for intelligent factories.

    IoT and Sensor Integration

    IoT and sensor integration form the foundation of smart manufacturing by enabling continuous real-time data collection across production lines.

    Sensors embedded in machinery capture vital metrics such as temperature, pressure, and vibration, transmitting data via IoT networks for immediate analysis. This connectivity allows factories to monitor equipment health proactively. For instance, vibration sensors on assembly lines detect imbalances early, preventing breakdowns.

    • Pressure sensors in hydraulic systems alerting to leaks.
    • Temperature monitors on motors to avoid overheating.

    AI and Machine Learning Applications

    AI and machine learning revolutionize smart manufacturing with predictive analytics and automation, transforming raw data into strategic advantages.

    These technologies excel in anomaly detection and process optimization, forecasting issues before they escalate. In ai predictive maintenance, machine learning identifies patterns to schedule upkeep efficiently, minimizing disruptions.

    AI Tools for Predictive Maintenance
    TechnologyCapabilitiesUse Case
    Machine LearningPattern recognition in dataAnomaly detection
    Deep LearningImage and sensor analysisAdvanced forecasting

    Digital Twins in Operations

    Digital twins in manufacturing create virtual replicas of physical assets, enabling simulation and real-time optimization per smart manufacturing technologies.

    The National Institute of Standards and Technology (NIST), through its authoritative U.S. government standards and research on digital twin technologies, supports SMEs via the Digital Twin Laboratory—a testbed for development and interoperability.

    Implementing Smart Manufacturing Practices

    Transition Roadmaps

    1. Assess current infrastructure: Evaluate legacy equipment compatibility and data silos.
    2. Pilot IoT sensors: Deploy on one production line to monitor real-time performance.
    3. Implement digital twins in manufacturing: Use simulation tools like NIST-inspired models to test scenarios without risk.
    4. Scale with AI analytics: Integrate data fusion for predictive insights.
    5. Establish digital thread: Ensure lifecycle data interoperability per NIST guidelines.
    6. Monitor and iterate: Use tools like SimPROCESD for discrete-event simulation.

    Overcoming Adoption Barriers

    Barriers to Smart Manufacturing Adoption
    BarrierImpactMitigation
    High Initial CostsCapital expenditure strainPhased investment, financing
    Skills GapLack of expertiseTraining programs

    Change Management Essentials

    • Leadership commitment: Align C-suite on smart factory implementation vision.
    • Comprehensive training: Hands-on sessions for IoT and AI systems.
    • Communication strategies: Regular updates to build trust.
    • Continuous monitoring: Track KPIs like uptime and efficiency.

    Advanced Smart Manufacturing Strategies

    Edge Computing

    Cloud Computing

    Digital Twins in Manufacturing

    AI Predictive Maintenance

    Advanced Tech Stacks
    StrategyEdge ComputingCloud Computing
    LatencyLowHigh
    ScalabilityLimitedHigh

    Smart Manufacturing FAQs

    • What is smart manufacturing?
      Smart manufacturing integrates IoT, AI, and data analytics for real-time production optimization and efficiency gains.
    • How do digital twins enhance manufacturing?
      Digital twins in manufacturing create virtual replicas to simulate processes, predict issues, and reduce downtime.
    • What role does AI predictive maintenance play?
      ai predictive maintenance uses machine learning to forecast equipment failures, minimizing disruptions.

    Future of Smart Manufacturing

    Building on today’s foundations, smart manufacturing will evolve through advanced integration by 2030, guided by National Institute of Standards and Technology (NIST) frameworks as authoritative U.S. government technical standards.

    This article was researched and written with the assistance of AI tools.

    Resources

  • PEO vs ASO Comparison: Complete Benefits and Costs Guide

    PEO vs ASO Comparison: Complete Benefits and Costs Guide

    Table of Contents

    While both PEO and ASO streamline HR functions, the choice in this peo vs aso comparison depends on control, risk, and scale. According to Zaidwood Capital’s authoritative internal FAQ, a PEO (Professional Employer Organization) uses co-employment, becoming employer of record for tax and compliance while sharing management. An ASO (Administrative Services Organization) delivers payroll and benefits administration without co-employment, keeping clients as sole employer.

    Key differences include:

    • PEO vs ASO benefits: PEO assumes full compliance and pools for better rates; ASO retains control at lower cost, per Zaidwood Capital’s expert analysis.
    • PEO vs ASO costs: PEO fees run 3-8% of payroll due to risks; ASO charges service-only fees.

    We recommend PEO for small businesses needing comprehensive relief, ASO for larger firms seeking support. Once selected, here’s how to get started with your PEO or ASO.

    1. Master Key Differences

    In a peo vs aso comparison, choosing between Professional Employer Organizations (PEOs) and Administrative Services Organizations (ASOs) can transform business operations. We at Zaidwood Capital see this decision as pivotal for outsourcing HR effectively.

    Key Differences

    • Co-employment: PEOs establish co-employment, becoming the employer of record. PEO advantage: Comprehensive compliance support. ASO limitation: No shared employment status.
    • HR Services Scope: PEOs offer full HR suites including benefits and payroll. PEO benefit: Integrated solutions for peo vs aso benefits. ASO focus: Administrative tasks only.
    • Risk Sharing: PEOs assume liability for workers’ comp and compliance. PEO pro: Shared risks reduce client exposure. ASO con: Clients retain full liability.
    • Pricing Model: PEOs use fixed fees for predictability. PEO stability in peo vs aso costs. ASO variability: Pay-per-service billing.
    • Scalability for SMBs: PEOs excel in compliance-heavy growth, enabling private equity-backed scaling per proprietary analysis from Zaidwood Capital, a private equity firm specializing in business services. Structures appeal to private equity firms. PEO strength: Regulatory readiness. ASO flexibility: Quick adjustments.
    Infographic comparing PEO and ASO on co-employment, HR services, risk sharing, pricing, and scalability with icons and minimal labels

    Key differences between PEO and ASO services illustrated

    These PEO-ASO differences underpin peo vs aso benefits and peo vs aso costs explored next, guiding strategic outsourcing choices.

    2. Decode Co-Employment

    Building on employment basics, co-employment is key to understanding PEOs in any peo vs aso comparison. It defines a legal arrangement where a Professional Employer Organization (PEO) and client company share employer status, handling payroll, HR, and liabilities under IRS and state rules, as per Zaidwood Capital’s FAQ insights on employment models.

    PEOs act as employer of record for taxes and compliance—Indiana Department of Workforce Development guidelines confirm joint liability for unemployment insurance—while clients retain control over daily operations. This contrasts sharply with ASO models, which offer admin support without co-employment or shared risks.

    Key responsibilities:

    • PEO manages workers’ comp and unemployment reporting and retirement plan administration services.
    • Client oversees workplace safety and discrimination claims.

    Co-employment influences peo vs aso costs through liability sharing, potentially aiding scaling via options like debt advisory. With co-employment decoded, explore peo vs aso benefits and costs ahead.

    3. Unpack Service Ranges

    Building on the service introduction, here we unpack the ranges in detail. Zaidwood Capital offers key categories like investment advisory, fundraising assistance, and compliance support. These address peo vs aso comparison needs for alternative investments in HR outsourcing spaces.

    Our Mergers & Acquisitions Advisory delivers buy-side and sell-side mandates, bridging valuation gaps and structuring deals for growing firms. Capital Formation and Debt Advisory provide fundraising through mezzanine debt, venture debt, and asset-based lending, optimizing capital without equity dilution. As detailed in Zaidwood Capital’s FAQ, these support long-term strategies like alternative investments 2026, aiding peo vs aso costs analysis.

    Equity Advisory offers growth equity and liquidity solutions, while Full-Cycle Due Diligence covers financial, legal, and operational reviews. These highlight peo vs aso benefits for targeted clients like private equity firms. Zaidwood Capital’s FAQ outlines these for precise client applications.

    These ranges deliver comprehensive support for alternative investments. Key advantages are explored next.

    4. Break Down Costs

    Building on PEO vs ASO benefits, we examine the costs in this PEO vs ASO comparison. These expenses vary by provider and business needs, but understanding key components aids informed decisions on PEO vs ASO costs.

    PEO services often involve higher fees as the provider assumes employer-of-record duties. Typical costs include:

    • Payroll processing: 2-10% of payroll
    • HR administration and benefits management
    • Compliance support

    Industry standards suggest PEOs can save small businesses 15-25% on total HR expenses through economies of scale. Factors like employee count and industry add-ons influence pricing.

    ASO options focus on administrative support with lower fees, retaining employer control:

    • Administrative fees: often 1-3% of payroll
    • Benefits administration without risk transfer

    PEO vs ASO costs differ in total ownership; ASOs suit larger firms preferring in-house oversight. Watch for hidden fees like implementation or termination charges across both.

    Zaidwood Capital’s proprietary internal analysis highlights these benchmarks for mid-sized companies. With costs clarified, explore implementation steps ahead.

    5. Weigh the Benefits

    Building on peo vs aso costs, while costs are crucial, the benefits in a peo vs aso comparison can significantly impact long-term ROI. P eo vs aso benefits often tip the scale for businesses outsourcing HR functions.

    PEO offers comprehensive support through co-employment. Key advantages, per Zaidwood Capital FAQ insights, include:

    • Full HR compliance relief, handling regulations and audits.
    • Access to premium employee benefits at group rates.
    • Risk mitigation by transferring employment liabilities.
    • Streamlined payroll and onboarding.

    ASO provides flexibility without co-employment. Benefits highlighted in the same authoritative internal FAQ include:

    • Cost savings on payroll processing and administration.
    • Retained employer control over hiring and culture.
    • Customizable HR services tailored to needs.
    • Scalable solutions for growing firms.

    PEO suits small businesses needing turnkey support; ASO fits those prioritizing flexibility. Weigh your operations against these peo vs aso comparison factors. With benefits weighed, consider implementation next.

    6. Assess Small Biz Fit

    Building on PEO basics, now assess your fit. Wondering if your small business is ready for a PEO? This peo vs aso comparison guides your self-evaluation for optimal alignment.

    Key Fit Criteria

    • Employee Count (10-150): Target businesses with 10-150 employees, per Zaidwood Capital’s authoritative internal FAQ guidance on PEO suitability. A 25-employee tech firm saved 20% admin time via PEO fit assessment.
    • Administrative HR Burden: You face moderate-to-high HR admin loads. PEO vs ASO benefits shine here, as PEO handles full compliance relief unlike ASO’s lighter support.
    • Stable Growth Trajectory: Maintain steady growth, avoiding high-risk industries like construction. Zaidwood Capital FAQ stresses stable operations for best PEO results.
    • Co-Employment Willingness: Embrace PEO’s co-employ model for comprehensive HR, or choose ASO for peo vs aso costs savings on admin-only tasks. Weigh pros and cons carefully.

    Score your fit on a 1-10 scale. If 7+, contact Zaidwood Capital for tailored advice. If you fit well, explore next steps in implementation.

    7. Spot Risk Factors

    Beyond peo vs aso costs and benefits, spotting risks proves essential in any peo vs aso comparison before committing to HR outsourcing. Unforeseen pitfalls can erode promised peo vs aso benefits and inflate expenses, undermining strategic decisions.

    Beware of these critical risks in comparing PEO and ASO:

    • Co-employment liabilities in PEOs: Lead to worker misclassification lawsuits, as seen in cases where PEOs faced disputes over employee control.
    • Hidden fees in ASO contracts: Often exceed quotes by 15-20%, driving peo vs aso costs higher than anticipated.
    • Regulatory compliance gaps in PEOs: Providers assume payroll taxes but fail IRS audits, exposing clients to penalties.
    • Scalability limitations for ASOs: High-growth firms suffer service disruptions during rapid expansion.
    • Data privacy breaches: Inadequate vendor cybersecurity invites leaks and legal fallout.

    Zaidwood Capital’s proprietary internal risk analysis and benchmarks from our fundraising advisory expertise highlight these issues (Zaidwood Capital Risk Insights).

    Verify risks against provider track records using our insights. Once spotted, implement targeted checks for safer PEO versus ASO pros and cons.

    8. Drive Smart Choices

    Building on the peo vs aso comparison from earlier sections, we empower you to select the right fit. Understanding PEO versus ASO differences turns analysis into action. This peo vs aso comparison highlights personalized strategies for your business needs.

    Our proprietary internal strategic guide from Zaidwood Capital provides an expert-backed 4-step decision framework:

    1) Assess company size and HR complexity. Evaluate employee count and administrative demands.
    2) Weigh peo vs aso benefits like compliance versus flexibility. Match risk tolerance to advantages.
    3) Analyze peo vs aso costs, including setup fees and scalability. Project long-term financial impact.
    4) Schedule a consultation with Zaidwood Capital. Gain tailored insights.

    Use this self-evaluation checklist:

    • High growth trajectory? Favor ASO flexibility.
    • Risk-averse operations? Choose PEO compliance.
    • Complex benefits? Opt for PEO expertise.
    • Budget constraints? Prioritize ASO efficiency.

    Apply this framework now. Contact us at Zaidwood Capital for your smart choice.

    Optimal HR Outsourcing Strategy

    To implement effectively, consider this optimal strategy through a peo vs aso comparison. Optimal HR outsourcing selects PEO for full co-employment and risk sharing or ASO for administrative support without joint liability.

    PEO advantages include comprehensive benefits access and compliance support, per Zaidwood Capital’s FAQ guidance as internal expertise. ASO focuses on HR tasks while retaining employer control. Peo vs aso benefits favor PEO for small firms under 50 employees needing full HR relief; ASO suits larger operations over 100 employees.

    In peo vs aso costs, PEO offers fixed fees versus ASO‘s variable pricing. Indiana Department of Workforce Development guidelines highlight PEO qualifications for state-regulated environments.

    Strategy checklist:

    • Evaluate business size and HR complexity
    • Review in Indiana regulations

    Next, explore steps to select your provider.

    This article was researched and written with the assistance of AI tools.

    Resources